










MMP Industries Ltd Targets FY28 Growth From New Facilities
Key highlights
- MMP expects its aluminium wire rod facility to begin contributing from Q1 FY28.
- MMP's polymer insulator facility is ready, with optimum utilisation expected from Q2 FY28.
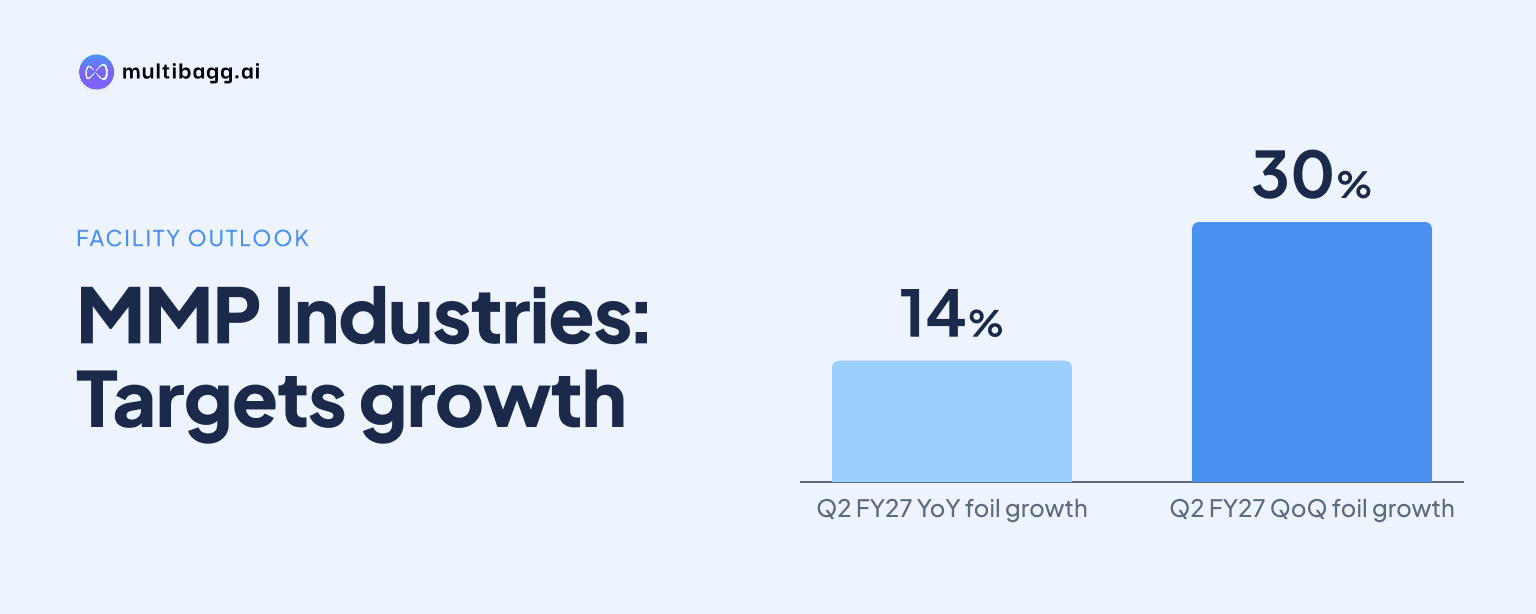
- Foil volume increased 14% year-on-year and 30% quarter-on-quarter in Q2 FY27.
- MMP reported an inventory valuation-related loss of about Rs. 2.5 crore in Q2 FY27.
powered by IRIS
MMP Industries Ltd expects its aluminium wire rod facility to begin contributing in Q1 FY28, while its ready polymer insulator unit is expected to make a meaningful contribution from the same quarter. The planned additions matter because MMP is expanding beyond its established aluminium powder operations, which supply about 80% of the requirement of India’s top four aluminium phosphide manufacturers.
Know MMP Industries inside out
Results, valuation, peers and who's buying, in one view.
What new facilities is MMP bringing into operation?
MMP Industries Ltd said its aluminium wire rod facility is at an advanced stage of completion and is scheduled to start contributing from Q1 FY28. Chief Financial Officer Sharad Khandelwal disclosed the timeline during the company’s Q2 and H1 FY27 earnings conference call held on November 3, 2026.
The polymer insulator facility is ready, according to the CFO. Management expects meaningful revenue contribution from Q1 FY28 and optimum utilisation from Q2 FY28. The project represents MMP’s move into products linked to India’s power transmission and distribution infrastructure.
The company is also expanding its low-tension cable business at Bhandara. Its smaller LT cable capacity has started operations and is expected to generate meaningful revenue from Q4 FY27. The larger LT cable capacity is expected to begin meaningful revenue contribution from FY29.
These timelines show that the new businesses will be phased in rather than become material simultaneously. Wire rods and polymer insulators are scheduled for contribution in early FY28, while the larger cable expansion has a longer lead time.
How did MMP’s key operating segments perform in Q2 FY27?
MMP reported mixed volume trends in Q2 FY27, with aluminium powder and foil recording growth while conductors declined. On a year-on-year basis, powder volume rose 2% and foil volume increased 14%, whereas conductor volume fell 33%.
Sequentially, powder volumes grew 8% and foil volumes rose 30%. Conductor volumes declined 10% quarter-on-quarter. The figures indicate stronger momentum in powder and foil during the quarter, but continued pressure in the conductor business.
Management also quantified an inventory valuation-related loss of about Rs. 2.5 crore in Q2 FY27. The company did not provide further detail in the available call extracts on the underlying inventory movement or its segment-wise allocation.
Toyal MMP India, an associate, reported Q2 FY27 revenue of Rs. 23.1 crore and profit after tax of Rs. 0.4 crore. This associate performance is separate from the operating-volume changes discussed for MMP’s main business segments.
Why is aluminium powder important to MMP’s business?
Aluminium powder remains MMP’s foundational business because it supplies about 80% of the aluminium powder requirement of India’s top four aluminium phosphide manufacturers. Aluminium phosphide is used as a grain fumigant, giving the company exposure to an established agricultural storage and pest-control application.
The company’s position in this market has been built over decades through consistent product quality, according to the information provided. This customer relationship base gives the powder segment strategic importance even as MMP adds wire rods, insulators and cables.
Earlier management commentary for FY27 had indicated an expectation of 13% to 15% revenue growth in the powder segment, supported by demand improvement, customer diversification, exports and operational efficiencies. That outlook was disclosed during the Q4 FY26 call and should be viewed as management guidance rather than a reported outcome.
In Q1 FY27, MMP reported revenue from operations of Rs. 232.6 crore, up 27.3% from Rs. 183.3 crore in Q1 FY26. EBITDA rose to Rs. 21.0 crore from Rs. 13.1 crore, while PAT was Rs. 13.7 crore compared with a loss of Rs. 5.4 crore in the previous-year quarter, which included an exceptional loss linked to a fire incident.
Got a follow-up? Ask IRIS
How do the expansion plans affect MMP’s financial profile?
The new facilities broaden MMP’s revenue base into power-sector-linked products, but their financial contribution will depend on commissioning, customer approvals and utilisation ramp-up. The company has specified contribution timelines, but the available Q2 FY27 call information does not provide revenue or profitability projections for the wire rod facility.
For polymer insulators, management had earlier indicated revenue expectations of Rs. 18 crore to Rs. 20 crore in FY27 and Rs. 45 crore to Rs. 50 crore in FY28. It had also indicated that the business could reach peak revenue of around Rs. 130 crore to Rs. 140 crore at full capacity. These are management expectations and are not reported financial results.
MMP had previously outlined capital commitments of about Rs. 15 crore for wire rods and about Rs. 90 crore for LT cables over two to three years. It also referred to approximately Rs. 30 crore of solar-power capex and Rs. 35 crore to Rs. 40 crore committed to the polymer insulator business.
What should investors monitor after the Q2 FY27 call?
Investors will be able to assess the expansion programme through the timing of commercial revenue, capacity utilisation and segment profitability once the facilities begin contributing. The immediate milestones disclosed by management are the Q4 FY27 revenue contribution from smaller LT cables and the Q1 FY28 start for wire rods and polymer insulators.
The conductor segment also remains relevant after its 33% year-on-year volume decline in Q2 FY27. Whether this trend stabilises, alongside the continuation of powder and foil volume growth, will influence the balance of MMP’s existing business performance before the new facilities scale up.
Raw-material pricing and inventory valuation are additional items to track. MMP reported a Rs. 2.5 crore inventory valuation-related loss in Q2 FY27, while management had earlier noted that raw-material price volatility and global uncertainties could affect near-term performance.
Conclusion
MMP is pursuing a broader product mix while retaining aluminium powder as its core business. The Q2 FY27 update showed improving sequential powder and foil volumes, weaker conductor volumes and a Rs. 2.5 crore inventory valuation-related loss. Its dominant supply position in the domestic aluminium phosphide value chain remains an important operating base.
The next disclosed milestones are meaningful revenue from the smaller Bhandara LT cable capacity in Q4 FY27, followed by contributions from wire rods and polymer insulators in Q1 FY28. Investors should watch execution against these timelines, the polymer insulator utilisation target for Q2 FY28 and the pace at which conductor volumes recover.