










MMP Industries H1 PAT jumps 1,516% as Q2 margins ease sequentially
Key highlights
- MMP Industries reported H1FY27 PAT of Rs 25.8 crore, up 1,516% from Rs 1.6 crore in H1FY26.
- MMP Industries' Q2FY27 EBITDA margin was 7.6%, down from 9.0% in Q1FY27.
- MMP Industries' Aluminium Powders revenue rose 41% to Rs 315 crore in H1FY27.
- MMP Industries targets Q4FY27 commercial production at its 18,000 metric-tonnes-per-annum wire-rod facility.
powered by IRIS
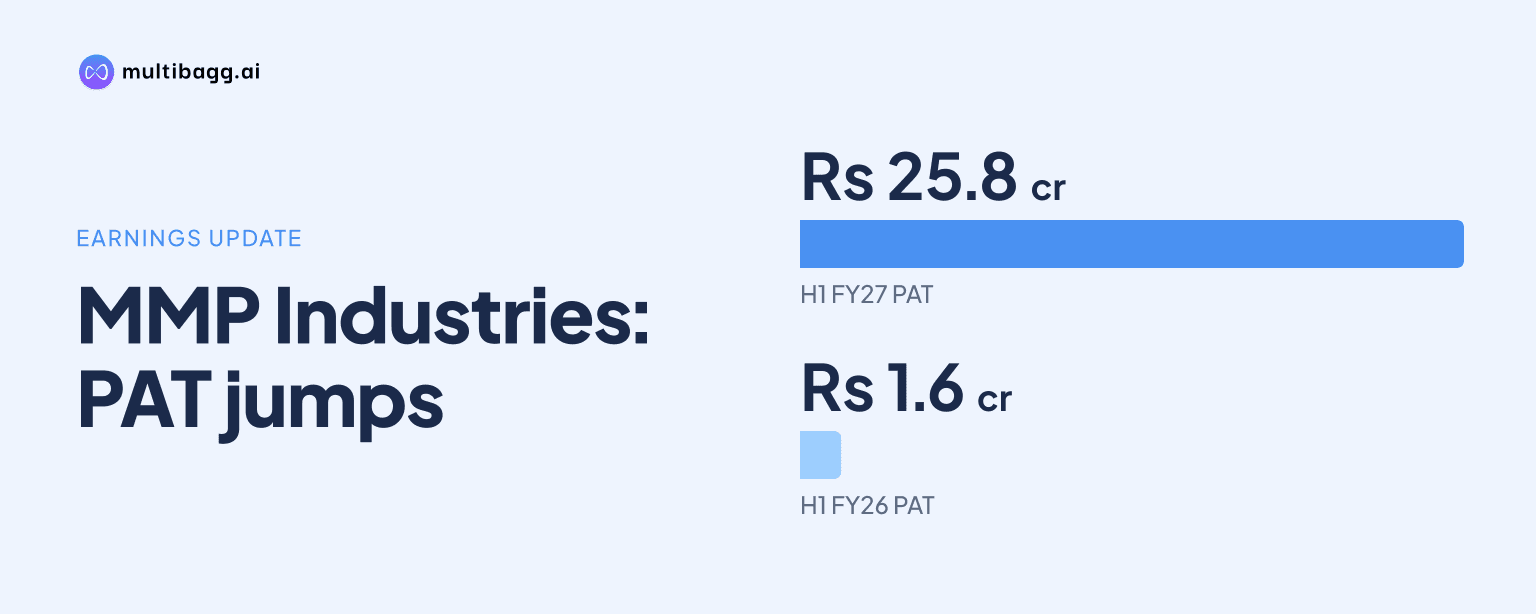
MMP Industries Limited reported profit after tax of Rs 25.8 crore in H1FY27, up 1,516% from a fire-affected Rs 1.6 crore in H1FY26, while Q2FY27 EBITDA margin eased sequentially to 7.6% from 9.0% in Q1FY27. The half-year income increase was 31%, taking total income to Rs 485.7 crore.
Know MMP Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did MMP Industries H1FY27 profit rise 1,516%?
MMP Industries' H1FY27 PAT rose to Rs 25.8 crore from Rs 1.6 crore because the prior-year period included a Rs 17.3 crore exceptional charge relating to the Q1FY26 fire incident, while operating earnings also increased. Total income rose 31% to Rs 485.7 crore, profit before tax rose 82.3% to Rs 27.3 crore, and PAT margin increased to 5.3% from 0.4%.
The increase was not limited to the lower comparison base. Gross profit rose by Rs 23.1 crore to Rs 97.2 crore and earnings before interest, tax, depreciation and amortisation (EBITDA) increased by Rs 13.8 crore to Rs 40.3 crore. EBITDA margin rose 117 basis points, with one basis point equal to one-hundredth of a percentage point, while earnings before interest and tax margin increased to 7.0% from 5.6%.
How did MMP Industries Q2FY27 margins change from Q1FY27?
MMP Industries recorded higher Q2FY27 income but lower sequential margins, as total income rose 9% to Rs 252.9 crore while gross profit declined 1% to Rs 48.3 crore from Rs 48.9 crore in Q1FY27. Gross margin consequently fell 193 basis points to 19.1% from 21.0%, despite the increase in quarterly income.
EBITDA fell 8% sequentially to Rs 19.3 crore from Rs 21.0 crore, taking EBITDA margin down 136 basis points to 7.6%. PAT declined 12% to Rs 12.1 crore from Rs 13.7 crore and PAT margin declined to 4.8% from 5.9%. Management attributed the sequential moderation primarily to inventory valuation losses, elevated aluminium prices and higher consumable costs; finance cost was unchanged at Rs 3.4 crore in both quarters.
The quarter remained ahead of Q2FY26 on a year-on-year basis. Q2FY27 total income was 34% above Rs 188.2 crore, EBITDA was 44% above Rs 13.4 crore and PAT was 73% above Rs 7.0 crore. EBITDA margin was 7.6%, compared with 7.1% a year earlier, and PAT margin was 4.8%, compared with 3.7%.
Got a follow-up? Ask IRIS
Which MMP Industries businesses drove H1FY27 revenue?
MMP Industries' Aluminium Powders segment was the largest contributor, generating Rs 315 crore in H1FY27, or 65% of the Rs 486 crore revenue mix disclosed by the company. Segment revenue rose 41% from Rs 224 crore in H1FY26, supported by demand, exports and improved plant utilisation. Management said export orders were executed at an unprecedented scale during Q2FY27.
Aluminium Foils generated Rs 135 crore, up 38% from Rs 98 crore and representing 28% of the H1FY27 mix. In Q2FY27, Foils revenue grew 47% year on year to Rs 75 crore and Powders revenue rose 37% to Rs 161 crore. Management said Foils maintained positive EBITDA margins across bare and printed products despite pricing pressure, while lidding-foil samples were under evaluation with customers including Dinshaw's and Amul.
Aluminium Conductors / Cables moved in the opposite direction, with H1FY27 revenue declining 32% to Rs 33 crore and Q2FY27 revenue falling 16% to Rs 16 crore. Management attributed the Q2 decline to a monsoon-related slowdown in project execution. It expects H2FY27 segment revenue to grow 40% to 50% over H1FY27, while low-tension cable sales are expected to gain momentum from Q4FY27, subject to utility approvals.
What could affect MMP Industries H2FY27 performance?
MMP Industries is targeting Q4FY27 commercial production at its 18,000 metric-tonnes-per-annum aluminium wire-rod facility. Management expects this backward-integration project to improve supply-chain efficiency and margins in Conductors and Cables. A separate 6,000 metric-tonnes-per-annum low-tension power-cable expansion is progressing, with trials targeted for Q4FY28.
Product commercialisation and approvals are further variables for the second half. The lidding-foil line is ready and initial trials have been completed, while security printing foil and lidding foil launches are targeted in Q3FY27. MMP Industries has received Bureau of Indian Standards certification for low-tension cables, but utility approvals remain in process; its polymer-insulator range has been developed up to 765 kilovolts.
A roughly 7-megawatt captive solar park is ready at site but awaits regulatory approval for commissioning. Management expects it to reduce power costs and support margins once operational. For Aluminium Powders, management expects higher exports, value-added products and economies of scale to support H2FY27 margins after the segment generated Rs 315 crore in H1FY27 revenue.
Conclusion
MMP Industries combined 31% H1FY27 income growth with a 52% increase in EBITDA and a 1,516% rise in PAT, although the PAT comparison was materially affected by the Rs 17.3 crore fire-related exceptional charge in H1FY26. Aluminium Powders and Foils together increased revenue by Rs 128 crore year on year, while Conductors and Cables declined by Rs 15 crore amid slower project execution.
The next disclosed milestones are Q3FY27 launches of security printing foil and lidding foil, Q4FY27 commercial production at the 18,000 metric-tonnes-per-annum wire-rod facility, and expected momentum in low-tension cable sales subject to utility approvals. The commissioning status of the roughly 7-megawatt solar park and management's stated target for 40% to 50% H2FY27 Conductors and Cables revenue growth over H1FY27 are also relevant developments to watch.