










MMP powder exports doubled in H1 FY27 as markets widened
Key highlights
- MMP reported around Rs 13 crore of aluminium-powder exports in Q2 FY27, compared with Rs 4.48 crore in Q2 FY26.
- MMP said H1 FY27 exports doubled year on year; disclosed Q1 FY27 and Q2 FY27 exports total Rs 18.53 crore.
- Powder volume rose 2% year on year and 8% quarter on quarter in the reported quarter.
- MMP reported an approximately Rs 2.5 crore inventory-valuation loss in Q2 FY27.
powered by IRIS
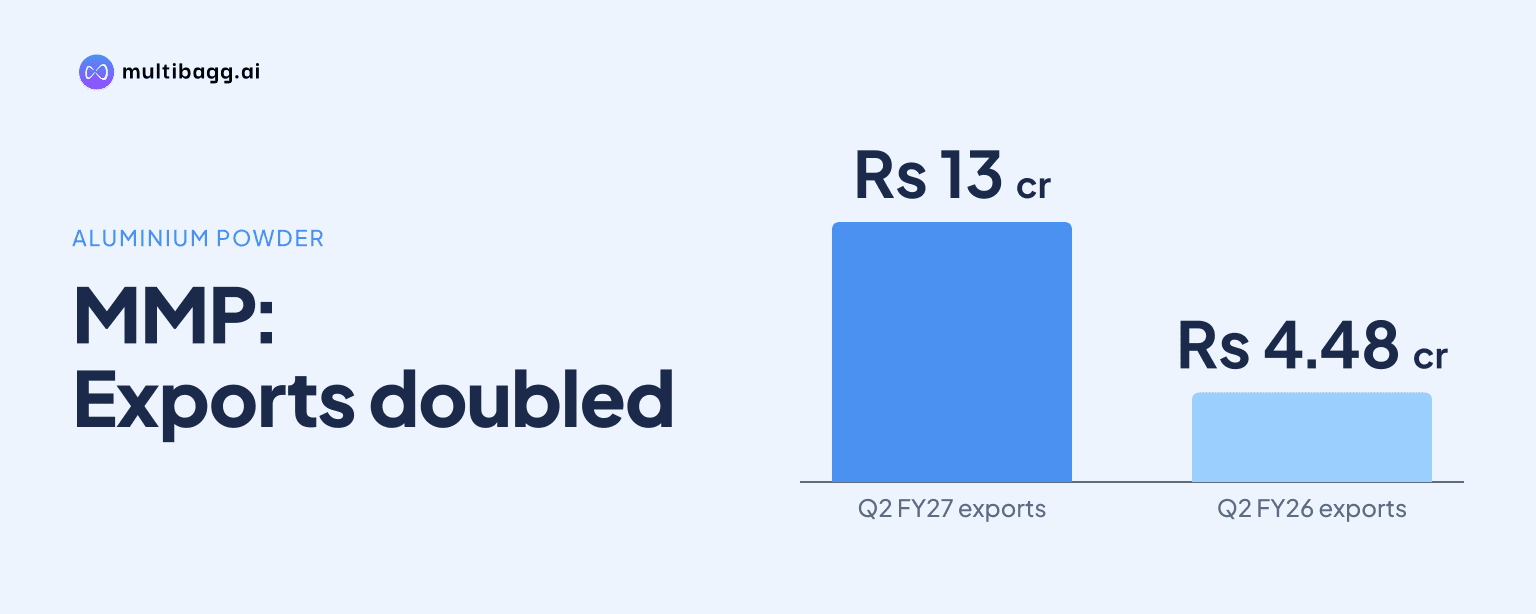
MMP’s powder exports doubled in H1 FY27, with around Rs 13 crore reported in Q2 FY27 versus Rs 4.48 crore in Q2 FY26, as management cited demand spanning Europe, Africa, South America, the Middle East and Southeast Asia during the quarter. Management did not disclose the exact H1 export base.
Know MMP Industries inside out
Results, valuation, peers and who's buying, in one view.
How fast did MMP’s aluminium-powder exports grow?
MMP’s aluminium-powder export sales reached around Rs 13 crore in Q2 FY27, compared with Rs 4.48 crore in Q2 FY26 and Rs 5.53 crore in Q1 FY27. The Q2 FY27 figure was nearly three times the year-earlier quarterly amount and more than twice the Q1 FY27 level disclosed on the call.
Management said exports in H1 FY27 had “just doubled” from the corresponding half year. The call did not provide the precise H1 FY26 export value, but the disclosed Q1 FY27 and Q2 FY27 figures add up to Rs 18.53 crore. That calculation provides the reported first-half run rate, rather than an independently disclosed half-year export total.
The export advance was substantially larger than MMP’s reported aggregate powder-volume movement. Management said powder volume grew 2% year on year and 8% quarter on quarter, while the Q2 FY27 export value rose from Rs 4.48 crore a year earlier. MMP did not disclose powder export tonnage, export pricing or export-specific profitability.
Which markets are driving MMP’s powder exports?
MMP said demand in Q2 FY27 was coming from Europe, Africa, South America, the Middle East and Southeast Asia, rather than being concentrated in one geography. Management also cited enquiries from Europe and South Africa when discussing visibility for powder exports, with South Africa forming part of the broader African demand description.
Mayank Bhandari said Europe was showing good signs and that MMP had added a few customers there. He also said orders deferred by AVL in Europe were expected to proceed immediately, although the call did not disclose the value, timing, powder grade or revenue contribution of those orders.
Management expects the geographically distributed demand to sustain for at least the next one to two years. That is management’s outlook, not a contracted export forecast: MMP gave no customer-wise order book, regional revenue split or export-revenue target for FY27.
Can MMP increase powder exports without new capacity?
MMP is not immediately planning capital expenditure in its powder division, according to management. Its stated near-term strategy is to increase exports from the current powder business, with Mayank Bhandari saying export realisations and margins are better than alternatives, without quantifying either the price or margin difference.
An analyst described the powder operation as having reached optimum utilisation, while management focused on export substitution rather than announcing a new powder-capacity project. MMP also said it had no current plan to enter aluminium additive manufacturing or other niche powder areas, keeping its stated priority on existing export markets.
Management identified prospective Middle East reconstruction as a potentially large opportunity, especially for AAC powders. AAC, or autoclaved aerated concrete, was described by MMP as its main domestic segment, where customisation and a wide range of grades create an entry barrier. Management did not present reconstruction-related demand as a booked order or specify a start date.
Got a follow-up? Ask IRIS
What do MMP’s volume and inventory figures show?
MMP reported 2% year-on-year powder-volume growth in the quarter, compared with 14% growth in foil volume and a 33% decline in conductor volume. On a quarter-on-quarter basis, powder volume rose 8%, foil volume increased 30%, and conductor volume fell 10%, making foil the fastest-growing segment by the disclosed sequential volume measure.
The differing segment movements show that the Rs 13 crore Q2 FY27 export result occurred alongside modest aggregate year-on-year powder-volume growth. The call does not establish how much of the export increase came from product mix, higher realisations, customer additions, domestic-to-export allocation or changes in aluminium prices.
MMP reported an approximately Rs 2.5 crore inventory-valuation loss in Q2 FY27. Management said its full-year operating guidance for powder and foil remained in line with earlier indications, subject to inventory-related gains or losses. It did not disclose actual H1 FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, per tonne for either segment.
What profitability and demand indicators should be followed next?
Management reaffirmed FY27 EBITDA guidance of Rs 37,000 to Rs 42,000 per tonne for powder and Rs 12,000 to Rs 15,000 per tonne for foil. It said variations from these ranges could arise from inventory gains or losses, including the approximately Rs 2.5 crore Q2 FY27 valuation loss, rather than a change in underlying guidance.
The next reported export figures will show whether the Rs 13 crore Q2 FY27 level is followed by repeat business from the five regions management identified. Europe is a near-term item because management referred to newly added customers and deferred AVL orders, while Middle East reconstruction remains a longer-dated opportunity without a disclosed schedule.
MMP said it expects to keep improving exports each month while retaining no immediate plan for powder capacity expansion. As a result, future disclosures on powder utilisation, export share, customer conversion, export realisations and AAC demand would help clarify whether further sales growth is coming from mix changes or a higher level of overall output.
Conclusion
MMP’s around Rs 13 crore of Q2 FY27 powder exports, compared with Rs 4.48 crore in Q2 FY26, supports management’s statement that H1 FY27 exports doubled year on year. Demand was described as spread across Europe, Africa, South America, the Middle East and Southeast Asia, while total powder volume increased 2% year on year.
The next points to watch are the conversion of European enquiries and deferred AVL orders, repeat demand across the disclosed regions, and any evidence that prospective Middle East reconstruction is becoming booked AAC-powder demand. Management has no immediate powder-capacity plan and retained FY27 powder EBITDA guidance of Rs 37,000 to Rs 42,000 per tonne, subject to inventory effects.