










Monte Carlo cotton reaches 63% of H1 gross product sales
Key highlights
- Cotton accounted for approximately 63% of Monte Carlo’s H1 FY '27 gross product sales.
- Monte Carlo’s cotton gross sales increased to Rs 390 crore in H1 FY '27 from Rs 326 crore in H1 FY '26.
- Home-textile gross sales rose to Rs 91.6 crore, while footwear gross sales increased to Rs 9.3 crore in H1 FY '27.
- Monte Carlo maintained FY '27 guidance for low double-digit revenue growth and 40 to 45 new EBOs.
powered by IRIS
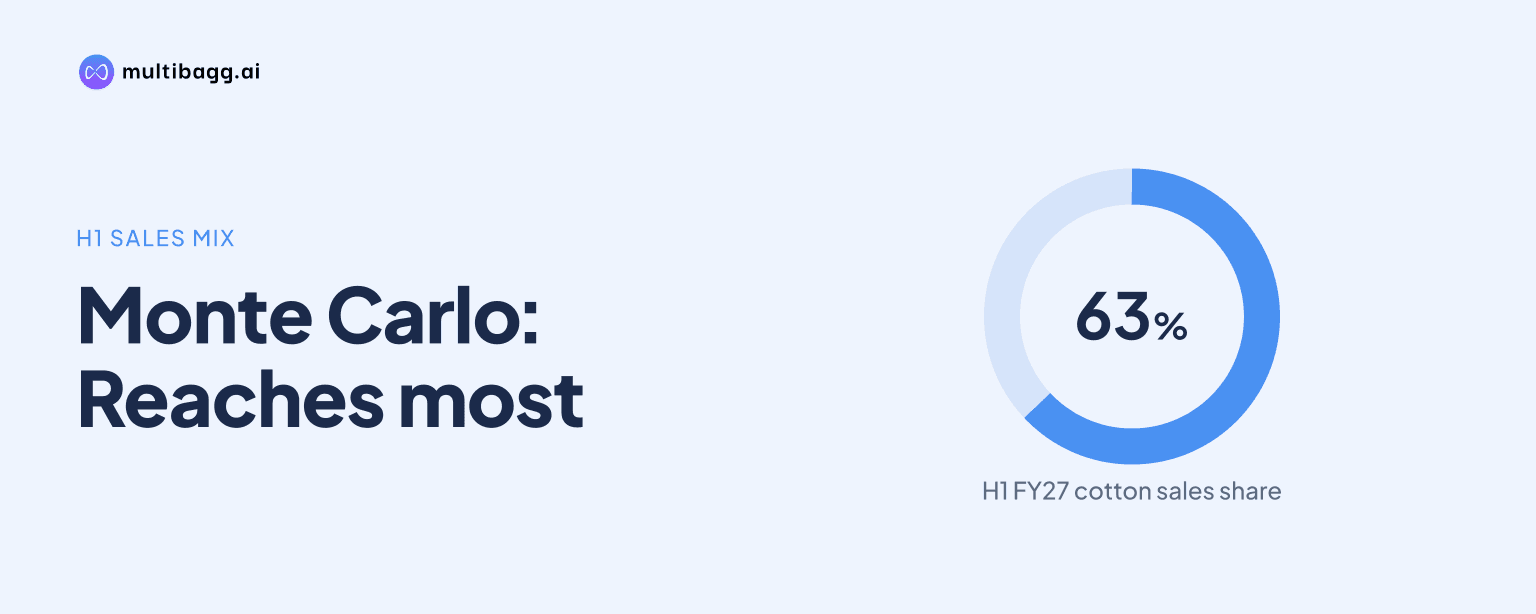
Monte Carlo Fashions Limited’s cotton category accounted for approximately 63% of H1 FY '27 gross product sales, making it its largest reported product line. Cotton gross sales reached Rs 390 crore in the half year, while the company said its portfolio also includes established kids wear and home-textile businesses.
Know Monte Carlo Fashions inside out
Results, valuation, peers and who's buying, in one view.
Why is cotton now Monte Carlo’s largest category?
Cotton is Monte Carlo’s largest reported product category because it contributed approximately 63% of H1 FY '27 gross product sales and has held that position since FY '22. Management said the category is central to making the brand relevant across a larger part of the year, rather than changing Monte Carlo’s winterwear franchise.
The 63% measure is based on gross product sales, not reported net revenue, because management said gross category sales are before returns and other adjustments. Winter remains material to annual performance through jackets within cotton apparel and blankets and quilts within home textiles. Monte Carlo said Q3 contributed about 48% of FY '26 revenue, showing that a larger cotton base has not removed the seasonal importance of the winter selling period.
Which Monte Carlo categories grew in H1 FY '27?
Monte Carlo reported H1 gross-sales growth in cotton, home textiles, kids wear and footwear, while woolen gross sales declined. The comparison below uses gross category sales before returns and other adjustments, rather than Monte Carlo’s reported revenue from operations.
Cotton added Rs 64 crore of gross sales from H1 FY '26, the largest increase among the disclosed categories. Home textiles added Rs 8.6 crore, kids wear Rs 4.5 crore and footwear Rs 4.4 crore, while woolen fell by about Rs 12 crore. The half-year expansion therefore came from non-woolen categories, even as management continued to identify winter as important to the full-year outcome.
At the company level, H1 FY '27 revenue from operations rose 6.25% to Rs 411 crore from Rs 387 crore in H1 FY '26. That reported revenue growth was lower than the gross-sales gains in several categories because management said dispatches must be assessed alongside returns, rebates and provisions. H1 returns were 30.70%, compared with 29.47% in H1 FY '26.
Got a follow-up? Ask IRIS
How is Monte Carlo using distribution to broaden its portfolio?
Monte Carlo is broadening its portfolio through selective retail, regional and channel expansion rather than outlet growth alone. As of September 26, it had 506 exclusive brand outlets, or EBOs, compared with 497 a year earlier, and 632 shop-in-shop locations, up from 578. Management said it evaluates expansion using store profitability and return potential, not outlet count alone.
The channel mix changed in other directions. Multi-brand outlets, or MBOs, declined to 1,413 from 1,615, while National Chain Stores fell to 846 from 891. Management identified digital and modern retail as channels for further development, alongside newer businesses including footwear and newer brands that remain relatively small. Rock.it serves athleisure, while Cloak & Decker serves the economy segment, according to management’s explanation for keeping those brands separate from the premium Monte Carlo brand.
North remains Monte Carlo’s largest market, while West and South together represented approximately 9.7% of gross sales. Management described those regions as medium-term expansion opportunities, although it cautioned that online and some other sales are not attributed to individual states in the available geographic classification. The disclosed regional mix therefore does not fully capture all sales by customer location.
What does Monte Carlo’s portfolio plan mean for FY '27?
Monte Carlo maintained guidance for low double-digit revenue growth in FY '27, 20% home-textile growth and 40 to 45 new EBOs, including expansion in West and South. Management’s stated priorities for the remainder of the year are consumer sell-through, productive retail expansion and cash conversion, with the festive and winter selling season the immediate execution focus.
The first half is a period of production, inventory building and dispatches before winter demand, management said. It added that a later festive season shifted meaningful consumer demand and winter sell-through into Q3. The Q2 return ratio improved to 16.17% from 23.18% a year earlier, but management expects the timing effect from retailer returns processed early in Q1 to reverse over the following two quarters.
Portfolio growth is occurring alongside pressure on first-half profitability. Operating earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 15.42 crore in H1 FY '27, with a 3.7% margin, while loss after tax was Rs 22.25 crore. Management attributed lower profitability to higher material costs, lower other income and higher employee costs; it said an 8% to 9% winterwear price increase had been taken for Q3 to address raw-material cost increases.
Conclusion
Monte Carlo’s H1 FY '27 figures show that cotton, at approximately 63% of gross product sales and Rs 390 crore of gross sales, has become its principal reported category. Growth in home textiles, kids wear and footwear alongside cotton provides evidence of a broader revenue base, but woolen’s decline and the continuing importance of the Q3 winter cycle show that seasonality remains consequential.
The next test is the festive and winter selling season in Q3, which management said is particularly important after late festive timing shifted demand from the first half. Readers can watch whether Monte Carlo delivers its low double-digit revenue-growth guidance, 20% home-textile target and planned addition of 40 to 45 EBOs, while converting inventory into collections and managing returns.