










Nupur Recyclers H1 EBITDA exceeds FY26 full-year result
Key highlights
- NR reported H1 FY27 EBITDA of Rs 28.59 crore, above FY26 EBITDA of Rs 27.75 crore.
- NR’s H1 FY27 total income rose 90.3% year on year to Rs 199.24 crore.
- NR’s H1 FY27 EBITDA margin increased to 15.0% from 12.4% in H1 FY26.
- NR targets Q4 FY27 commissioning of a 6,000-metric-ton annual battery-recycling facility.
powered by IRIS
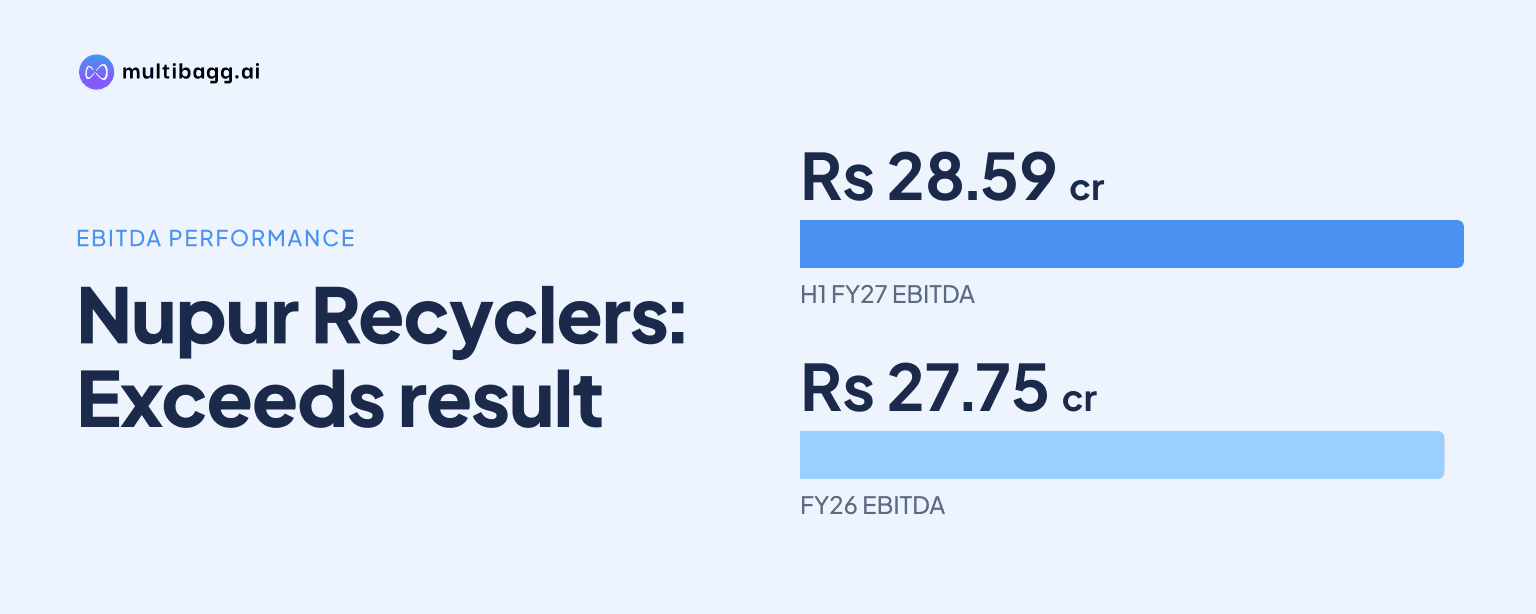
Nupur Recyclers reported H1 FY27 earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 28.59 crore, surpassing its FY26 full-year EBITDA of Rs 27.75 crore by Rs 84 lakh. The six-month result followed a 90.3% year-on-year increase in total income to Rs 199.24 crore, while H1 EBITDA margin rose to 15.0% from 12.4%.
Know Nupur Recyclers inside out
Results, valuation, peers and who's buying, in one view.
What drove NR’s H1 FY27 EBITDA above its FY26 result?
NR’s H1 FY27 EBITDA exceeded the FY26 full-year result because total income grew faster than the comparable prior-year cost base. Total income rose from Rs 104.71 crore in H1 FY26 to Rs 199.24 crore in H1 FY27, while total expenses increased from Rs 93.86 crore to Rs 177.74 crore. This produced EBITDA of Rs 28.59 crore, up 130.3% from Rs 12.41 crore a year earlier.
Revenue from operations was the principal component of that increase. It grew 91.4% year on year to Rs 190.91 crore in H1 FY27 from Rs 99.74 crore in H1 FY26. Other income also increased to Rs 8.33 crore from Rs 4.97 crore. EBITDA therefore rose by Rs 16.18 crore over the period, whereas total income increased by Rs 94.53 crore.
The comparison with the full year is notable because FY26 EBITDA of Rs 27.75 crore was generated on total income of Rs 226.61 crore. H1 FY27 total income of Rs 199.24 crore was Rs 27.37 crore below that full-year figure, yet EBITDA was Rs 84 lakh higher. NR’s H1 EBITDA margin of 15.0% was also 2.1 percentage points above FY26’s 12.9%.
How did NR’s second-quarter performance compare with the first quarter?
NR’s Q2 FY27 earnings increased in absolute terms from Q1 FY27, but EBITDA and profit after tax margins declined sequentially. Q2 EBITDA reached Rs 15.73 crore, 22.4% above Rs 12.86 crore in Q1. Total income increased 40.0% quarter on quarter to Rs 116.21 crore, while total expenses rose 42.6% to Rs 104.49 crore.
The faster sequential increase in expenses reduced the EBITDA margin to 14.1% in Q2 from 16.2% in Q1, a decline of 210 basis points. A basis point is one-hundredth of a percentage point. Q2 EBITDA margin nevertheless remained 110 basis points above the 13.0% reported in Q2 FY26, when EBITDA was Rs 6.33 crore.
Profit after tax (PAT) rose 19.1% quarter on quarter to Rs 8.80 crore in Q2 from Rs 7.39 crore in Q1. However, PAT margin declined to 7.9% from 9.3%, a 140-basis-point movement. Against Q2 FY26, PAT more than doubled from Rs 4.33 crore, but the Q2 FY27 PAT margin was 100 basis points lower than the prior-year quarter’s 8.9%.
Got a follow-up? Ask IRIS
How does H1 FY27 compare with NR’s earlier annual financial record?
NR’s H1 FY27 result surpassed FY26 EBITDA but had not exceeded FY26 PAT by the end of the half year. H1 PAT was Rs 16.18 crore, compared with Rs 16.48 crore for FY26, leaving a Rs 30 lakh difference. H1 PAT was still 93.2% higher than Rs 8.38 crore in H1 FY26, and its margin improved by 10 basis points to 8.5%.
Over the three completed financial years, NR’s revenue and EBITDA record has varied. Total income declined from Rs 246.19 crore in FY24 to Rs 167.69 crore in FY25, then increased to Rs 226.61 crore in FY26. EBITDA moved from Rs 13.14 crore in FY24 to Rs 25.00 crore in FY25 and Rs 27.75 crore in FY26; the corresponding EBITDA margins were 5.47%, 15.79% and 12.85%.
H1 FY27 also showed a larger balance sheet than FY26. Total assets rose to Rs 247.30 crore from Rs 198.01 crore, while total equity increased to Rs 163.20 crore from Rs 147.02 crore. Debt-to-equity increased to 0.37 times from 0.25 times, while return on equity was 9.9% and return on capital employed was 12.3%, compared with FY26 levels of 11.2% and 13.9%, respectively.
What is NR planning after H1 FY27?
NR plans to commission a battery-recycling facility at Sampla, Haryana, in Q4 FY27. The proposed facility has installed capacity of about 6,000 metric tons per year and requires estimated capital investment of Rs 50 crore to Rs 70 crore. Management identifies internal accruals and no external debt as the planned funding source.
Management’s stated financial case for the facility is annual revenue potential of about Rs 100 crore to Rs 125 crore at full operating capacity and a targeted EBITDA margin of about 25% to 30%. These are management targets for the planned operation, not reported H1 FY27 results. The site also has about 10 additional acres secured beyond the land associated with the initial 6,000-metric-ton capacity.
The process described by NR takes battery material through collection, dismantling, shredding and separation into black mass, followed by hydrometallurgy and recovered materials. Management says hydrometallurgy can recover lithium, iron phosphate and graphite using controlled chemical reactions. The presentation lists lithium as 4%, iron phosphate as 25% and graphite as 22% of the stated material composition.
Conclusion
NR’s H1 FY27 performance shows that EBITDA of Rs 28.59 crore moved above the Rs 27.75 crore reported for all of FY26, supported by 90.3% growth in total income and a 250-basis-point year-on-year increase in H1 EBITDA margin. The sequential picture was more mixed: Q2 EBITDA increased to Rs 15.73 crore, while its margin declined from 16.2% in Q1 to 14.1%.
The next disclosed event to watch is the Q4 FY27 commissioning target for NR’s Sampla battery-recycling facility. Management’s plan calls for about 6,000 metric tons of annual installed capacity, Rs 50 crore to Rs 70 crore of investment from internal accruals, and a targeted EBITDA margin of about 25% to 30% at full operating capacity.