










PCCPL Targets Rs 120-150 Crore New-Product Revenue in 2-3 Years
Key highlights
- PCCPL expects Rs 120-150 crore of incremental revenue from new product lines over the next 2-3 years.
- PCCPL has earmarked about Rs 100 crore for two multi-purpose plants.
- PCCPL has more than 25 products at R&D and pilot stages and plans to double R&D expenditure over two years.
- PCCPL signed 3 exclusive global-customer MoUs, with trial lots supplied for 2 products.
powered by IRIS
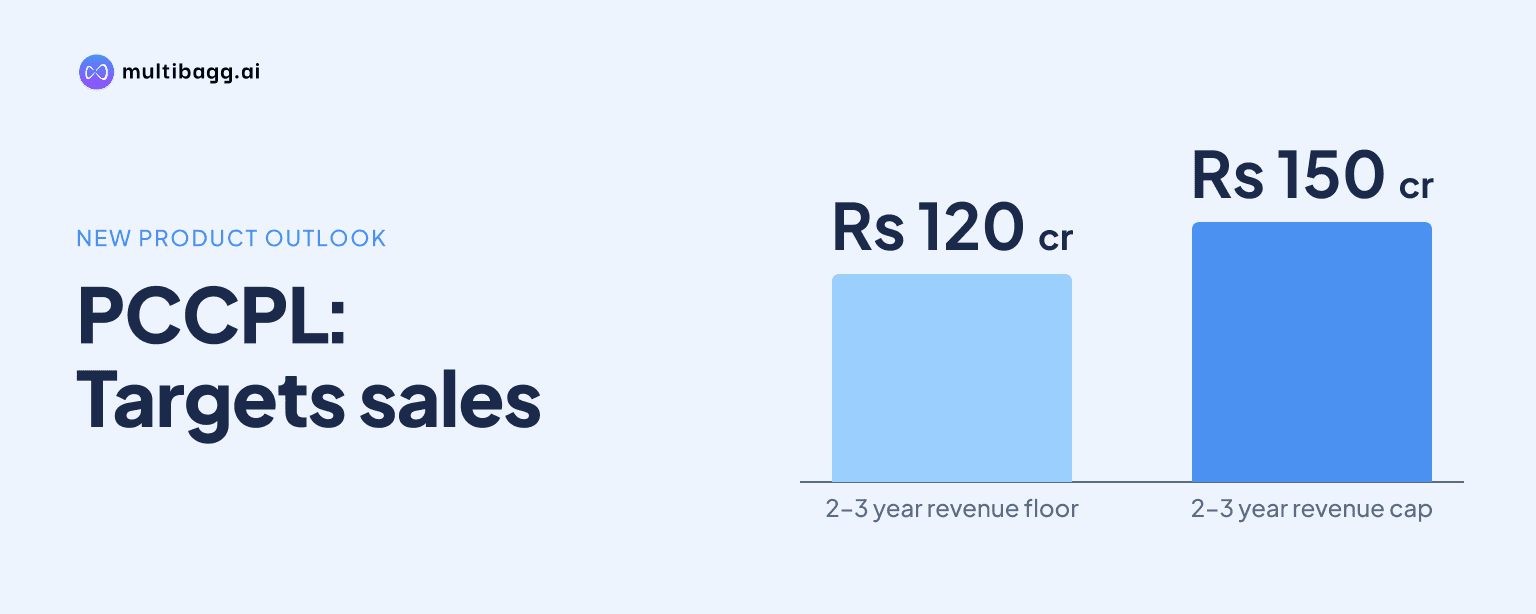
Punjab Chemicals and Crop Protection Limited expects Rs 120-150 crore of incremental revenue from new product lines over the next 2-3 years, supported by about Rs 100 crore earmarked for two multi-purpose plants. PCCPL also plans to double research and development expenditure over two years and has more than 25 products at research and pilot stages.
Know Punjab Chemicals & Crop Protection inside out
Results, valuation, peers and who's buying, in one view.
What is PCCPL investing Rs 100 crore in?
PCCPL has earmarked about Rs 100 crore of capital expenditure for two multi-purpose plants to cater to growth over the next 2-3 years. The planned facilities are intended to serve domestic and export markets, with the company describing the manufacturing expansion as focused on new business markets and export growth.
The investment supports PCCPL's stated move towards higher-value intermediates, aimed at capturing upstream value and supporting global clients. The presentation does not disclose plant locations, capacities, commissioning dates or the allocation of the approximately Rs 100 crore between the two facilities.
PCCPL is also actively scouting for a new site to support growing operations and its product range. The presentation identifies the prospective site as a future production location but provides no location, acquisition timetable or investment estimate.
How will PCCPL generate new-product revenue?
PCCPL expects Rs 120-150 crore of incremental revenue from new product lines over the next 2-3 years. The target is linked to a pipeline of more than 25 products at research and development (R&D) and pilot stages, rather than to a disclosed product-level revenue schedule.
The pipeline includes performance chemicals, fuel additives and intermediates, alongside PCCPL's agrochemical activities. The company also cites backward integration, which involves bringing earlier production steps into its value chain, as part of its approach to long-term sustainability and profit-margin improvement.
Additional new-molecule commercialisation trials are planned in the second half of FY27. PCCPL is revamping its pilot plant to handle product commercialisation and trials for new chemistries, although it has not specified the number of products due for trials in H2 FY27 or the revenue contribution expected from that phase.
What customer progress has PCCPL reported?
PCCPL has signed three exclusive memorandums of understanding (MoUs) with global customers for high-value agrochemicals and intermediates. It has supplied lots for market trials for two of the three MoU products, indicating that those two products have advanced to customer evaluation.
The company is expanding both its contract development and manufacturing organisation (CDMO) portfolio and direct-sales range. PCCPL identifies in-house R&D, faster turnaround, quality delivery, safety, reliability, intellectual-property protection and transparency as CDMO capabilities, but it does not disclose order values or revenue tied to the three MoUs.
PCCPL says its R&D work across diverse chemistries adds six to eight new products each year. That annual product-addition rate sits alongside the larger pipeline of more than 25 products at R&D and pilot stages, with no product-by-product approval or launch timetable disclosed.
Got a follow-up? Ask IRIS
How does PCCPL's plan compare with FY26 performance?
PCCPL reported revenue of Rs 1,030 crore in FY26, up Rs 129 crore from Rs 901 crore in FY25. Earnings before interest, tax, depreciation and amortisation (EBITDA) rose to Rs 118 crore from Rs 99 crore, while profit after tax (PAT) increased to Rs 64 crore from Rs 39 crore.
Export revenue accounted for Rs 100 crore of the Rs 129 crore revenue increase in FY26, compared with a Rs 29 crore rise in domestic revenue. Export sales of Rs 448 crore remained below Rs 581 crore in FY23, while domestic revenue of Rs 582 crore was the highest domestic figure reported for FY22 to FY26.
EBITDA margin improved to 11.5% in FY26 from 11.0% in FY25, and PAT margin increased to 6.2% from 4.3%. Both remained below the FY22 levels of 15.0% and 8.9%, respectively, providing context for PCCPL's focus on scale, higher-value product mix, efficiency gains and deeper integration.
How will PCCPL expand R&D and integration?
PCCPL plans to double R&D expenditure over the next two years through capability and infrastructure development. Its stated uses include catalogue products, technology development, backward integration and new chemistries, while it aims to increase high-value intermediates alongside its CDMO business.
The intended portfolio mix includes a greater share of specialty chemicals and intermediates and a balance between domestic and export markets. PCCPL has not disclosed its present R&D expenditure, the absolute budget after the planned doubling, or target revenue shares for catalogue products, intermediates and CDMO activities.
PCCPL also cites regular investment in technology and asset renewal to maintain existing-product competitiveness. Its debt declined to Rs 142 crore in FY26 from Rs 157 crore in FY25, while equity rose to Rs 424 crore from Rs 365 crore and debt-to-equity fell to 0.3 times from 0.4 times.
Conclusion
PCCPL's plan combines about Rs 100 crore for two multi-purpose plants, a doubling of R&D expenditure over two years and a pipeline of more than 25 R&D and pilot-stage products. Management's Rs 120-150 crore new-product revenue expectation over 2-3 years depends on commercialising that pipeline across agrochemicals, intermediates, performance chemicals and fuel additives.
The next disclosed milestone is additional new-molecule commercialisation trials in H2 FY27. Progress in market trials for the two MoU products already supplied, advancement of the third MoU product, further details on the new-site search and information on plant commissioning would clarify execution of the stated plan.