










PCCPL receivables more than doubled to Rs 453.9 crore
Key highlights
- PCCPL trade receivables rose to Rs 453.9 crore at Sep'26 from Rs 203.5 crore at Mar'26.
- PCCPL total borrowings reached Rs 284.5 crore at Sep'26, compared with Rs 142.4 crore at Mar'26.
- PCCPL inventories fell by Rs 32.6 crore to Rs 213.2 crore between Mar'26 and Sep'26.
- PCCPL H1 FY27 revenue rose 17.3% to Rs 673.9 crore, while PAT declined 9.3% to Rs 35.5 crore.
powered by IRIS
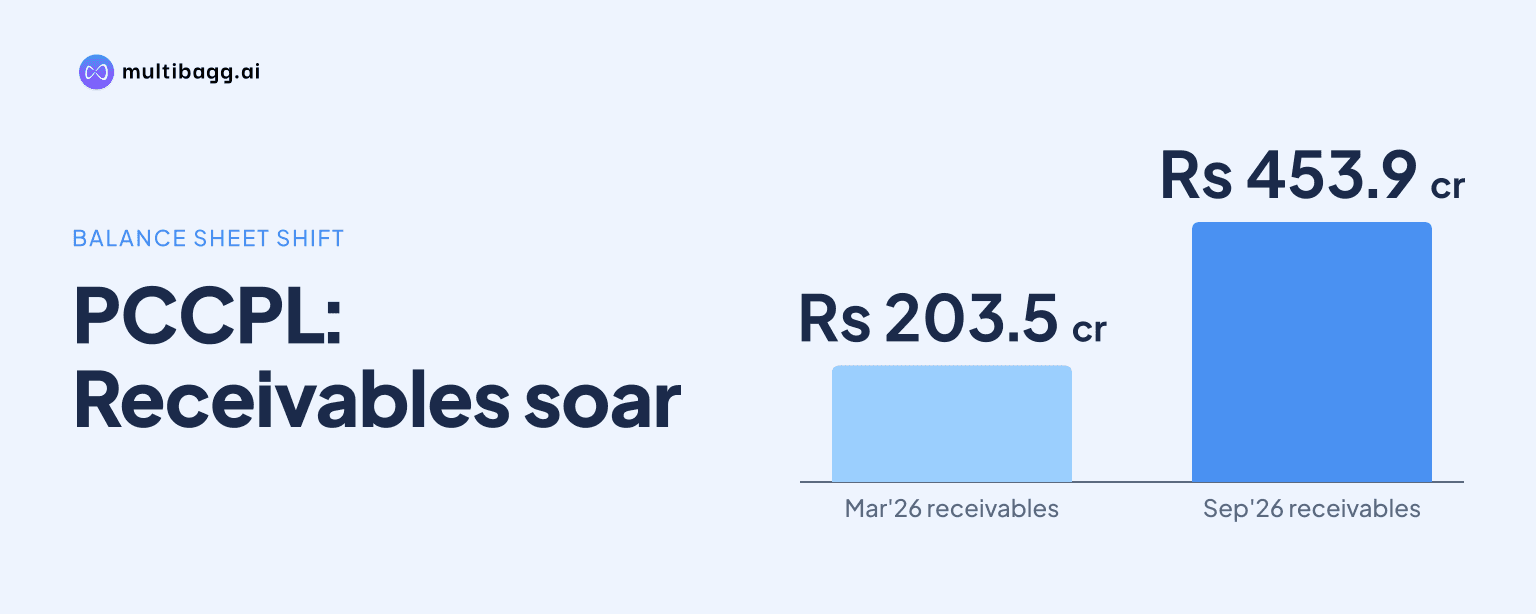
At Sep'26, Punjab Chemicals and Crop Protection Limited (PCCPL) reported trade receivables of Rs 453.9 crore, more than double Rs 203.5 crore at Mar'26, while total borrowings rose to Rs 284.5 crore from Rs 142.4 crore. The balance-sheet shift occurred as inventories declined by Rs 32.6 crore to Rs 213.2 crore.
Know Punjab Chemicals & Crop Protection inside out
Results, valuation, peers and who's buying, in one view.
Why did PCCPL's receivables rise by Sep'26?
PCCPL's trade receivables increased by Rs 250.4 crore in the six months to Sep'26, reaching Rs 453.9 crore from Rs 203.5 crore at Mar'26. The September balance was 2.2 times the March amount and was the largest movement among the reported current-asset categories. The presentation does not disclose the customers involved, due dates, ageing of dues or reasons for the increase.
The receivables movement coincided with higher sales in the first half. PCCPL reported consolidated revenue of Rs 673.9 crore for H1 FY27, up 17.3% from Rs 574.7 crore in H1 FY26. Q2 FY27 revenue was Rs 326.7 crore, 28.0% above Rs 255.2 crore in Q2 FY26, although it was 5.9% below Rs 347.2 crore in Q1 FY27.
Receivables rose while inventories moved in the opposite direction. PCCPL's inventory fell to Rs 213.2 crore at Sep'26 from Rs 245.8 crore at Mar'26, a reduction of Rs 32.6 crore. For FY26, the company reported 72 receivable days and 145 inventory days, compared with 95 receivable days and 151 inventory days in FY25; it did not provide equivalent working-capital-day data for Sep'26.
How did PCCPL's borrowings change by Sep'26?
PCCPL's total borrowings rose to Rs 284.5 crore at Sep'26 from Rs 142.4 crore at Mar'26. Current borrowings were Rs 212.8 crore, up from Rs 105.0 crore, while non-current borrowings were Rs 71.7 crore, up from Rs 37.4 crore. The Rs 107.8 crore increase in current borrowings accounted for most of the Rs 142.1 crore rise in total borrowings.
The borrowing increase followed a FY26 in which PCCPL reported debt of Rs 142 crore and equity of Rs 424 crore, producing a debt-to-equity ratio of 0.3 times. The presentation's Sep'26 balance sheet gives the borrowing classification but does not provide a September debt-to-equity ratio, borrowing rates, maturity schedule or stated use of the additional funding.
Finance cost increased alongside the higher reported debt balances. PCCPL's H1 FY27 finance cost was Rs 9.8 crore, compared with Rs 7.7 crore in H1 FY26, while Q2 FY27 finance cost was Rs 5.7 crore against Rs 3.8 crore in Q2 FY26. The presentation does not attribute the finance-cost increase to a particular borrowing facility or interest-rate change.
How did PCCPL's liabilities and funding mix move?
PCCPL's total current liabilities increased to Rs 494.1 crore at Sep'26 from Rs 335.0 crore at Mar'26. Besides current borrowings, dues to creditors other than micro, small and medium enterprises (MSMEs) rose to Rs 189.0 crore from Rs 152.2 crore, and MSME dues increased to Rs 27.9 crore from Rs 20.7 crore.
Non-current liabilities rose to Rs 98.8 crore from Rs 64.5 crore over the same period. This included the Rs 34.3 crore rise in non-current borrowings, while deferred tax liabilities rose to Rs 12.8 crore from Rs 12.0 crore and provisions increased to Rs 5.2 crore from Rs 4.5 crore. Total liabilities consequently reached Rs 592.9 crore, compared with Rs 399.5 crore at Mar'26.
PCCPL's total equity rose to Rs 455.6 crore at Sep'26 from Rs 423.5 crore at Mar'26. Other equity increased to Rs 443.3 crore from Rs 411.2 crore, while equity share capital remained Rs 12.3 crore at both dates. The presentation reports these balance-sheet changes but does not set a target capital structure for FY27.
Got a follow-up? Ask IRIS
What changed in PCCPL's assets by Sep'26?
PCCPL's total assets increased to Rs 1,048.5 crore at Sep'26 from Rs 823.0 crore at Mar'26. Current assets rose by Rs 223.8 crore to Rs 732.7 crore, while non-current assets changed by Rs 1.7 crore to Rs 315.5 crore. The Rs 250.4 crore rise in receivables exceeded the overall current-asset increase because inventories and other current-asset categories declined or had smaller movements.
Cash and bank balances were Rs 9.9 crore at Sep'26, compared with Rs 8.7 crore at Mar'26, while bank balances other than cash and bank balances increased to Rs 8.2 crore from Rs 6.3 crore. Other financial assets rose to Rs 22.8 crore from Rs 12.4 crore. Other current assets declined to Rs 24.4 crore from Rs 32.0 crore.
Property, plant and equipment increased to Rs 267.9 crore at Sep'26 from Rs 255.5 crore at Mar'26. Capital work in progress declined to Rs 15.3 crore from Rs 17.5 crore, and right-of-use assets fell to Rs 13.6 crore from Rs 15.9 crore. These changes left non-current assets broadly stable despite the increase in property, plant and equipment.
How did PCCPL's H1 FY27 earnings compare with H1 FY26?
PCCPL's H1 FY27 earnings before interest, tax, depreciation and amortisation (EBITDA) rose 19.3% year on year to Rs 72.3 crore from Rs 60.6 crore. EBITDA margin increased to 10.7% from 10.5%, even as gross margin declined to 35.4% from 35.9%. Revenue growth of 17.3% therefore accompanied a 0.2 percentage-point increase in the half-year EBITDA margin.
Profit after tax (PAT) fell 9.3% to Rs 35.5 crore in H1 FY27 from Rs 39.2 crore in H1 FY26. PAT margin declined to 5.3% from 6.8%, while depreciation increased to Rs 15.3 crore from Rs 13.2 crore, finance cost rose to Rs 9.8 crore from Rs 7.7 crore, and other income fell to Rs 1.1 crore from Rs 9.8 crore.
In Q2 FY27, PCCPL reported EBITDA of Rs 29.6 crore, up from Rs 26.2 crore a year earlier but below Rs 40.8 crore in Q1 FY27. Q2 PAT was Rs 13.5 crore, compared with Rs 18.5 crore in Q2 FY26 and Rs 22.1 crore in Q1 FY27. Q2 EBITDA margin was 9.0%, versus 10.3% a year earlier and 11.8% in the preceding quarter.
What disclosed plans could affect PCCPL's funding needs?
PCCPL has earmarked about Rs 100 crore of capital expenditure for two multi-purpose plants intended to support domestic and export markets over the next two to three years. Management says it is also actively scouting for a new site to support operations and product range. The presentation does not specify project spending by year or identify the financing source for this capital expenditure.
Management says PCCPL has more than 25 products at research and development and pilot stages, with additional new-product commercialisation trials planned in H2 FY27. It plans to double research and development expenditure over the next two years and expects incremental revenue of Rs 120 crore to Rs 150 crore from new product lines over two to three years. These are management plans and expectations, not reported financial outcomes.
PCCPL has signed three exclusive memorandums of understanding with global customers for high-value agrochemicals and intermediates, according to the presentation. Lots have been supplied for market trials for two of the three products. Management also plans to increase the share of catalogue products and high-value intermediates alongside its contract development and manufacturing organisation business.
Conclusion
PCCPL's Sep'26 balance sheet shows a Rs 250.4 crore increase in trade receivables, exceeding the Rs 223.8 crore growth in current assets, while inventory declined by Rs 32.6 crore. Total borrowings doubled to Rs 284.5 crore, principally through higher current borrowings. Revenue and EBITDA rose in H1 FY27, but PAT declined to Rs 35.5 crore amid higher finance cost and depreciation and lower other income.
The next disclosed items to watch are H2 FY27 new-product commercialisation trials, market trials for two memorandum-of-understanding products, and execution of the planned Rs 100 crore capital expenditure over two to three years. Future disclosures may also show whether receivables reduce, how funding is split between current and non-current borrowings, and progress toward management's expected Rs 120 crore to Rs 150 crore of new-product revenue.