










PCCPL Q2 revenue rose 28% but profit fell 27% as margins shrank
Key highlights
- PCCPL's Q2 FY27 revenue rose 28.0% to Rs 326.7 crore from Rs 255.2 crore.
- PCCPL's Q2 FY27 PAT fell 27.4% to Rs 13.5 crore, while PAT margin reduced to 4.1% from 7.3%.
- PCCPL's domestic Q2 sales rose to Rs 186 crore from Rs 116 crore, while international sales reached Rs 141 crore.
- PCCPL reported Q2 FY27 gross margin of 34.1%, down from 39.5% in Q2 FY26.
powered by IRIS
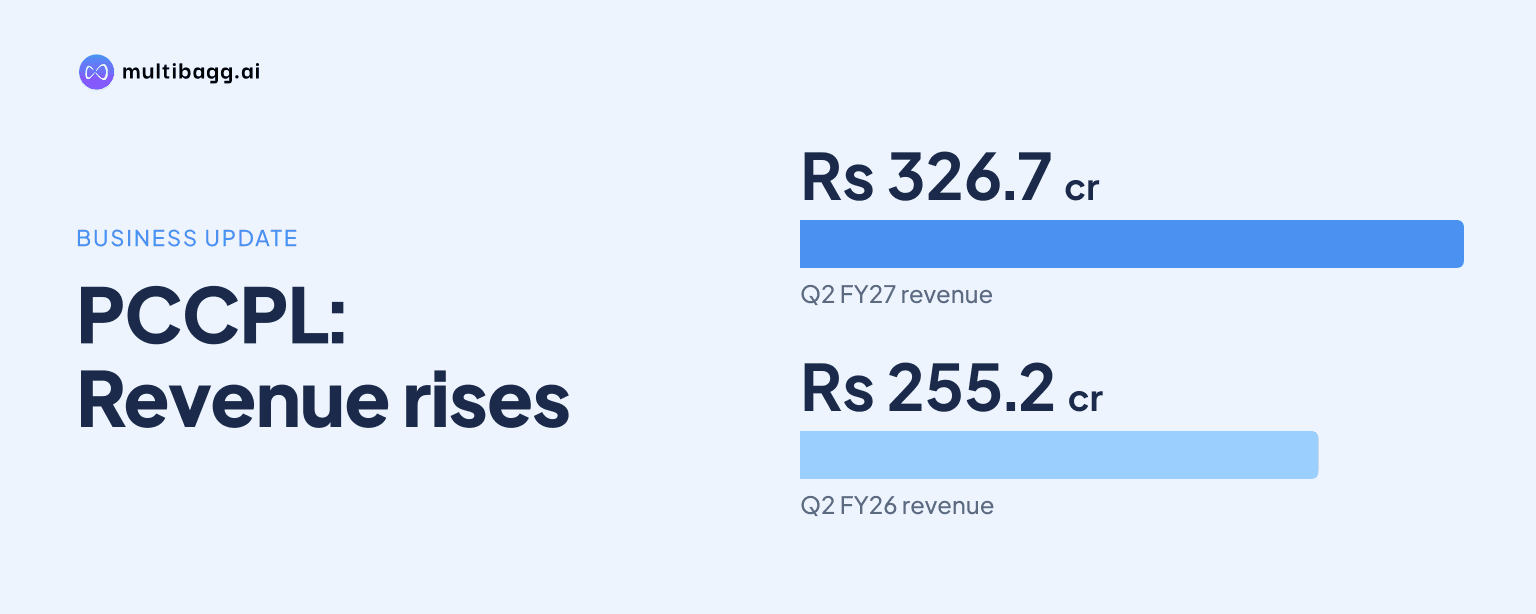
Punjab Chemicals and Crop Protection Ltd (PCCPL) reported consolidated second-quarter FY27 revenue of Rs 326.7 crore, up 28.0% year on year, while profit after tax (PAT) fell 27.4% to Rs 13.5 crore. Gross margin declined to 34.1% from 39.5%, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell to 9.0%.
Know Punjab Chemicals & Crop Protection inside out
Results, valuation, peers and who's buying, in one view.
Why did PCCPL's Q2 FY27 profit decline despite revenue growth?
PCCPL's Q2 FY27 PAT declined because higher revenue was accompanied by lower margins, lower other income, and higher depreciation, finance cost and tax expense. Revenue rose by Rs 71.5 crore from Rs 255.2 crore in Q2 FY26 to Rs 326.7 crore, but gross margin declined by 5.4 percentage points from 39.5% to 34.1%. Gross profit still increased by Rs 10.5 crore to Rs 111.3 crore.
The decline below EBITDA was more pronounced. EBITDA increased 12.6% to Rs 29.6 crore, but EBITDA margin declined from 10.3% to 9.0%. Depreciation increased from Rs 6.6 crore to Rs 8.0 crore, finance cost rose from Rs 3.8 crore to Rs 5.7 crore, and other income fell from Rs 6.1 crore to Rs 2.4 crore. Profit before tax consequently decreased 16.4% to Rs 18.3 crore, while tax expense increased to Rs 4.8 crore from Rs 3.4 crore.
PCCPL's PAT margin was 4.1% in Q2 FY27, compared with 7.3% a year earlier. Earnings per share were Rs 11.0, down from Rs 15.1 in Q2 FY26. The presentation records no exceptional item in either quarter, so the reported PAT movement reflects the operating and below-EBITDA lines in the consolidated profit and loss statement.
Which markets drove PCCPL's Q2 FY27 revenue increase?
PCCPL's domestic business drove the Q2 FY27 revenue increase, with domestic sales rising by Rs 70 crore to Rs 186 crore. International sales were Rs 141 crore, only Rs 2 crore above Rs 139 crore in Q2 FY26. Domestic sales therefore accounted for nearly all of the Rs 72 crore increase in the geographical revenue total, which reached Rs 327 crore in the presentation's rounded figures.
New products were also a disclosed contributor to the quarter's sales mix. PCCPL said new products contributed 19% of Q2 FY27 revenue and grew 295% year on year. The company attributed the overall 28% quarterly revenue growth to improvement in domestic sales, rather than identifying international business as the principal driver.
The revenue expansion came alongside higher cost of goods sold (COGS), which rose to Rs 215.4 crore in Q2 FY27 from Rs 154.4 crore in Q2 FY26. Employee expenses increased by Rs 2.3 crore to Rs 28.0 crore, while other expenses rose by Rs 5.0 crore to Rs 53.8 crore. EBITDA therefore increased by Rs 3.4 crore, less than the Rs 71.5 crore increase in revenue.
How did PCCPL's H1 FY27 results compare with H1 FY26?
PCCPL's first-half, or H1, FY27 revenue and EBITDA increased from H1 FY26, while PAT declined. Revenue rose 17.3% to Rs 673.9 crore from Rs 574.7 crore, and EBITDA increased 19.3% to Rs 72.3 crore from Rs 60.6 crore. EBITDA margin improved slightly to 10.7% from 10.5% over the six-month period, unlike the decline reported in Q2 alone.
PAT for H1 FY27 was Rs 35.5 crore, down 9.3% from Rs 39.2 crore in H1 FY26, and PAT margin decreased from 6.8% to 5.3%. Profit before tax was Rs 48.3 crore, compared with Rs 49.5 crore a year earlier. The half-year statement also shows other income at Rs 1.1 crore, down from Rs 9.8 crore, while finance cost increased to Rs 9.8 crore from Rs 7.7 crore.
Domestic revenue rose by Rs 64 crore to Rs 376 crore in H1 FY27, while international revenue increased by Rs 36 crore to Rs 298 crore. Both geographies contributed to the Rs 99 crore increase in half-year revenue, although domestic sales represented the larger absolute increment. Gross margin was 35.4% in H1 FY27, compared with 35.9% in H1 FY26, a narrower decline than in the Q2 comparison.
Got a follow-up? Ask IRIS
What changed sequentially in PCCPL's Q2 FY27 performance?
PCCPL's Q2 FY27 revenue, EBITDA and PAT were lower than in Q1 FY27. Revenue declined 5.9% sequentially from Rs 347.2 crore in Q1 FY27 to Rs 326.7 crore in Q2 FY27. EBITDA fell 27.5% from Rs 40.8 crore to Rs 29.6 crore, and EBITDA margin reduced from 11.8% to 9.0%.
PAT declined 39.0% sequentially to Rs 13.5 crore from Rs 22.1 crore, with PAT margin falling from 6.4% to 4.1%. Gross margin declined from 36.6% in Q1 FY27 to 34.1% in Q2 FY27. Other income was Rs 2.4 crore in Q2, above Rs 0.7 crore in Q1, but finance cost increased from Rs 4.1 crore to Rs 5.7 crore.
PCCPL's September 2026 balance sheet showed current borrowings of Rs 212.8 crore, compared with Rs 105.0 crore in March 2026, while non-current borrowings were Rs 71.7 crore versus Rs 37.4 crore. Trade receivables rose to Rs 453.9 crore from Rs 203.5 crore, whereas inventories decreased to Rs 213.2 crore from Rs 245.8 crore. The presentation reports these balance-sheet movements without stating a causal explanation.
What operational milestones does PCCPL expect next?
PCCPL expects volume growth of 100% in the current financial year from capacity enhancement for a new agro intermediate that it says has been successfully commercialised through a more efficient process. The presentation does not provide the starting volume, capacity quantity, capital cost or revenue expected from the intermediate, so the stated volume expectation cannot be converted into a sales forecast using the disclosed material.
PCCPL also said it had supplied commercial lots for two of the three products covered by its memorandum of understanding (MoU), with volume pickup expected from Q4 FY27 onwards. In its domestic market plan, the company expects to launch two intermediate herbicide products in Q3 FY27 or Q4 FY27. These milestones are the disclosed basis for management's next-period volume expectations.
Conclusion
PCCPL's Q2 FY27 results show that domestic-led revenue growth did not translate into higher quarterly profit. Revenue increased 28.0% to Rs 326.7 crore, while PAT declined 27.4% to Rs 13.5 crore, reflecting a lower gross margin, a lower EBITDA margin, reduced other income and higher depreciation, finance cost and tax expense.
The next developments to watch are PCCPL's planned launch of two domestic intermediate herbicide products in Q3 FY27 or Q4 FY27 and its expected Q4 FY27 volume pickup for two MoU products. Management also expects 100% volume growth in the current financial year from the commercialised agro-intermediate capacity enhancement, but the presentation does not disclose a numerical sales or profit target for that plan.