










PNGS Reva H1 EBITDA margin rises to 26.3% as mix shifts
Key highlights
- PNGS Reva's H1 FY27 EBITDA margin rose to 26.3% from 19.6% in H1 FY26.
- H1 FY27 jewellery revenue excluding gold sales increased 76% to Rs 239 crore.
- H1 FY27 gross profit rose 90% to Rs 79 crore and gross margin reached 33.2%.
- Q3 FY27 sales grew 35% across the 10 Navaratri and Dussehra days.
powered by IRIS
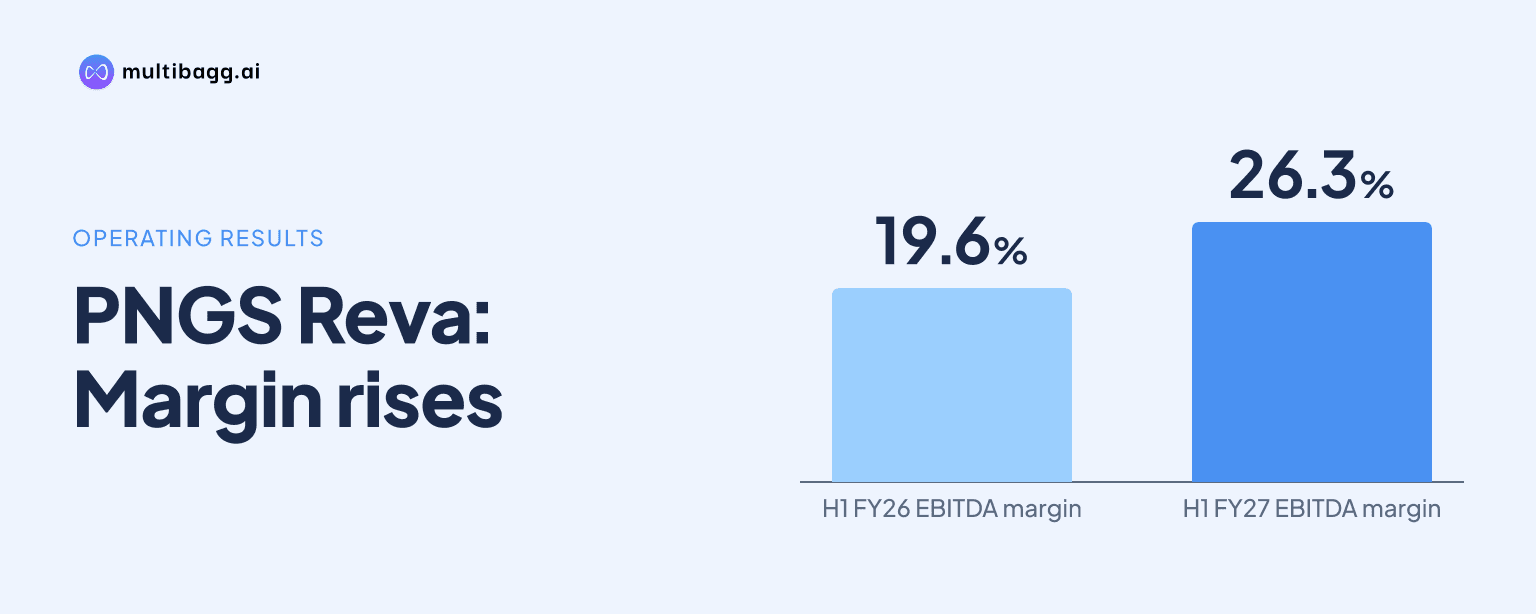
PNGS Reva Diamond Jewellery Limited reported a 26.3% earnings before interest, tax, depreciation and amortisation (EBITDA) margin in H1 FY27, up from 19.6% a year earlier, as jewellery revenue excluding gold sales rose 76% to Rs 239 crore. Management attributed the reported revenue comparison partly to lower external sales of exchanged gold scrap.
Know PNGS Reva Diamond Jewellery inside out
Results, valuation, peers and who's buying, in one view.
How did PNGS Reva's H1 FY27 profitability change?
PNGS Reva's H1 FY27 EBITDA rose 103% year on year to Rs 63 crore, and its EBITDA margin increased by 6.7 percentage points to 26.3% from 19.6% in H1 FY26. Gross profit increased 90% to Rs 79 crore, while gross margin rose by 6.5 percentage points to 33.2% from 26.7%.
Profit after tax (PAT) reached Rs 51 crore in H1 FY27, an increase of 151% year on year, with a PAT margin of 21.2%. Management said PAT remained in line with its guidance even excluding other income, which it said reflected the performance of the core business.
The same pattern appeared in Q2 FY27, although quarterly profitability was below the H1 level. Q2 gross profit was Rs 37 crore, up 50% year on year, and gross margin was 31.1%, compared with 24.2% in Q2 FY26. Q2 EBITDA rose 49% to Rs 29 crore and the EBITDA margin increased to 23.8% from 18.7%.
Why did PNGS Reva's reported revenue lag jewellery sales growth?
PNGS Reva's reported revenue growth lagged jewellery sales growth because H1 FY26 included sizeable external sales of gold scrap received through customer exchanges. Management said jewellery revenue excluding gold sales was Rs 239 crore in H1 FY27, representing growth of about 76% year on year.
Management said it received a similar quantity of exchange gold in FY27 but used that gold for captive consumption rather than selling it externally. The gold was used as the company developed and received newly fabricated jewellery, reducing the amount of separately reported business-to-business gold sales relative to FY26.
The effect was also visible in Q2 FY27. Revenue from operations was Rs 121 crore, up 17% year on year, while management said revenue excluding gold sales grew about 46%. Management described external gold-scrap trading as not being its principal business, whereas jewellery sales are business-to-consumer.
What demand trends supported PNGS Reva's H1 FY27 result?
PNGS Reva said demand remained healthy in Q2 FY27 despite an unfavourable festival-calendar comparison. Management said Q2 FY26 contained nine Navaratri festival days in September, while Q2 FY27 had no festival days, yet H1 jewellery revenue excluding gold sales increased 76% to Rs 239 crore.
Management linked demand to customers shifting from plain gold jewellery towards natural diamond-studded gold jewellery. It presented this trend alongside the increase in H1 FY27 gross margin to 33.2% from 26.7%, but did not disclose product-level revenue, volume or margin data to quantify the contribution of that shift.
Management also said Q3 FY27 began with 35% overall sales growth across the 10 Navaratri and Dussehra days. Dussehra single-day sales grew 62% year on year, with all 10 Navaratri days and Dussehra falling in early October in FY27, compared with nine festival days in September and two in October in the prior year.
Got a follow-up? Ask IRIS
How is PNGS Reva expanding its sales channels?
PNGS Reva launched three new stores during FY27 at Amanora Mall in Pune, College Road in Nashik and Jaipur, its first location outside Maharashtra. At the October 30, 2026 call, management said it had six exclusive brand outlets (EBOs), including a newly opened Bavdhan store, and expected to announce one more store during that week.
The Jaipur store established the company's presence in Rajasthan, while management said its retail expansion was focused on quality locations and customer experience. Management said stores outside Maharashtra would be more likely to be located in malls rather than on high streets, while expansion within Maharashtra includes Pune locations such as Wakad, Paud Road, Amanora and Bavdhan.
PNGS Reva also launched revadiamonds.com during FY27. Management said online sales were not expected to become sizeable for jewellery involving gold, natural diamonds and certified diamonds, but described the site as a catalogue and discovery channel that can bring customers to stores. The call did not disclose online revenue, store-level sales or the contribution of new stores to H1 EBITDA.
What could affect PNGS Reva's H2 FY27 margins and growth?
Management said it expected H2 FY27 to continue broadly in line with H1, subject to normal market conditions. It identified Diwali and the wedding season as potential contributors to growth and higher average order values after the 35% rise in sales across the early-October Navaratri and Dussehra period.
Management did not give a full-year revenue, EBITDA or margin target. It said newly opened EBOs may contribute to costs before contributing to earnings, with stores typically taking 15 to 18 months to contribute to earnings. Management therefore said EBITDA margin could move by plus or minus 200 basis points as marketing costs rise with expansion.
The company said it aimed to complete 15 EBOs over 24 months and had completed or was close to completing six at the time of the call. Management said it expected at least three more EBOs in H2 FY27 and intended to finish the remaining nine stores in less than the 18 to 20 months then remaining under its disclosed schedule.
Conclusion
PNGS Reva's H1 FY27 results show a substantial rise in profitability alongside faster growth in jewellery sales than in reported revenue. Jewellery revenue excluding gold sales increased 76% to Rs 239 crore, while gross margin rose to 33.2% and EBITDA margin reached 26.3%. The comparison was affected by the move from external sales of exchanged gold scrap in FY26 to captive use of exchanged gold in FY27.
The next measures to watch are H2 festive and wedding-season sales, the addition of at least three EBOs that management expects in H2 FY27, and the effect of expansion costs on margin. Management expects H2 performance to broadly track H1, but has cautioned that new EBO marketing costs could move EBITDA margin by plus or minus 200 basis points.