










Pushpa Jewellers Limited H1 FY27 Income Rises 83%, Margin Slips
Key highlights
- Pushpa Jewellers reported H1 FY27 standalone total income of ₹314.16 crore, up 82.85% year-on-year.
- H1 FY27 profit after tax rose 83.27% to ₹20.21 crore.
- EBITDA margin declined to 8.50% from 9.72%, while per-gram EBITDA rose to ₹1,280 from ₹1,000.
- Sales volume increased 25% to 208.5 kg from 167 kg in H1 FY26.
powered by IRIS
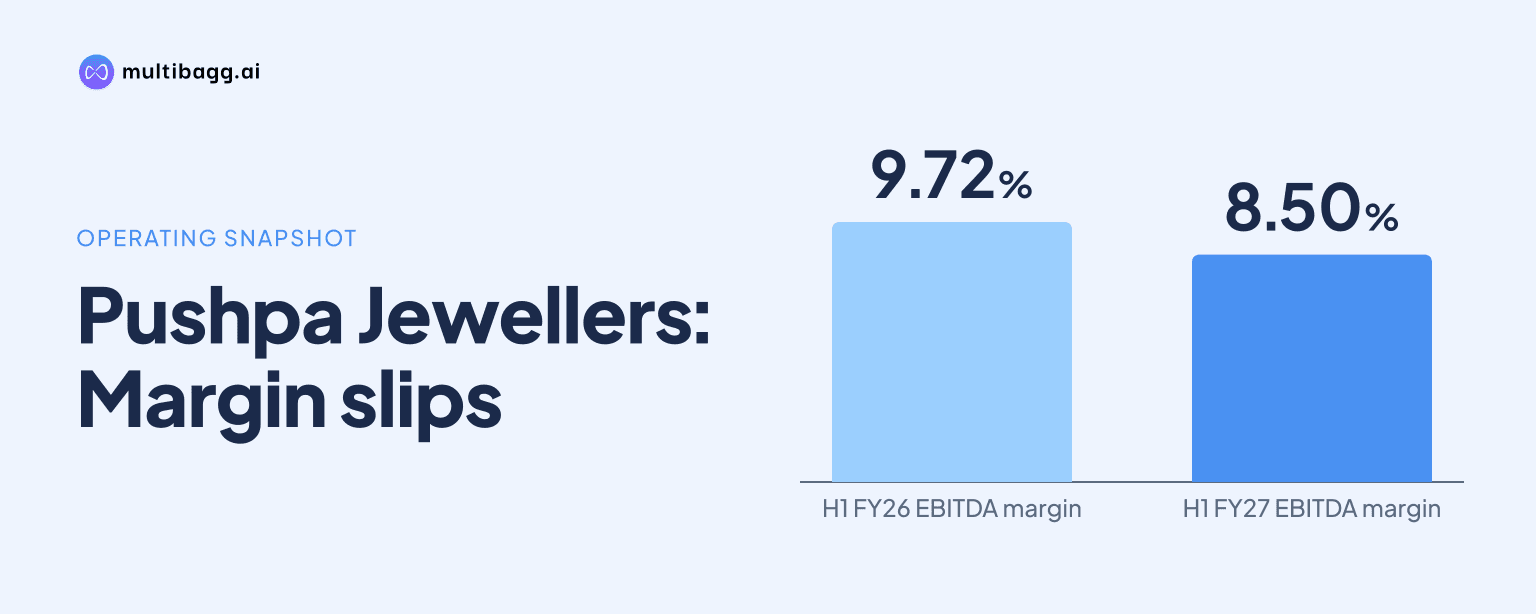
Pushpa Jewellers Limited reported H1 FY27 standalone total income of ₹314.16 crore, up 82.85% year-on-year, while EBITDA margin declined to 8.50% from 9.72% despite a 25% rise in sales volume. The company’s net profit increased 83.27% to ₹20.21 crore for the half year ended September 30, 2026.
Know Pushpa Jewellers inside out
Results, valuation, peers and who's buying, in one view.
What did Pushpa Jewellers report for H1 FY27?
Pushpa Jewellers reported strong growth in income and profit for H1 FY27, supported by higher gold realisations and increased sales volume. Standalone total income rose to ₹314.16 crore from ₹171.82 crore in the corresponding prior-year period. EBITDA increased 59.79% to ₹26.69 crore, while profit after tax rose to ₹20.21 crore.
The company discussed these unaudited standalone results during its H1 FY27 earnings call held on November 16, 2026. The call was hosted by Kirin Advisors at 5:00 PM IST. The earnings-call transcript was published on November 19, 2026, and covered performance for the half year ended September 30, 2026.
The reported income increase was materially helped by higher gold prices. Management also highlighted underlying volume growth, with gold jewellery sales volume rising 25% to 208.5 kg from 167 kg a year earlier. This indicates that the growth was not solely due to price realisation, although gold-price movement remained a significant contributor to rupee-value growth.
Why did EBITDA margin decline despite higher earnings?
Pushpa Jewellers’ EBITDA margin fell because higher gold prices diluted percentage margins, even as absolute EBITDA and per-gram profitability increased. EBITDA margin declined by 122 basis points to 8.50% from 9.72%, while EBITDA grew 59.79% to ₹26.69 crore.
Management said per-gram EBITDA improved to ₹1,280 from ₹1,000. This measure suggests improved earnings per unit sold, but the increase in gold value within sales reduced EBITDA as a percentage of total income. In a gold jewellery business, a rise in gold prices can lift reported revenue faster than value-added income, placing pressure on percentage margins.
The call summary described management as constructive on demand but cautious in its responses on future margins and financial projections. The company did not provide quantified forward guidance for demand, profitability or the second half of FY27. As a result, the available information establishes the H1 performance but does not set a specific earnings or margin target for the rest of the year.
How is Pushpa Jewellers growing its jewellery business?
Pushpa Jewellers operates a lightweight business-to-business gold jewellery model focused on 22K and 18K products. Its portfolio includes necklaces, bangles, earrings, rings, malas, pendants, mangalsutras and kadas. Products are made through independent Kolkata-based karigars and supplied across India as well as selected export markets.
The company serves more than 550 jewellers across over 20 states, according to the investor presentation. It has also launched a Mumbai fulfilment centre, adding an operating facility intended to support distribution. The combination of a lightweight product mix and a B2B customer base is central to its sales approach.
Management described jeweller demand as healthy and expressed optimism about festive and wedding demand. However, it did not quantify expected seasonal demand or provide a volume outlook. This distinction matters because H1 volume growth was stated at 25%, while the outlook comments were qualitative rather than a formal forecast.
Got a follow-up? Ask IRIS
What expansion plans did management disclose?
Pushpa Jewellers plans to open facilities in Ahmedabad and Kozhikode during April to June 2027. Management disclosed a planned property spend of ₹50 crore over three years in connection with its expansion plans.
The stated timeline places the proposed openings in the first quarter of FY28. The company did not disclose expected revenue contribution, operating costs, capacity, or a detailed funding breakdown for these facilities during the information provided. Investors therefore have clarity on the broad timing and planned property spending, but not on the financial contribution expected from the new locations.
The expansion follows the Mumbai fulfilment centre launch and points to a wider distribution footprint. For a B2B jewellery supplier, additional locations can be relevant to fulfilment and access to regional jeweller networks. However, the call material does not quantify any customer additions or order growth linked to the proposed Ahmedabad and Kozhikode facilities.
What should investors note about cash flow and operating risks?
Investors should note that the reported profit growth occurred alongside working-capital scrutiny and negative operating cash flow. The supplied summary stated inventory at ₹91 crore and negative operating cash flow of ₹51 crore, while receivables, working capital and cash flow were raised during the earnings call.
Gold jewellery operations typically involve substantial inventory requirements, and higher gold prices can increase the rupee value of inventory and working-capital needs. In Pushpa Jewellers’ case, the available material identifies these issues as discussion points but does not provide a detailed management explanation for the negative operating cash flow or a stated timetable for improvement.
Exports declined to ₹3.2 crore, according to the H1 FY27 summary. The company’s growth during the period was therefore described principally through domestic jeweller demand, higher realisations and volume growth. Its ability to maintain per-gram EBITDA, manage inventory and convert earnings into operating cash will remain relevant operating measures alongside reported income growth.
Conclusion
Pushpa Jewellers delivered 82.85% growth in H1 FY27 standalone total income and 83.27% growth in profit after tax, with sales volume increasing 25%. Yet the EBITDA margin decline to 8.50% shows that higher gold prices affected the relationship between revenue and operating profit, even as per-gram EBITDA improved.
The next disclosed operational milestones are the planned Ahmedabad and Kozhikode openings in April to June 2027 and the broader ₹50 crore property-spending plan over three years. Investors will also watch for further disclosures on margins, working capital, receivables and operating cash flow, since management did not provide quantified forward guidance on these areas.