










Safe Enterprises executed 203 stores as rollout mix shifted
Key highlights
- Safe Enterprises executed 203 stores in H1 FY27, compared with 230 stores in H1 FY26.
- Safe Enterprises reported revenue per store of Rs 38.34 lakh in H1 FY27, against Rs 51.39 lakh in FY26.
- Safe Enterprises disclosed Rs 23.02 crore of deferred orders, including Rs 20.78 crore of new-store orders.
- Safe Enterprises reported H1 FY27 revenue from operations of Rs 77.87 crore, down 30.7% year on year.
powered by IRIS
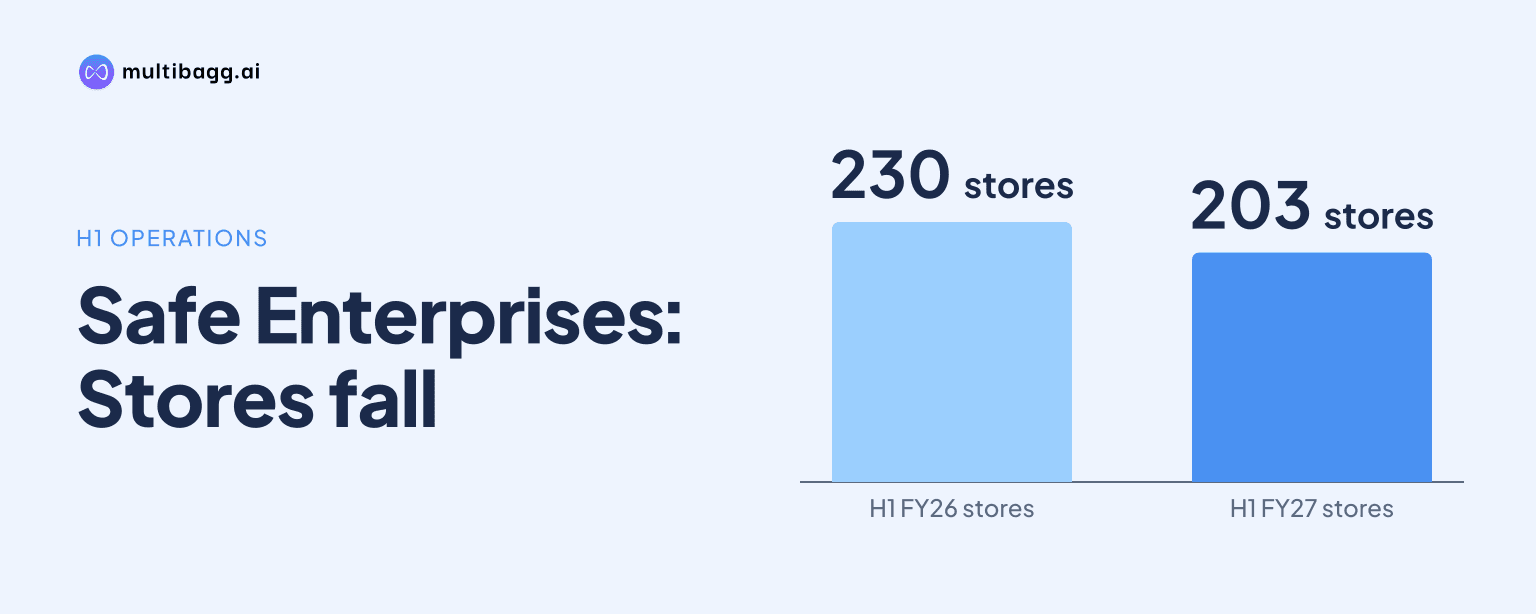
Safe Enterprises Retail Fixtures Limited executed 203 stores in H1 FY27, versus 230 in H1 FY26, while revenue per store was Rs 38.34 lakh against Rs 51.39 lakh in FY26. Safe Enterprises attributed the lower store value to deferred rollouts, later festive installations, postponed refurbishment work and a larger share of smaller-ticket compact formats rather than pricing.
Know Safe Enterprises Retail Fixtures inside out
Results, valuation, peers and who's buying, in one view.
Why did Safe Enterprises execute 203 stores in H1 FY27?
Safe Enterprises executed 203 stores in H1 FY27, 27 fewer than the 230 stores completed in H1 FY26. Its annual execution count rose from 407 stores in FY24 to 445 in FY25 before declining to 425 in FY26. FY26 comprised 230 stores in H1 and 195 in H2, making the latest first-half count lower than both H1 FY26 and half of the preceding full-year total.
Management said key retail clients had indicated significant expansion plans for the year but deferred planned store rollouts to H2 FY27 amid geopolitical uncertainty. It described this as a timing shift rather than a reduction in underlying demand. The festive season also fell later than in the previous year, shifting a substantial portion of pre-festive installations into Q3 FY27 and moving associated revenue recognition into H2 FY27.
The presentation identified Rs 23.02 crore of orders received before September that were not dispatched in H1 FY27. Safe Enterprises said clients moved festive rollouts to Q3 and H2 FY27 because of uncertain global conditions and a later festive season. New-store orders accounted for Rs 20.78 crore, or 90.3%, of this deferred-order value.
How did Safe Enterprises' revenue per store change?
Safe Enterprises reported revenue per store of Rs 38.34 lakh in H1 FY27, compared with Rs 51.39 lakh in FY26. The FY26 figure followed Rs 31.08 lakh in FY25 and Rs 24.79 lakh in FY24. The H1 FY27 result therefore reversed part of the increase recorded over the preceding two full financial years.
Management attributed the lower H1 FY27 amount to project mix rather than pricing. A higher share of compact-format, smaller-ticket installations moderated revenue per store, while clients deferred discretionary refurbishment and refresh spending. Safe Enterprises also said several larger-format rollouts were rescheduled to H2 FY27 and that these could support revenue per store when executed.
New stores accounted for 80.5% of H1 FY27 consolidated revenue of Rs 77.87 crore, while refurbishment and additions contributed 13.7%. Other operating income, comprising packing, freight and installation charges, represented 5.5%. Sale of other services, including Inssite advisory revenue and design fees, accounted for the remaining 0.4%.
Refurbishment was also a small part of the disclosed deferred orders. Of the Rs 23.02 crore total, refurbishment and additions represented Rs 0.81 crore, or 3.5%, compared with Rs 20.78 crore for new stores and Rs 1.42 crore for export orders. Safe Enterprises said delayed client planning cycles in Q1 FY27 led clients to postpone discretionary refresh spending.
Got a follow-up? Ask IRIS
What did deferred rollouts mean for H1 FY27 revenue and profit?
Safe Enterprises reported revenue from operations of Rs 77.87 crore in H1 FY27, down 30.7% from Rs 112.38 crore in H1 FY26. Operating EBITDA, calculated by the company as profit before tax plus finance costs and depreciation less other income, declined 39.4% to Rs 25.64 crore. Profit after tax declined 34.6% to Rs 21.75 crore.
Operating EBITDA margin declined to 32.9% in H1 FY27 from 37.7% in H1 FY26, while profit after tax margin moved to 27.9% from 29.6%. Safe Enterprises said neither period contained exceptional items and that the margins were calculated on revenue from operations. The revenue decline was therefore accompanied by lower reported margins in the same comparison.
The company presented an illustrative revenue view including the Rs 23.02 crore deferred orders. If those orders had been dispatched and billed by September 30, 2026, H1 FY27 revenue would have been Rs 100.89 crore, according to the presentation. That illustrative amount would be 10.2% below H1 FY26 revenue, compared with the reported 30.7% year-on-year decline; it is not reported revenue.
Safe Enterprises said 53% of deferred orders had already been received as advances. The deferred-order table lists Rs 12.13 crore of advances and Rs 10.89 crore as the balance amount to be received. Management said revenue from these orders will be recognised in H2 FY27 on dispatch, without specifying individual dispatch dates or H2 reported revenue.
What could change Safe Enterprises' store mix in H2 FY27?
Safe Enterprises said rescheduled larger-format rollouts, pre-festive installations shifted into Q3 FY27 and deferred new-store orders could alter the H2 FY27 mix. The Rs 20.78 crore new-store component of deferred orders is much larger than the Rs 0.81 crore refurbishment component. The disclosed spillover is consequently concentrated in greenfield store work rather than refurbishment cycles.
Management said Wave, its radio-frequency identification self-checkout solution, has seen encouraging early client adoption and that its revenue-per-store contribution is expected predominantly in H2 FY27. The presentation does not disclose the number of Wave installations, contract values or H1 FY27 revenue from the product. Its eventual effect on store value is therefore not quantified in the disclosed material.
Manufacturing capacity is also scheduled to change in the second half. Safe Enterprises said its Lodha Industrial and Logistics Park plant at Ambernath is set to commence operations in the last week of December 2026. The facility has a 250,000-square-foot manufacturing area, while total manufacturing area is stated to increase from 130,000 square feet before expansion to 346,505 square feet after expansion.
The Pune facility expanded by 46,505 square feet to 96,505 square feet in March 2026, while construction of the 250,000-square-foot Ambernath manufacturing area progressed on schedule through H1 FY27. After commencement, Safe Enterprises plans to move leased Navi Mumbai units into Ambernath and ramp capacity in phases. This plan does not determine customer rollout timing, but it is the company’s disclosed capacity programme for the period.
Conclusion
Safe Enterprises' H1 FY27 results show both lower store execution and a lower-value mix: 203 stores were completed and revenue per store was Rs 38.34 lakh. Reported revenue fell to Rs 77.87 crore, while Rs 23.02 crore of deferred orders, mainly new-store work, indicates that management attributes a substantial part of the disruption to rollout and dispatch timing.
The next disclosed items to watch are movement of festive and larger-format projects into Q3 and H2 FY27, dispatch-led recognition of deferred orders, and the planned last-week-of-December 2026 start of the Ambernath plant. Management also expects Wave's contribution to revenue per store to be reflected predominantly in H2 FY27, although the presentation provides no installation or revenue target for the product.