










Sanjivani Parenteral Ltd. targets Rs 35-37 crore IV-fluid FY27
Key highlights
- Sanjivani Parenteral guides Rs 35-37 crore of IV-fluid revenue in FY27.
- Pune IV-fluid utilisation is planned to rise from 40% in Q1 FY27 to 70% in Q4 FY27.
- The Pune facility began commercial production in December 2025 and has annual capacity of 6 crore bottles.
- Sanjivani Parenteral reported about Rs 3.5 crore of IV-fluid revenue in FY26 from about 20 lakh bottles.
powered by IRIS
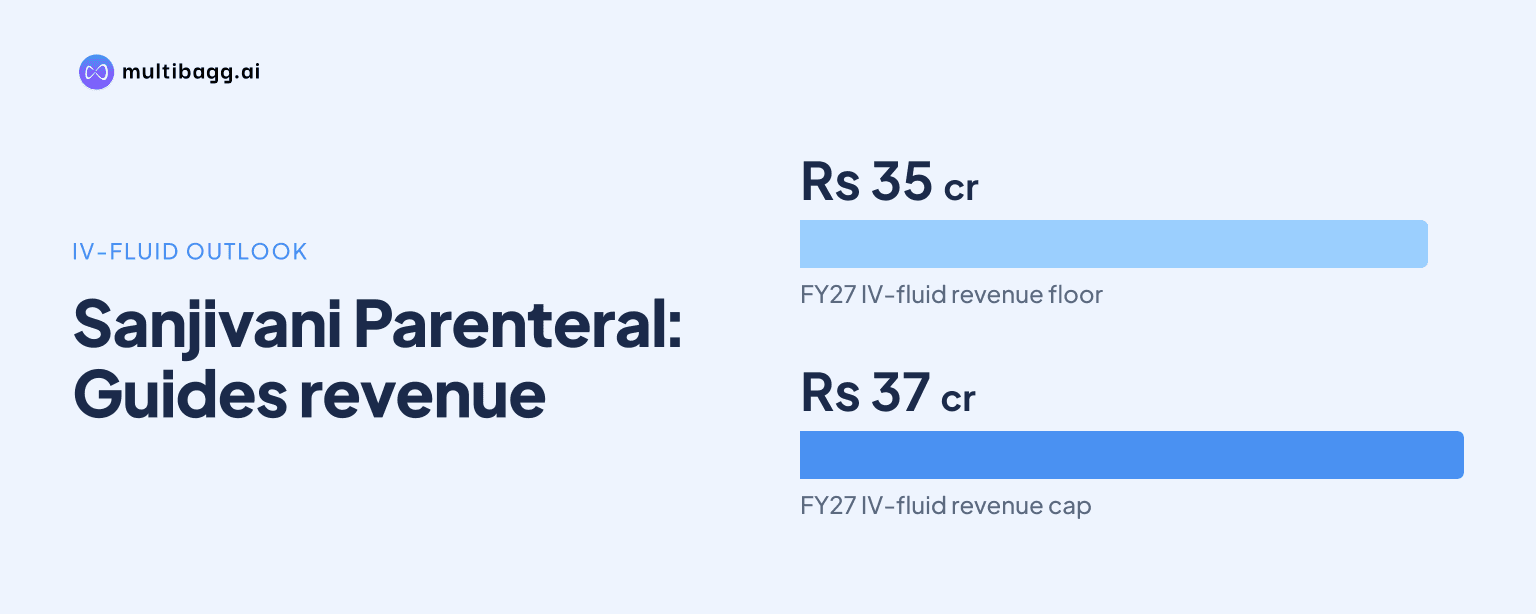
Sanjivani Parenteral Ltd. is targeting Rs 35-37 crore of IV-fluid revenue in FY27, with Pune plant utilisation planned to rise from 40% in Q1 FY27 to 70% in Q4 FY27. The facility began commercial production in December 2025 and generated about Rs 3.5 crore of revenue in FY26 from about 20 lakh bottles.
Know Sanjivani Paranteral inside out
Results, valuation, peers and who's buying, in one view.
What is Sanjivani Parenteral's FY27 IV-fluid revenue target?
Sanjivani Parenteral's management guides IV-fluid revenue of about Rs 35-37 crore in FY27 from its Pune subsidiary. The presentation describes this amount as roughly the size of the current base business, placing IV fluids alongside injectables, oral products and nutraceuticals in its multi-vertical growth platform.
The FY27 guidance compares with about Rs 3.5 crore of IV-fluid revenue in FY26. That FY26 revenue was associated with about 20 lakh bottles, while the Pune plant has annual installed capacity of 6 crore bottles, showing the scale of the production and sales ramp embedded in management's FY27 plan.
The IV-fluid business operates through SP Infusion Private Ltd. Sanjivani Parenteral says the subsidiary has been consolidated from Q3 FY26, while commercial production at the Pune facility began in December 2025. The presentation does not provide a quarterly FY26 revenue series for the subsidiary.
How is Sanjivani Parenteral planning the Pune utilisation ramp?
Sanjivani Parenteral plans to raise Pune IV-fluid utilisation from 40% in Q1 FY27 to 45% in Q2 FY27, 60% in Q3 FY27 and 70% in Q4 FY27. The plan represents a 30-percentage-point increase from the first to the final quarter, with the largest sequential step of 15 percentage points scheduled between Q2 and Q3 FY27.
The 70% Q4 FY27 target applies to a facility with installed annual capacity of 6 crore bottles. The presentation describes the plant as solar-supported and technology-led, but it does not quantify any production-cost saving or output benefit from those features.
Product-wise approvals are the stated gate to scaling the IV-fluid business, with additions planned through FY27. Sanjivani Parenteral also cites the Pune location's proximity to pharmaceutical clusters and hospitals, as well as connectivity for domestic and export demand, as elements supporting the planned capacity ramp.
How does IV-fluid revenue compare with Sanjivani Parenteral's other segments?
IV fluids recorded Rs 1.80 crore of revenue in the Q2 FY27 segment comparison, versus nil in Q2 FY26. In the same comparison, injectables increased to Rs 11.80 crore from Rs 9.20 crore, while oral products rose to Rs 5.60 crore from Rs 4.90 crore.
Injectables remained the largest business line, accounting for 61.4% of Q2 FY27 revenue. Sanjivani Parenteral attributes Rs 11.85 crore of Q2 FY27 injectable revenue in its business-structure display to four injectable products and higher dispatches after new customers were commercialised.
The presentation contains differently labelled IV-fluid figures for July 2026 to September 2026. Its business-structure display shows Rs 1.76 crore of Q2 FY27 IV-fluid revenue, while a note cites about Rs 6.65 crore of standalone IV-fluid revenue for the same July-September period; the presentation does not explain the difference between these figures.
Got a follow-up? Ask IRIS
What will determine whether Sanjivani Parenteral reaches its FY27 target?
Sanjivani Parenteral's FY27 revenue guidance depends on product-wise approvals being added during FY27 and on the planned move to 70% utilisation in Q4 FY27. Management identifies approvals as the scale-up gate, meaning installed capacity alone does not determine the pace at which the facility can expand its saleable IV-fluid portfolio.
Management says the IV-fluid operation had met its EBITDA, or earnings before interest, tax, depreciation and amortisation, margin targets in FY26. It expects bottom-line breakeven in FY27 as depreciation and interest normalise, although the presentation does not specify a quarter for that breakeven.
The disclosed steady-state EBITDA margin target is 17-18%. This is a management target rather than a reported FY26 EBITDA margin, and it sits alongside the Rs 35-37 crore FY27 revenue guidance and the 70% Q4 FY27 utilisation target.
Sanjivani Parenteral also expects injectables to grow 10-12% in FY27 and tablets to grow 7-8%. Tablet and capsule dossier approvals are intended to expand the oral portfolio, while IV-fluid product approvals remain the specifically identified requirement for the Pune facility's scale-up.
Conclusion
Sanjivani Parenteral is seeking to establish IV fluids as a material revenue vertical, with FY27 guidance of Rs 35-37 crore compared with about Rs 3.5 crore in FY26. The target rests on a recent Pune facility with 6 crore bottles of annual capacity, a planned utilisation increase from 40% to 70% through FY27, and expansion beyond the Rs 1.80 crore IV-fluid revenue shown in the Q2 FY27 segment comparison.
The next disclosed milestones are product-wise approvals through FY27, the planned increase to 60% utilisation in Q3 FY27 and 70% in Q4 FY27. Management also expects FY27 bottom-line breakeven as depreciation and interest normalise, while its stated steady-state EBITDA margin target is 17-18%.