










Carraro India forecasts 23% annual 4WD tractor growth to 2029
Key highlights
- Carraro forecasts India’s 4WD tractor market will rise from 213,000 units in 2024E to 600,000 units in 2029E.
- Carraro projects a 23.0% CAGR for 4WD tractors, versus 2.8% for India’s 2WD tractor market.
- Carraro states it has more than 50% share of non-captive Indian agricultural 4WD axle volumes above 40 HP.
- Carraro reported 79.9% raw-material localisation in Q2 FY27, up from 78.1% in FY26.
powered by IRIS
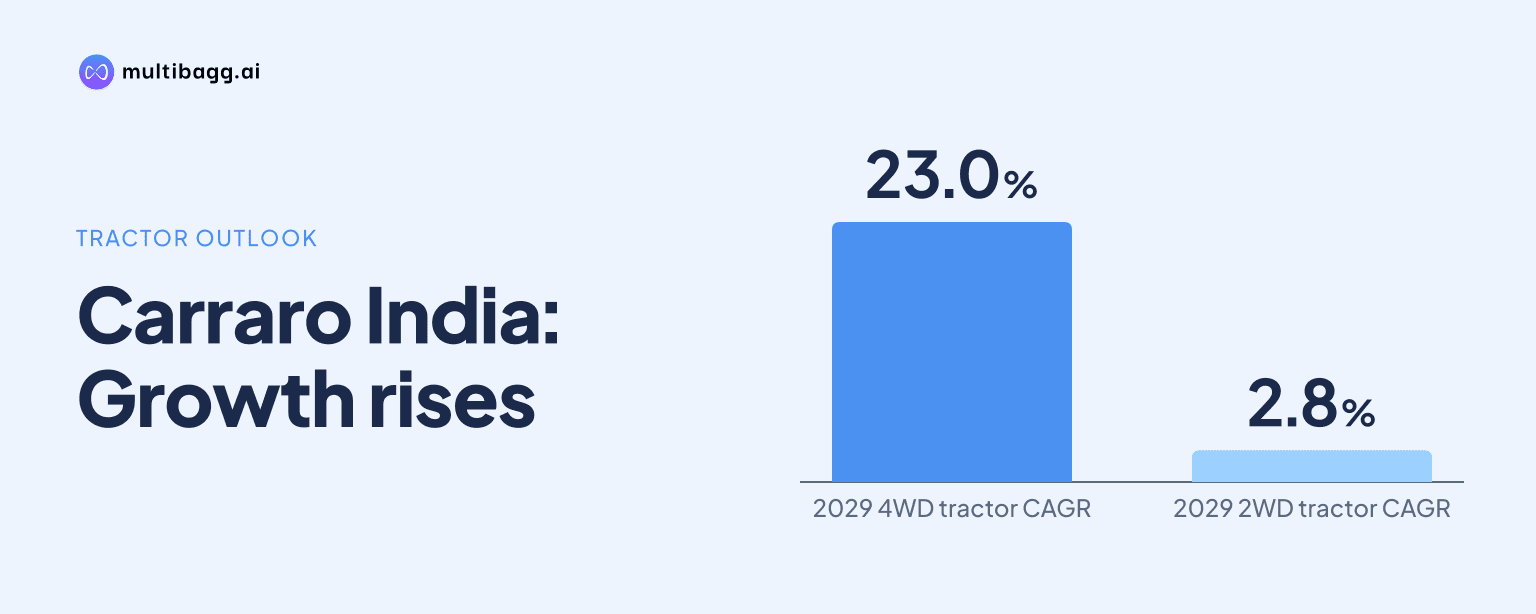
Carraro India forecasts that India’s four-wheel-drive, or 4WD, tractor market will grow at a 23.0% compound annual growth rate to 600,000 units in 2029E from 213,000 units in 2024E. The projection exceeds the 2.8% forecast growth for two-wheel-drive, or 2WD, tractors and supports Carraro’s focus on axles, transmission systems, localisation and electric driveline development.
Know Carraro India inside out
Results, valuation, peers and who's buying, in one view.
How fast is India’s 4WD tractor market expected to grow?
India’s 4WD tractor market is expected to rise by 387,000 units, from 213,000 in 2024E to 600,000 in 2029E, at a 23.0% CAGR. Carraro’s market data also show that 4WD volumes increased from 80,000 units in 2019A to the 2024E estimate. A denotes actuals and E denotes estimates, with the presentation using calendar-year data.
Carraro links the 4WD outlook to a shift toward better-efficiency tractors and increased demand for machines in the 41 horsepower, or HP, to 50 HP range. The 23.0% 4WD forecast is above the 8.2% CAGR presented for India’s total agricultural tractor market, which is projected to expand from 1.064 million units in 2024E to 1.578 million units in 2029E.
How does the 4WD opportunity compare with other vehicle markets?
The 4WD tractor segment has the highest projected growth rate among the Indian end markets quantified by Carraro. Its 23.0% CAGR compares with 5.0% for the total construction-vehicle market and 5.0% for backhoe loaders between 2024E and 2029E.
Construction-vehicle volumes are projected to increase from 116,000 units in 2024E to 147,000 in 2029E, while backhoe-loader volumes rise from 48,000 to 62,000. Carraro identifies rapid urbanisation and infrastructure development as demand drivers, and says compact construction vehicles are expected to grow at a higher rate.
The difference is also marked within tractors: 2WD volumes are forecast to add 126,000 units from 2024E to 2029E, compared with 387,000 units for 4WD. Carraro states that farm mechanisation should support overall tractor demand and that India consumes 35% to 40% of tractors sold globally.
What is Carraro’s stated position in the 4WD driveline market?
Carraro states that it has more than 50% share of non-captive Indian agricultural 4WD axle volumes above 40 HP. The presentation attributes this market-share measure to a Markets and Markets report; non-captive volumes refer to components supplied independently rather than made in-house by an original equipment manufacturer, or OEM.
Carraro also describes itself as the leading sole supplier in the non-captive agricultural-tractor transmission segment and as a market leader in transmission systems for tractors up to 150 HP with 4WD capability. It identifies product customisation, longstanding customer relationships, manufacturing infrastructure and switching costs as mechanisms supporting its position, but does not disclose sales by product or customer.
For construction vehicles, Carraro reports more than 60% share of non-captive Indian transmission volumes. Its examples include TCB80 transmissions in 2WD, 4WD and SPS versions, along with 28.32 and 28.43 rear rigid axles and a 26.22 front steering axle for backhoe loaders and loader series.
Got a follow-up? Ask IRIS
How is Carraro localising its supplier base?
Carraro reported raw-material localisation of 79.9% in Q2 FY27, up 1.8 percentage points from 78.1% in FY26. As of September 2026, it had 252 suppliers, including 180 domestic suppliers, across locations identified as the National Capital Region, Rajkot, Maharashtra, Karnataka and Tamil Nadu.
Carraro’s supplier programme requires a minimum of two suppliers per component and at least two raw-material suppliers. The company says this mechanism is intended to limit single-source dependence, while value analysis, engineering consulting and logistics optimisation are intended to lower production costs and reduce lead times.
The company also lists rapid improvement workshops, long-term agreements, periodic engagement and formalised supplier partnerships as measures to maintain supplier relationships. Carraro identifies vertical integration of key gearbox components as an initiative, but its presentation provides no future localisation percentage target or implementation timetable.
What electric driveline products is Carraro developing?
Carraro is developing transmission-hydrostatic-electric, or THE, solutions for electric off-highway vehicles and transmission systems for electric tractors. Its stated development path begins with standard drivelines and portal axles before moving to a specific driveline for electric tractors, alongside higher-HP tractor transmissions.
Carraro says it provided engineering services to the Carraro Group Luxembourg research and development centre and a customer in developing E-trans. The company says this work has enabled it to internalise technical capabilities for electric projects, though it discloses no customer name, product launch date, sales volume or revenue target.
The electric programme is presented as one of five growth-strategy pillars, alongside industry opportunity, complex driveline components, customised solutions, and supplier diversification and localisation. Carraro characterises THE and electric-tractor transmission work as potential collaboration opportunities in product development rather than a disclosed replacement for conventional axle and transmission products.
Conclusion
Carraro’s presentation centres on a projected change in India’s tractor mix, with 4WD demand expected to reach 600,000 units in 2029E from 213,000 in 2024E, while 2WD demand is projected to reach 978,000 units. Carraro aims to address that opportunity through its stated more-than-50% share in non-captive 4WD axles above 40 HP, customised driveline offerings and 79.9% raw-material localisation in Q2 FY27.
The next disclosed matters to watch are whether 4WD volumes progress toward the 23.0% CAGR forecast, whether raw-material localisation advances beyond 79.9%, and whether E-trans and THE engineering work produces identified commercial products. Carraro has outlined a product-development plan for electric drivelines, but has not disclosed a launch schedule, volume objective or revenue target.