










Savita Q2 FY27 EBITDA Margin Hits 17.3% as PBT Rises 410%
Key highlights
- Savita’s Q2 FY27 total income rose 57.2% year on year to Rs 1,714.1 crore.
- Savita’s Q2 FY27 EBITDA margin increased to 17.3% from 6.0% in Q2 FY26.
- Savita’s Q2 FY27 PBT rose 410.1% year on year to Rs 283.1 crore.
- Savita plans to increase Lubricants capacity by 50% and double Diesel Exhaust Fluids capacity.
powered by IRIS
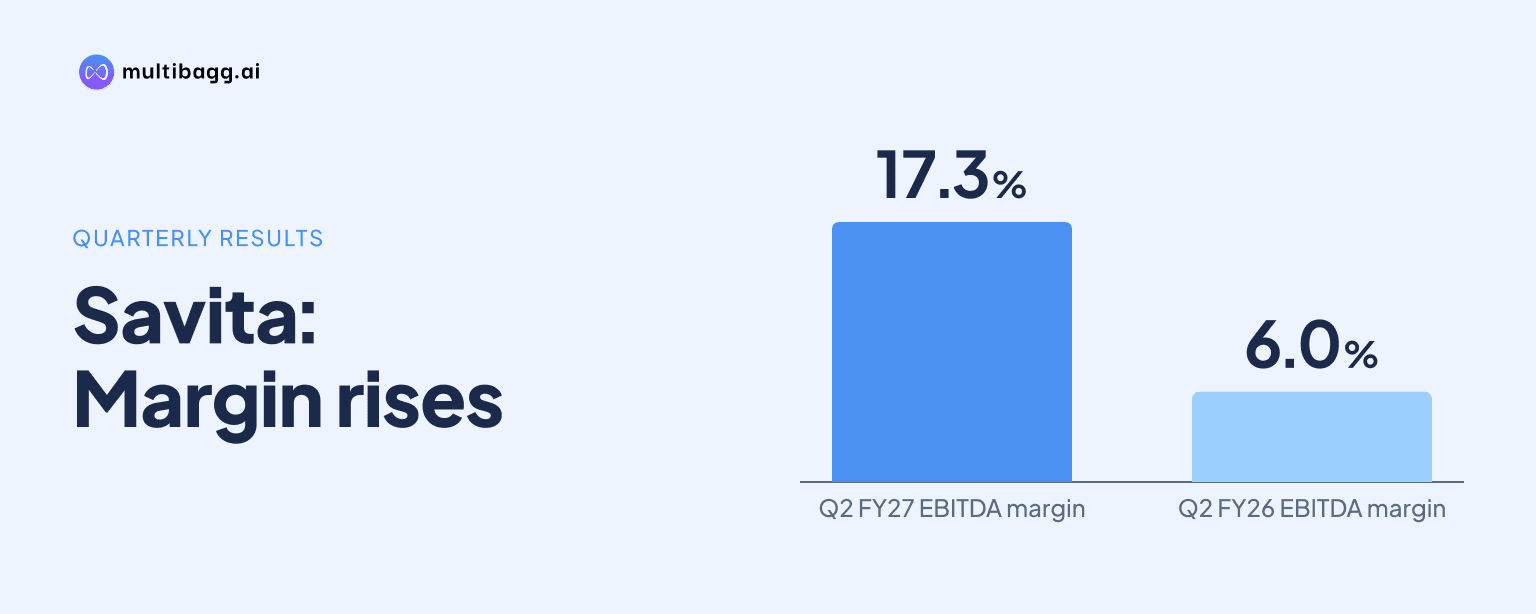
Savita Oil Technologies Limited reported a 17.3% earnings before interest, tax, depreciation and amortisation (EBITDA) margin in Q2 FY27, up from 6.0% a year earlier, as profit before tax rose 410.1% to Rs 283.1 crore. Savita’s consolidated total income increased 57.2% to Rs 1,714.1 crore in the quarter.
Know Savita Oil Technologies inside out
Results, valuation, peers and who's buying, in one view.
How did Savita perform in Q2 FY27?
Savita delivered its highest quarterly total income of Rs 1,714.1 crore in Q2 FY27, compared with Rs 1,090.4 crore in Q2 FY26. Revenue from operations rose to Rs 1,709.4 crore from Rs 1,075.9 crore, while other income declined to Rs 4.7 crore from Rs 14.5 crore. The 57.2% increase in total income therefore coincided with higher revenue from operations.
EBITDA increased 350.5% year on year to Rs 296.4 crore in Q2 FY27 from Rs 65.8 crore, lifting the EBITDA margin by 11.3 percentage points to 17.3%. Profit before tax (PBT) increased to Rs 283.1 crore from Rs 55.5 crore, while profit after tax (PAT) rose 421.9% to Rs 211.9 crore from Rs 40.6 crore. PAT margin reached 12.4%, compared with 3.7% in Q2 FY26.
What changed in Savita’s costs and profitability?
Savita recorded cost of goods sold of Rs 1,269.3 crore in Q2 FY27, up from Rs 889.6 crore in Q2 FY26, alongside a Rs 230.6 crore increase in EBITDA. Employee cost rose to Rs 30.0 crore from Rs 26.4 crore, while other expenses increased to Rs 118.4 crore from Rs 108.6 crore. Savita said crude oil and refined-product price volatility, together with tighter supply, increased input feedstock costs and prices across its portfolio during the quarter.
Below EBITDA, depreciation was Rs 6.5 crore in Q2 FY27 against Rs 6.3 crore a year earlier, while finance cost was Rs 6.8 crore against Rs 4.0 crore. Savita reported no exceptional-item gain or loss in either Q2 FY27 or Q2 FY26. Tax expense rose to Rs 71.2 crore from Rs 14.9 crore as PBT increased, and earnings per share rose to Rs 30.90 from Rs 5.92.
How did Q2 FY27 compare with Q1 FY27 and H1 FY27?
Savita’s Q2 FY27 total income was 13.3% higher than Rs 1,512.7 crore in Q1 FY27, but EBITDA was 25.3% lower than Rs 396.7 crore in the preceding quarter. EBITDA margin declined by 8.9 percentage points from 26.2% in Q1 FY27 to 17.3% in Q2 FY27. PBT decreased 26.8% sequentially from Rs 386.6 crore despite the increase in quarterly total income.
For H1 FY27, Savita reported total income of Rs 3,224.8 crore, up 53.3% from Rs 2,103.2 crore in H1 FY26. EBITDA rose 361.8% to Rs 693.1 crore from Rs 150.1 crore, and H1 EBITDA margin reached 21.5%, compared with 7.1%. H1 PBT increased 424.1% to Rs 669.7 crore, while PAT rose 418.0% to Rs 499.9 crore and PAT margin expanded to 15.5% from 4.6%.
Got a follow-up? Ask IRIS
Which business trends and risks did Savita identify?
Savita said Transformer Oils, White Oils and export volumes registered double-digit sequential growth in Q2 FY27, while its Lubricant division delivered double-digit volume growth in H1 FY27. Management also said exports and the Lubricating Oil divisions posted healthy double-digit volume growth in the first half. Savita did not disclose revenue or profit by division, so the relative contribution of these activities to H1 EBITDA of Rs 693.1 crore is not stated.
Management said the Savsol Ester5 automotive-lubricant range, launched last year, was growing at four times the industry growth rate for automotive lubricants. Savita also identified significant daily volatility in key feedstock supplies as a continuing factor and said it remained cautiously optimistic. This disclosure is relevant to Q2 FY27 cost of goods sold of Rs 1,269.3 crore because management cited both tighter feedstock supply and changing crude and refined-product prices.
What capacity and product plans has Savita disclosed?
Savita plans a project to increase Lubricants capacity by 50% and double Diesel Exhaust Fluids capacity, citing continuing double-digit Lubricants growth. The presentation does not provide an investment amount, project location, commissioning timetable or expected production capacity. Savita therefore does not disclose the expected financial effect of the proposed expansion.
Savita said ester-based refrigeration-compressor fluids continued to receive approvals from existing and new original equipment manufacturers (OEMs). Its research and development work is focused on tailoring ester-based immersion coolants for electric-vehicle batteries and stationary battery systems used in Battery Energy Storage Systems. Management described these fluids as having potential, but Savita did not disclose their current sales, margins, order book or revenue target.
Conclusion
Savita’s Q2 FY27 results combined higher income with a substantial year-on-year increase in profitability: total income rose 57.2% to Rs 1,714.1 crore, EBITDA rose 350.5% to Rs 296.4 crore, and PBT rose 410.1% to Rs 283.1 crore. The comparison with Q1 FY27 adds context, as total income grew 13.3% sequentially while EBITDA declined 25.3% and margin moved from 26.2% to 17.3%.
The next disclosed matters to watch are Savita’s planned 50% Lubricants capacity expansion and doubling of Diesel Exhaust Fluids capacity, for which no timing or cost has been provided. Management also identified feedstock availability and daily price volatility as unresolved operating factors, while Savsol Ester5 growth and further OEM approvals for ester-based fluids may show how Savita’s product plans develop after H1 FY27.