










SEDEMAC trailing revenue rises 48% to Rs 1,265 crore at Q2FY27
Key highlights
- SEDEMAC reported TTM Q2FY27 revenue of Rs 1,265 crore, up 48% year on year.
- Industrial revenue rose Rs 406 crore year on year to Rs 1,135 crore in TTM Q2FY27.
- TTM Q2FY27 EBITDA was Rs 250 crore, with a 19.8% margin unchanged year on year.
- TTM Q2FY27 profit after tax rose 82% to Rs 129 crore, while RoCE was 34%.
powered by IRIS
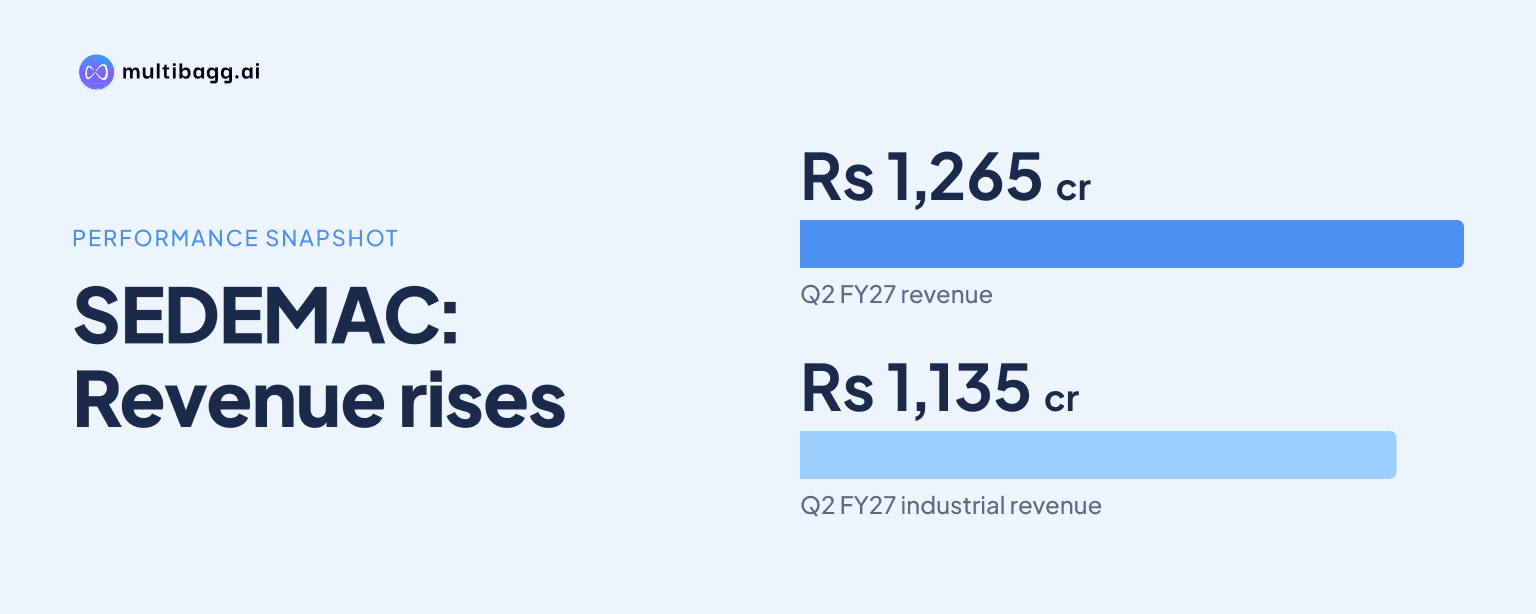
SEDEMAC Mechatronics Limited reported Rs 1,265 crore of trailing-12-month (TTM) revenue in Q2FY27, 48% above TTM Q2FY26, as industrial revenue rose Rs 406 crore to Rs 1,135 crore. Earnings before interest, tax, depreciation and amortisation (EBITDA) reached Rs 250 crore, while profit after tax increased 82% to Rs 129 crore.
Know Sedemac Mechatronics inside out
Results, valuation, peers and who's buying, in one view.
What drove SEDEMAC's TTM Q2FY27 revenue growth?
SEDEMAC's industrial segment accounted for nearly all of the Rs 409 crore increase in TTM revenue between TTM Q2FY26 and TTM Q2FY27. Industrial revenue increased Rs 406 crore, from Rs 729 crore to Rs 1,135 crore, while mobility revenue increased Rs 3 crore, from Rs 127 crore to Rs 130 crore. Total revenue rose from Rs 856 crore to Rs 1,265 crore.
Industrial sales also became a larger part of SEDEMAC's reported revenue over three years. Industrial revenue was Rs 396 crore out of total revenue of Rs 477 crore in TTM Q2FY24, compared with Rs 1,135 crore out of Rs 1,265 crore in TTM Q2FY27. SEDEMAC reported a 38% three-year compound annual growth rate for total revenue and 48% year-on-year growth in the latest TTM period.
SEDEMAC defines TTM Q2FY27 as October 2025 to September 2026. It designs and supplies control-intensive electronic control units (ECUs) to vehicle and industrial original equipment manufacturers (OEMs) in India, the United States and Europe, and says most revenue comes from ECUs incorporating control technologies developed in-house. Cumulative sales exceeded 14 million control-intensive ECUs.
Why did SEDEMAC's profit after tax grow faster than revenue?
The presentation does not identify a specific driver for faster profit-after-tax growth, but it reports an 82% year-on-year increase in profit after tax to Rs 129 crore, compared with 48% revenue growth. EBITDA increased 47% to Rs 250 crore, and its margin was unchanged at 19.8%. The profit-after-tax margin increased to 10.2% from 8.3%.
The longer comparison shows profit growth exceeding sales growth over three years. EBITDA rose from Rs 63 crore in TTM Q2FY24 to Rs 250 crore in TTM Q2FY27, lifting its margin from 13.2% to 19.8%. Profit after tax increased from Rs 19 crore to Rs 129 crore, while its margin rose from 4.0% to 10.2%; SEDEMAC reported an 89% three-year compound annual growth rate for profit after tax.
Return on capital employed (RoCE) was 34% in TTM Q2FY27, versus 38% in TTM Q2FY26 and 22% in TTM Q2FY24. SEDEMAC defines RoCE as earnings before interest and tax divided by capital employed, with capital employed calculated as average tangible net worth plus total debt. The measure was 12 percentage points above TTM Q2FY24 but 4 percentage points below the preceding TTM period.
How did SEDEMAC's Q2FY27 and H1FY27 performance compare?
SEDEMAC's Q2FY27 revenue rose 40% year on year to Rs 401 crore, while EBITDA increased 22% to Rs 76 crore and profit after tax rose 30% to Rs 39 crore. The EBITDA margin declined to 19.0% from 21.7%, and the profit-after-tax margin declined to 9.8% from 10.5%.
In the first half (H1) of FY27, revenue increased 41% year on year to Rs 710 crore. EBITDA rose 26% to Rs 136 crore from Rs 108 crore, with its margin falling to 19.2% from 21.4%. Profit after tax increased 53% to Rs 72 crore from Rs 47 crore, and its margin rose to 10.2% from 9.4%.
The quarterly and half-year comparisons differ from the TTM margin outcome. TTM Q2FY27 EBITDA margin held at 19.8%, although the Q2FY27 margin was 2.7 percentage points below Q2FY26. H1FY27 profit-after-tax margin increased by 0.8 percentage points year on year despite the 2.2-percentage-point decline in EBITDA margin.
Got a follow-up? Ask IRIS
What operating indicators and market conditions matter for SEDEMAC?
SEDEMAC sold 4,597,435 control-intensive ECUs in TTM Q2FY27, up from 3,187,171 in TTM Q2FY26. The increase in unit sales accompanied revenue growth from Rs 856 crore to Rs 1,265 crore. The presentation does not disclose ECU pricing, revenue per unit or volume by industrial and mobility segment.
For industrial generators, SEDEMAC said weaker Atlantic hurricane activity in North America during 2025 reduced demand for electronic fuel injection (EFI) ECUs, although some demand recovery was being seen. This disclosure relates to a segment that generated Rs 1,135 crore of TTM Q2FY27 revenue, but the presentation does not quantify the sales affected by North American generator EFI ECU demand.
In mobility, SEDEMAC said its integrated starter generator (ISG) and EFI ECU had shipped 1 million units in about two years since start of production in October 2024. Export internal-combustion-engine three-wheeler ISG ECUs and electric two-wheeler motor-control units (MCUs) introduced for production in FY26 had fully ramped up, while ISG-plus-EFI ECUs were continuing to ramp up.
What milestones has SEDEMAC disclosed for FY27 and FY28?
SEDEMAC has disclosed production and customer-program milestones rather than financial targets. Its MF4 facility in Chakan, Pune is expected to begin electric-machine shipments in Q3FY27, while MF3 in Chakan has started pilot production. MF5 at Shoolagiri, Tamil Nadu, is intended for future customer shipments in South India and has an allotted plot of about 13 acres.
For product programmes, SEDEMAC said a European two- and three-wheeler OEM win for an ISG ECU and magneto kit is likely to start production in H1FY28. A commercial-vehicle auxiliary control unit start of production was pushed to H1FY28, a commercial-vehicle EFI ECU start is likely in H1FY28, and an electric light-commercial-vehicle MCU start is likely in H2FY27. A power-tools MCU using switched reluctance control technology is also likely to start in H1FY28.
Conclusion
SEDEMAC's TTM Q2FY27 results show that industrial revenue supplied Rs 406 crore of the Rs 409 crore year-on-year increase in revenue, taking total revenue to Rs 1,265 crore. EBITDA reached Rs 250 crore at a 19.8% margin, while profit after tax reached Rs 129 crore and its margin rose to 10.2%. RoCE, however, declined to 34% from 38% a year earlier.
The next disclosed milestones are electric-machine shipments from MF4 expected in Q3FY27 and an electric light-commercial-vehicle MCU start likely in H2FY27. SEDEMAC also indicated that its European ISG ECU and magneto-kit programme, commercial-vehicle control programmes and power-tools MCU programme are likely to start production in H1FY28, while North American generator EFI ECU demand was showing some recovery.