










TCI Express targets 14%-15% H2 FY27 growth on pricing
Key highlights
- TCI Express is targeting 14%-15% growth in the remaining two quarters of FY27.
- TCI Express reported Q2 FY27 income from operations of Rs 336 crore, up about 9% year on year.
- TCI Express handled 265,000 tonnes in Q2 FY27, up 7.5% year on year.
- TCI Express reported a Q2 FY27 EBITDA margin of 12.7%, versus 12.4% a year earlier.
powered by IRIS
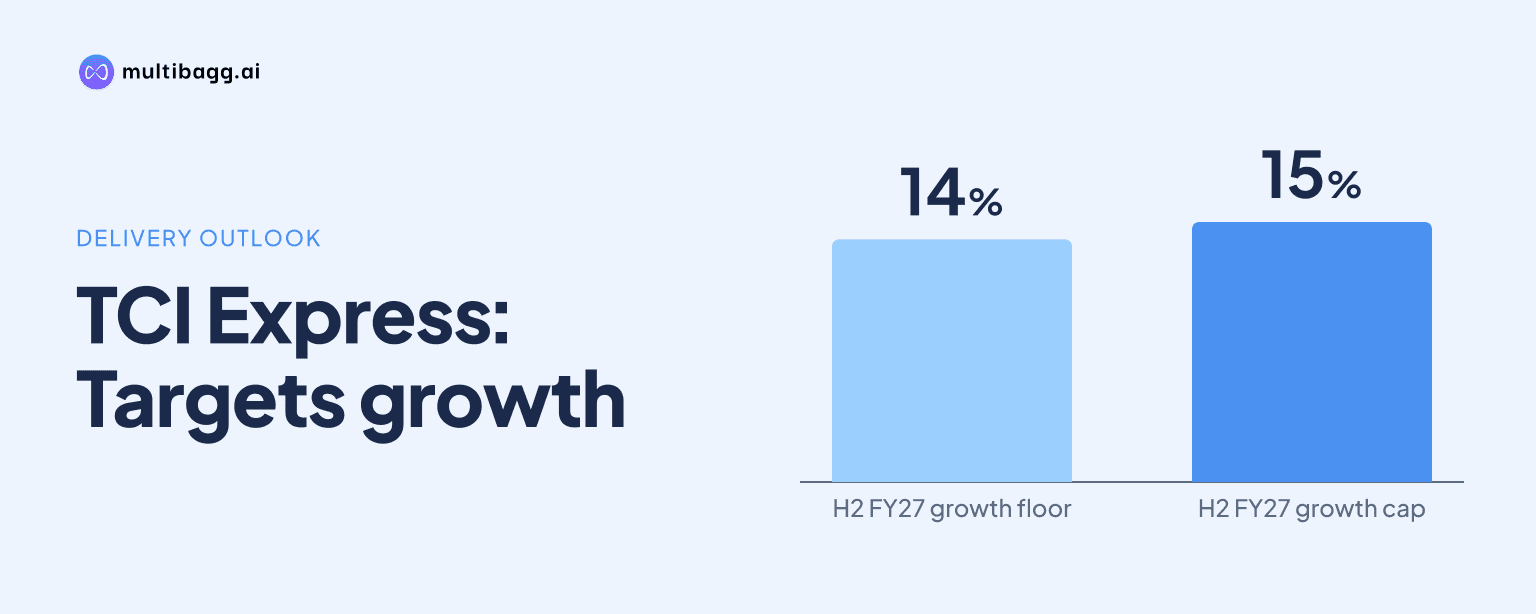
TCI Express is targeting 14%-15% growth in the remaining two quarters of FY27, after income from operations rose 8.8% to Rs 648 crore in H1 FY27, with management citing an October pickup, expected 11%-12% volume growth and a net price increase of about 1.5%.
Know TCI Express inside out
Results, valuation, peers and who's buying, in one view.
What is TCI Express's H2 FY27 growth target?
TCI Express is targeting growth of about 14%-15% in the final two quarters of FY27, management said, versus about 9% growth in both Surface Express and the overall business in H1 FY27. Management described October as strong and said its business pipeline covers Surface Express, Air Express, rail and E-Commerce Express. This is management's stated outlook, rather than a reported result.
TCI Express reported Q2 FY27 tonnage of 265,000 tonnes, up 7.5% year on year, while income from operations increased about 9% to Rs 336 crore from Rs 309 crore. Management's target of around 11%-12% volume growth in H2 FY27 would therefore represent a higher run rate than Q2 volume growth. Management also reiterated its commitment to finish FY27 with double-digit volume and revenue growth.
Surface Express remains central to the plan because its growth broadly matched the 9% overall increase in H1 FY27, while the faster-growing newer services have smaller shares. Domestic Air Express grew 29%, International Air Express rose 26%, and E-Commerce Express increased 52% in H1 FY27. C2C Express declined because fuel-linked rates were not conducive, but management said normalized rates should enable growth from Q3 FY27.
How will pricing and volume support TCI Express's H2 FY27 growth?
TCI Express said it is obtaining a net price increase of about 1.5% after passing fuel-cost increases to customers, and management expects that trend to continue through Q3 and Q4 FY27. Management said increased volumes give TCI Express scope to implement the higher prices, alongside the stated 11%-12% volume-growth objective for the second half.
Management said customers in express logistics are prioritizing service response and on-time delivery for higher-value cargo rather than seeking price cuts. It added that freight is about 1.5% of cargo value, though this was a management observation and not a disclosed company-wide yield calculation. TCI Express said price increases and volume growth should support revenue across its service lines.
The reported results show that revenue growth exceeded Q2 volume growth by about 1.5 percentage points, although TCI Express did not quantify the respective contribution from pricing, mix or other factors. In H1 FY27, total income rose 8.7% to Rs 655 crore from Rs 602 crore, close to the 8.8% rise in income from operations. That comparison indicates that the H2 target requires a clear acceleration from the first-half revenue trend.
Got a follow-up? Ask IRIS
Can TCI Express expand margins while accelerating growth?
TCI Express said margin expansion should continue in Q3 and Q4 FY27 and management expects a full-year improvement of at least 50 to 100 basis points from the prior year. One basis point is one-hundredth of a percentage point. Management attributed the Q2 FY27 margin increase to operating performance, higher capacity utilization across the network and cost discipline.
Q2 FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, rose about 11% to Rs 43 crore, faster than the 9% increase in income from operations. EBITDA margin consequently reached 12.7% from 12.4%, which management described as the highest level in five quarters. Profit after tax rose 6% to Rs 27 crore, with a 7.9% margin, while earnings per share were Rs 6.90, also up 6%.
For H1 FY27, EBITDA increased 10.8% to Rs 80 crore, exceeding the 8.8% increase in income from operations, and margin rose to 12.2% from 12.0%. Profit before tax increased 6% to Rs 64.70 crore and profit after tax grew 6% to Rs 49 crore. The smaller increase in profit after tax than EBITDA means the reported operating-margin improvement did not translate into the same rate of bottom-line growth in the first half.
Automation is one cost mechanism cited by TCI Express. Management said its two automated sorting centres reduced labour requirements and truck turnaround times, lowering annual direct costs by an estimated 40 to 50 basis points. Ahmedabad and Kolkata are due for automation after construction, with management expecting completion in Q1 or, at the latest, Q2 of the following financial year.
Which operations and investments underpin TCI Express's plan?
TCI Express is pursuing SME and e-commerce opportunities alongside its Surface Express network, while keeping a 50:50 business mix between small and medium enterprises, or SMEs, and large customers in Q2 FY27. Management said that mix is important for margin levels. For E-Commerce Express, TCI Express is targeting direct-to-consumer sellers, platform-connected merchants and selected smaller e-commerce operators, rather than focusing on a few large platforms.
TCI Express said its current business-to-consumer E-Commerce Express work is mainly last-mile delivery, while business-to-business e-commerce customers are another focus. Management cited Surat, Bengaluru and Ludhiana as markets for dedicated city teams and said it is concentrating on Tier 2 cities where merchants ship directly to consumers. It also said platform registrations, including ONDC, provide access to merchants, although the related e-commerce business remains small.
Investment in capacity is continuing alongside the growth objective. TCI Express spent about Rs 80 crore on capital expenditure in H1 FY27 for branch expansion, sorting-centre construction and information-technology infrastructure. As of September 30, 2026, it had net cash of about Rs 77 crore, liquid assets of Rs 93 crore and total debt of Rs 15 crore, while H1 FY27 cash flow from operations was Rs 28 crore.
Management said three projects in Lucknow, Ahmedabad and Kolkata should be completed by the end of FY27, excluding the corporate-office project that is also under construction. It expects Ahmedabad and Kolkata automation to follow in the next financial year. TCI Express has completed six or seven sorting-centre conversions and expects to reach nine with these three projects, before considering Mumbai, Chennai and Bengaluru over the next three to four years.
Conclusion
TCI Express's H2 FY27 target depends on growth rising from 8.8% in H1 FY27 to 14%-15% in the remaining two quarters, supported by management's expected 11%-12% volume growth and a 1.5% net price increase. Q2 FY27 EBITDA margin of 12.7%, up from 12.4%, and H1 EBITDA growth of 10.8% versus 8.8% income-from-operations growth provide the reported basis for management's margin-expansion expectation.
The next disclosed milestones are Q3 FY27 volume growth, pricing realization and the planned completion of the Lucknow, Ahmedabad and Kolkata projects by FY27-end. Management also plans to convert 12 to 15 sorting centres, with 80%-85% of revenue expected to move through owned centres by around FY30 or FY31, and indicated Rs 100 crore-plus annual capital expenditure over the next four to five years.