










Tonbo expects H2 FY27 revenue to materially exceed H1 sales
Key highlights
- Tonbo reported H1 FY27 revenue from operations of Rs 219 crore, compared with Rs 77 crore in H1 FY26.
- Tonbo recorded Rs 183 crore of revenue in Q2 FY27, versus Rs 36 crore in Q1 FY27.
- Tonbo had a Rs 250 crore order book as of September 2026 and Rs 408 crore of contracts under negotiation.
- Tonbo reported H1 FY27 EBITDA of Rs 31.15 crore at a 14.2% margin.
powered by IRIS
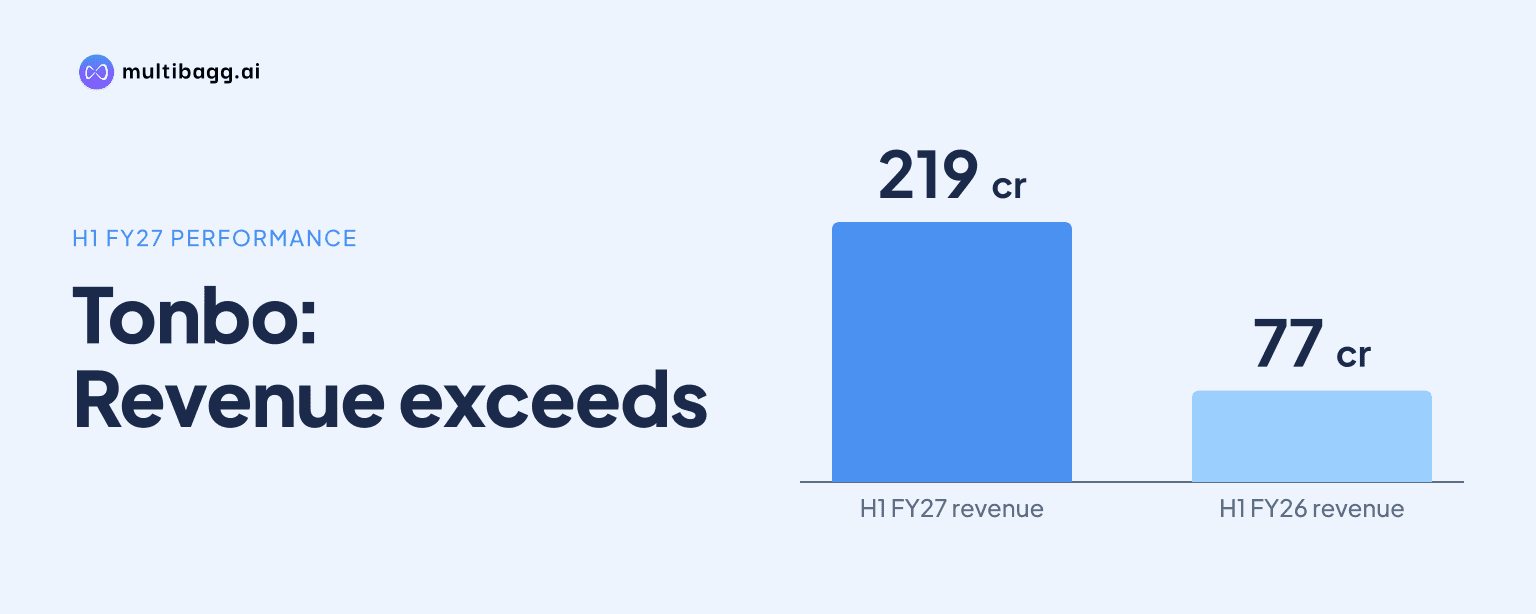
Tonbo Imaging India Limited expects revenue in H2 FY27, the second half of financial year 2027, to materially exceed H1 FY27 sales of Rs 219 crore, management said after a Rs 183 crore second quarter. The expectation is based on a Rs 250 crore order book, Rs 408 crore of contracts under negotiation and potential pipeline conversions over the next two to three months.
Know Tonbo Imaging India inside out
Results, valuation, peers and who's buying, in one view.
Why does Tonbo expect H2 FY27 revenue to exceed H1?
Tonbo expects H2 FY27 revenue to be materially better than H1 FY27 revenue of Rs 219 crore, but management did not issue full-year revenue guidance. Chief Financial Officer Srivatsan Sivashankar said the view was based on the Rs 250 crore order book as of September 2026, contracts under negotiation worth about Rs 408 crore, and tactical and platform opportunities that management hopes will become orders within two to three months.
The expectation also reflects Tonbo's historical revenue-recognition pattern. In FY26, 22% of revenue was recognised in H1 and 78% in H2, according to management. Tonbo said the timing of order receipt and execution can shift revenue between quarters and half-years, so the Rs 408 crore under negotiation should not be treated as confirmed orders.
Tonbo's revenue rose from Rs 36 crore in Q1 FY27 to Rs 183 crore in Q2 FY27, showing the concentration that management says is characteristic of the business. H1 FY27 revenue of Rs 219 crore was also Rs 142 crore above the Rs 77 crore recorded in H1 FY26. The company nevertheless said quarterly and half-yearly measures can be affected by delivery schedules and revenue recognition.
How uneven was Tonbo's H1 FY27 revenue recognition?
Tonbo recorded 84% of its H1 FY27 revenue in Q2, with Rs 183 crore of sales in the quarter out of the Rs 219 crore half-year total. Q1 revenue was Rs 36 crore, leaving the second-quarter figure more than five times the first-quarter level. Management said this pattern was not specific to FY27 and cited the 78% H2 share of FY26 revenue as the relevant prior-year comparison.
The timing effect applies to both tactical and platform systems. Tonbo said tactical systems, which include soldier-carried sights and binoculars, currently contribute about 70% to 80% of its business. Platform systems include gimbals, fire-control systems, weapon stations and seekers, and management expects that segment to represent a larger share over time without providing a revenue target or timetable.
Platform programmes can have longer recognition cycles because deliveries depend on the readiness of associated vehicles, vessels or aircraft. Tonbo said some Indian capital-procurement programmes require more rigorous testing and can take longer, while certain tactical procurement categories could move within a stated six-to-18-month window. These differences mean a contract award or engineering milestone may not immediately become reported revenue.
What did Tonbo report on margins and revenue mix?
Tonbo reported H1 FY27 gross margin of Rs 75 crore, about 87% above Rs 40 crore in H1 FY26, while the gross-margin percentage was 34.62%. Management attributed the percentage being below the 51% recorded in FY26 to product mix. The change shows that the increase in first-half revenue from Rs 77 crore to Rs 219 crore did not produce the FY26 gross-margin percentage.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 31.15 crore in H1 FY27, compared with Rs 11.75 crore in H1 FY26. The H1 EBITDA margin was 14.2%, while Q2 EBITDA was Rs 44 crore at a 24.11% margin. Management said employee costs are largely fixed between quarters and expects higher H2 revenue to improve the full-year EBITDA margin, without setting a margin target.
Exports accounted for about 35% of H1 FY27 revenue and domestic sales made up 65%. On the reported Rs 219 crore of first-half revenue, Tonbo did not provide absolute revenue amounts for either geography. The disclosed mix means domestic sales were the larger contributor during the six months.
Got a follow-up? Ask IRIS
Which orders and markets could shape Tonbo's second half?
Tonbo's Rs 250 crore order book is the primary confirmed-order base cited for its H2 FY27 outlook, while the Rs 408 crore of contracts under negotiation remains subject to conversion. Management said it has pipeline opportunities in both tactical and platform systems and hopes some can become orders within two to three months. No value was assigned to the wider qualified pipeline.
In tactical systems, Tonbo cited stated Indian requirements for around 80,000 thermal weapon sights and hand-held thermal imagers combined, along with approximately 27,000 image-intensifier sights. Management expects procurement activity to continue over the next six to 18 months, although final volumes depend on tenders and contract awards. Internationally, it is pursuing near-term opportunities for about 10,000 thermal sights and monoculars.
Tonbo also said it secured an export order last month from a European state-owned company for initial production units of its multi-sensor stabilised seeker for a loitering-munition programme. The customer has an option to place further orders after acceptance of the initial units. Management presented the programme as an extension of Tonbo's imaging, stabilisation and tracking work into precision-guidance systems.
What could affect Tonbo's ability to deliver a stronger H2?
Tonbo's H2 expectation depends on converting negotiations, executing orders and meeting customer delivery schedules, any of which can move revenue between periods. The company said its Rs 408 crore of contracts under negotiation and pipeline opportunities are not booked revenue. Platform programmes in particular may remain small seed projects until the underlying vehicle, naval or airborne platform enters broader service.
Working-capital funding is another disclosed operating factor. Tonbo had net worth of Rs 564 crore and bank borrowings of about Rs 169 crore as of September 30, 2026, with management describing the borrowings as working-capital funding that is self-liquidating. After that date, one bank increased the company's cash-credit limit to Rs 50 crore from Rs 30 crore, and Tonbo said it was seeking higher limits from its other two banks.
Tonbo is also investing in directed-energy systems over the next three to four years. Its base-strike product is at technology-readiness level four, and it has signed letters of intent for 11 units, including five for the Indian Navy as a minimum order quantity and six for a European customer. Management said directed energy should be viewed as a longer-term option rather than short-term revenue.
Conclusion
Tonbo's Rs 219 crore H1 FY27 revenue, including Rs 183 crore in Q2, supports management's view that the first half is not a smooth run-rate for the year. The company has a Rs 250 crore order book and cited FY26, when 78% of revenue was recognised in H2, to support its expectation of materially higher second-half revenue. At the same time, the 34.62% H1 gross-margin percentage versus 51% in FY26 shows that product mix can affect profitability alongside sales volume.
The next indicators are whether the Rs 408 crore of contracts under negotiation and tactical and platform pipeline produce new orders in the stated two-to-three-month period, and whether those orders can be delivered in H2 FY27. Readers can also track procurement activity across the stated six-to-18-month tactical window, acceptance of the European seeker's initial production units, and progress on the planned three-to-four-year directed-energy investment programme.