










Tonbo Imaging India Q2 Revenue Reaches Rs 183.3 Crore
Key highlights
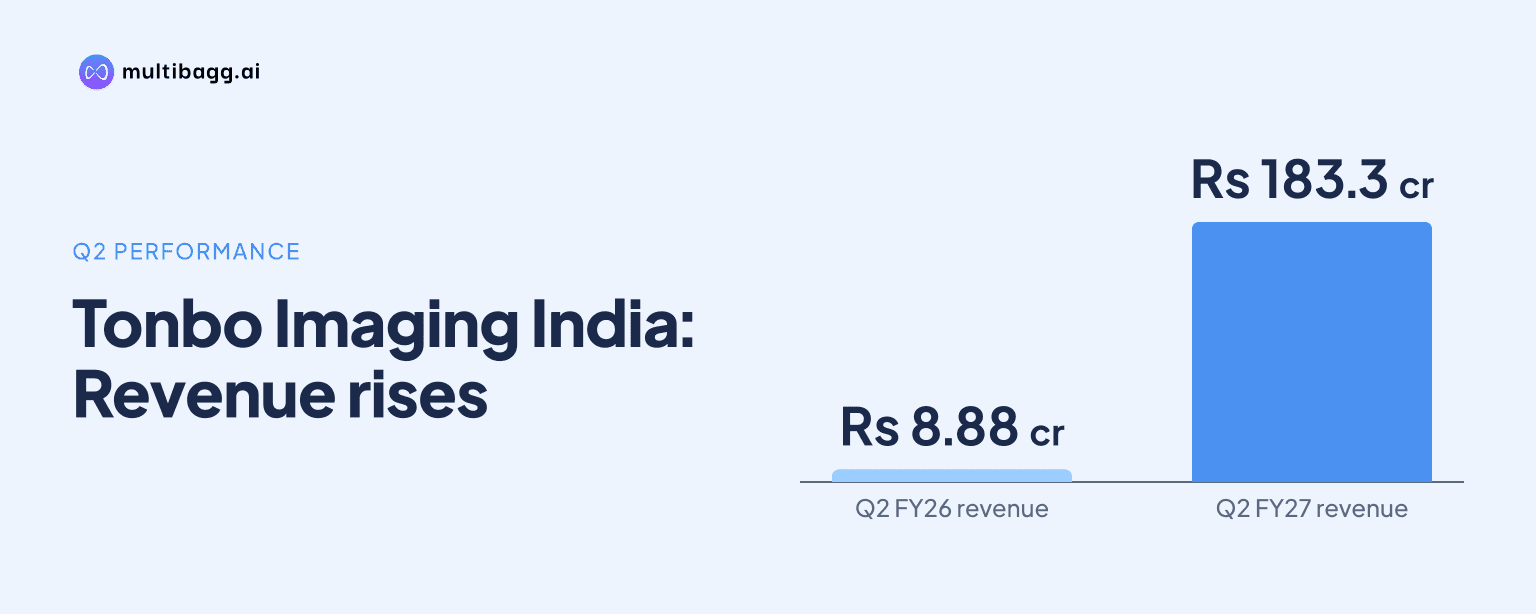
- Tonbo reported Q2 FY27 revenue of Rs 183.29 crore, versus Rs 8.88 crore in Q2 FY26.
- Q2 FY27 net profit was Rs 23.54 crore, compared with a Rs 9.62 crore loss a year earlier.
- H1 FY27 consolidated revenue rose 182.7% year-on-year to Rs 219.30 crore.
- Tonbo reported a Rs 249.8 crore order book and Rs 408.3 crore of contracts under negotiation.
powered by IRIS
Tonbo Imaging India Limited reported Q2 FY27 revenue of Rs 183.29 crore and net profit of Rs 23.54 crore for the quarter ended September 30, 2026, as delayed order receipts and execution that affected Q1 improved during the second quarter. The quarter moved the company to a profitable H1 FY27 after a loss in the corresponding prior period.
Know Tonbo Imaging India inside out
Results, valuation, peers and who's buying, in one view.
What did Tonbo report for Q2 FY27?
Tonbo reported consolidated revenue of Rs 183.29 crore in Q2 FY27, compared with Rs 8.88 crore in Q2 FY26. Consolidated net profit was Rs 23.54 crore, against a net loss of Rs 9.62 crore a year earlier. The company also reported Q2 EBITDA of Rs 44.20 crore, translating into an EBITDA margin of 24.11%.
The Q2 performance followed a subdued first quarter, when delayed receipt and execution of orders affected revenue and profitability. Management said the Q2 execution helped offset the Q1 EBITDA loss of Rs 13.0 crore. As a result, the company generated Rs 31.2 crore of EBITDA for the first half of FY27.
The earnings call for the quarter and half year ended September 30, 2026, was held on November 6, 2026. Tonbo subsequently made the audio recording of the analyst and investor call available on its website. The call lasted about 70 minutes and included questions from six analysts, according to the available event summary.
How did the first-half financial performance change?
Tonbo's consolidated H1 FY27 revenue rose 182.7% year-on-year to Rs 219.30 crore. Net profit for the half year was Rs 5.80 crore, compared with a net loss of Rs 4.19 crore in H1 FY26. This shift reflected the substantially stronger second quarter after the execution delays in Q1.
The financial split between the two quarters highlights the uneven nature of the company's project-led business. Q2 revenue of Rs 183.29 crore represented most of H1 revenue, while Q2 EBITDA of Rs 44.20 crore more than offset the loss recorded in the first quarter. Management described quarterly execution as lumpy, meaning revenue recognition can depend materially on timing of order receipts, deliveries and project execution.
H1 gross profit stood at Rs 75.9 crore. Exports accounted for 35% of H1 revenue, while domestic sales contributed 65%. The mix indicates that India remained the larger revenue market during the six-month period, even as exports formed a material part of the business.
What supports Tonbo's H2 FY27 outlook?
Tonbo said H2 FY27 revenue is expected to be materially higher than H1, supported by its existing order book, contracts under negotiation and opportunities that could convert over the next two to three months. Management did not provide a quantified revenue target or margin guidance for FY27.
As of September 30, 2026, the company had an order book of Rs 249.8 crore. It also had contracts worth Rs 408.3 crore under negotiation. These figures indicate the scale of identified business opportunities, but contracts under negotiation are not confirmed revenue and their conversion, timing and execution remain relevant variables.
Tactical systems remained Tonbo's largest business during the period. Management also referred to platform systems and directed-energy development as areas intended to broaden its growth over time. The company did not disclose separate revenue contributions for these activities in the available earnings summary.
Got a follow-up? Ask IRIS
Why are the quarterly results important for investors?
The Q2 numbers show how strongly Tonbo's reported performance can change when delayed orders move into execution. Revenue increased from Rs 8.88 crore in Q2 FY26 to Rs 183.29 crore in Q2 FY27, while the company moved from a quarterly loss to a Rs 23.54 crore profit. For investors, the result also underlines that a single quarter may not represent a smooth run rate in a business with project-linked deliveries.
The order book and contract negotiations are relevant because management has linked the expectation of a stronger H2 to these opportunities. However, Tonbo has not provided formal full-year revenue or margin guidance. Investors therefore have confirmed information on the order pipeline and management's directional commentary, but not a specific FY27 financial target against which performance can be measured.
The export share of 35% also shows that the company has exposure beyond the domestic market, while domestic sales remain the majority of revenue. The available disclosures do not provide a geographic breakup of exports or identify individual customers, so the reported sales mix should be assessed alongside future disclosures on order conversion and execution.
What should investors monitor after the Q2 update?
The central issue after the Q2 update is execution. Tonbo has reported a strong recovery from the first quarter, but management has also said quarterly revenue can be lumpy. The pace at which the Rs 249.8 crore order book is executed, and whether contracts worth Rs 408.3 crore progress from negotiation to confirmed orders, will shape the visibility available for the second half.
Investors may also track whether the company provides further detail on tactical systems, platform systems and directed-energy development, including their commercial contribution. Tonbo's recorded November 6 earnings call is available for shareholders seeking management's discussion of the quarter and half-year results.
Conclusion
Tonbo's Q2 FY27 results marked a significant improvement in reported revenue and profitability, with revenue of Rs 183.29 crore, EBITDA of Rs 44.20 crore and net profit of Rs 23.54 crore. The quarter enabled the company to report H1 revenue of Rs 219.30 crore and a net profit of Rs 5.80 crore after a loss in H1 FY26.
The next focus is H2 execution. Management expects H2 revenue to be materially higher than H1, but has not issued quantified revenue or margin guidance. Progress in converting the Rs 408.3 crore of negotiated contracts and executing the Rs 249.8 crore order book will be the key disclosed factors to monitor.