










UFlex targets 50% value-added share of sales by FY29 from 30%
Key highlights
- UFlex targets value-added products at 50% of total sales by FY29, versus almost 30% currently.
- UFlex said 60% of aseptic packaging sales occur in Q4 and Q1.
- UFlex put overall capacity utilisation at around 80% and targets around 90% in the next year.
- UFlex expects most of its Rs 2,000 crore March 2027 CWIP to become assets by FY28.
powered by IRIS
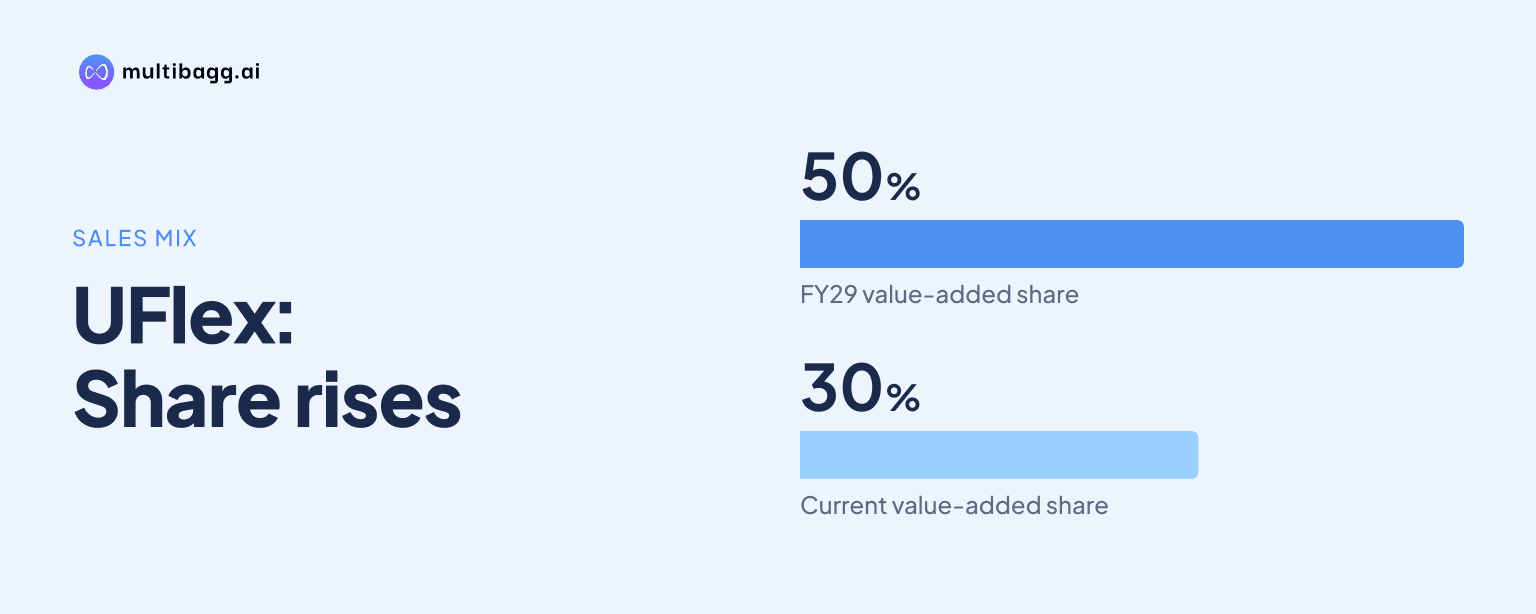
UFlex Limited aims to lift value-added products from almost 30% of total sales currently to 50% by FY29, a three-year internal vision led by aseptic packaging. Management said the mix change, alongside capacity additions and higher utilisation, is intended to maintain and improve margins over the next three to five years.
Know Uflex inside out
Results, valuation, peers and who's buying, in one view.
What is UFlex targeting for value-added sales by FY29?
UFlex is targeting a 50% value-added share of total sales by FY29, compared with almost 30% currently. Management described the 20-percentage-point increase as an internal vision for the next three years and said the portfolio should support margins over a sustained three-to-five-year period.
The target concerns sales mix rather than an absolute revenue forecast. UFlex did not disclose current revenue from value-added products or their standalone earnings before interest, tax, depreciation and amortisation, or EBITDA, margin, but management said these products generate healthy EBITDA margins and will receive additional capacity investment.
The planned mix shift comes as management distinguishes value growth from volume growth. UFlex said sales volume grew by around 2% in H1 FY27 and it expected growth in the same vicinity in H2 FY27. Management clarified that its earlier 30% expectation referred to top-line and EBITDA growth, rather than a 30% increase in volume.
Which products will increase UFlex's value-added sales mix?
UFlex identifies aseptic packaging, packaging cylinders, chemicals and holography as value-added product lines. Management said aseptic packaging will be a major future component, while its engineering division installs packaging machinery at customer premises for formats including 100 millilitre, 200 millilitre and 400 millilitre packs.
Aseptic packaging is central to the FY29 objective because UFlex has expanded the product in India and is setting up a new line in Egypt. Management said aseptic packaging can extend product life, improve appearance and has become less costly to manufacture, while more companies are requesting this packaging format.
The aseptic business also has a pronounced seasonal pattern. Management said 60% of aseptic sales occur in Q4 and Q1, with the remaining 40% in the other two quarters. Winter consumption of juices and related products is lower, meaning quarterly aseptic sales can vary materially even if the business is progressing toward the FY29 mix target.
UFlex's manufacturing chain spans chemical inks and adhesives, holography, printing cylinders, flexible packaging, aseptic packaging and engineering. Management said the chain begins with polyethylene terephthalate, or PET, chips and ends with final packaging material, while internally produced cylinders and chemicals support the packaging process.
Got a follow-up? Ask IRIS
How will new capacity support UFlex's FY29 plan?
UFlex expects its aseptic project to be capitalised in H2 FY27 and its Dharwad plant in H1 FY28. Management said most of the Rs 2,000 crore of capital work in progress, or CWIP, expected to be outstanding by March 2027 would be translated into fixed assets through these two projects by FY28.
The project timing links the current investment cycle to FY28 and FY29 growth. Management said capacities being commercialised at the end of FY27 or the beginning of FY28 should support growth in those later periods, while the Egypt aseptic line and Indian expansion are directly connected to the value-added product strategy.
UFlex also linked profitability to capacity use across geographies. Management put overall utilisation at around 80% and set an objective of around 90% in the next year. Its explanation was that fixed costs are already covered at higher utilisation, allowing incremental output to improve margins.
Management did not disclose investment by project, output capacity, sales contribution or a separate margin target for either the aseptic line or Dharwad. The disclosed operating milestones are instead aseptic capitalisation in H2 FY27, Dharwad capitalisation in H1 FY28, and a subsequent contribution from new assets to FY28 and FY29 growth.
What do UFlex's margins and utilisation targets indicate?
UFlex said its blended EBITDA margin across overseas and Indian operations is in the 14% to 15% range. Management said overseas margins exceed domestic margins because overseas price realisation is higher, and indicated that around 60% of the blended margin is driven by overseas operations.
Management called the 14% to 15% blended range sustainable and said it seeks improvement over the long term. It cited specialised plants in Egypt and Mexico and recycled PET chips among investments intended to improve margins, while the 80%-to-90% utilisation objective is another stated operating lever.
The company also cited tax-efficient locations as part of its operating model. Management named trade zones in Egypt, Mexico and Nigeria, and Indian locations including Jammu, Sanand and Dharwad, and said these arrangements result in a tax payout below the maximum rate of around 30% it cited.
Management said almost 30% to 40% of EBITDA flows into net profit because of this tax positioning. That is management's explanation of the integrated footprint rather than an earnings forecast; the quantified strategic objective remains moving value-added products from almost 30% of sales to 50% by FY29.
Conclusion
UFlex has set a measurable sales-mix objective: value-added products are to reach 50% of total sales by FY29 from almost 30% currently. Aseptic packaging is the principal named driver, supported by cylinders, chemicals, holography and engineering capabilities across the company's PET-chip-to-packaging chain.
The next milestones are aseptic project capitalisation in H2 FY27 and Dharwad in H1 FY28, with most of the Rs 2,000 crore March 2027 CWIP expected to become assets by FY28. Management's target to raise utilisation from around 80% to around 90%, together with aseptic sales concentration of 60% in Q4 and Q1, will indicate how the plan is developing.