










Windlas Biotech CDMO rose 32% as trade revenue fell 31%
Key highlights
- Generic Formulations CDMO revenue rose 32% to Rs. 422 crore in H1FY27.
- Trade Generics & Institutional revenue fell 31% to Rs. 66 crore in H1FY27.
- CDMO increased to 82% of H1FY27 revenue mix from 74% in H1FY26.
- Net revenue from operations grew 18% to Rs. 512 crore and adjusted PAT rose 33% to Rs. 50 crore in H1FY27.
powered by IRIS
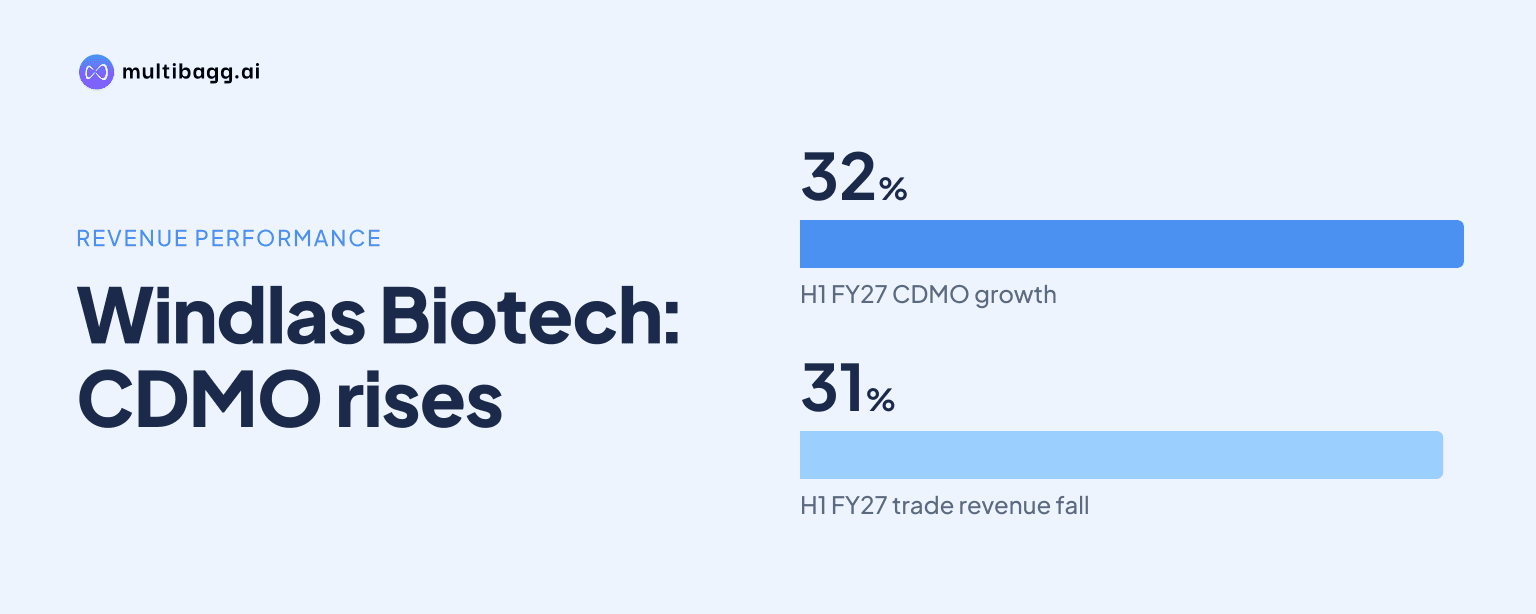
Windlas Biotech shifted its H1FY27 revenue mix toward Generic Formulations CDMO, where revenue rose 32% year on year to Rs. 422 crore, while Trade Generics & Institutional revenue fell 31% to Rs. 66 crore. CDMO represented 82% of the three reported verticals, up from 74% in H1FY26.
Know Windlas Biotech inside out
Results, valuation, peers and who's buying, in one view.
Why did Windlas' revenue mix change in H1FY27?
Windlas' mix changed because CDMO added Rs. 101 crore of H1FY27 revenue while Trade Generics & Institutional lost Rs. 30 crore, and exports added Rs. 7 crore. Generic Formulations CDMO, or contract development and manufacturing organisation, rose to Rs. 422 crore from Rs. 321 crore in H1FY26. Its contribution increased by 8 percentage points to 82% of the reported three-vertical mix.
Management said customers entrusted Windlas with a larger share of their portfolios and new products in the CDMO business. That mechanism coincided with 32% H1FY27 growth and a 34% rise in Q2FY27 CDMO revenue to Rs. 215 crore from Rs. 160 crore a year earlier. By contrast, Trade Generics & Institutional fell to 13% of mix from 22%, a 9-percentage-point reduction.
The reported vertical amounts sum to Rs. 511 crore in H1FY27 and Rs. 433 crore in H1FY26. Windlas reported net revenue from operations of Rs. 512 crore for H1FY27, up 18% from Rs. 432 crore, with the presentation reporting the segment figures and company total separately.
How did Windlas' three businesses perform during the half year?
Windlas' CDMO and export businesses grew in H1FY27, whereas Trade Generics & Institutional contracted. CDMO revenue reached Rs. 422 crore, exports reached Rs. 23 crore and Trade Generics & Institutional generated Rs. 66 crore. Exports grew at the fastest reported rate, 46%, but remained 5% of the H1FY27 revenue mix, compared with CDMO's 82%.
Management attributed the Trade Generics & Institutional decline to a portfolio reshaping process that replaced codeine-based products with new launches. The vertical produced Rs. 36 crore in Q2FY27, down 30% from Rs. 52 crore in Q2FY26, following the 31% half-year decline. Management said the replacement launches were intended to give the business a broader and more resilient base, but it did not disclose a timeline or revenue target for that process.
Export revenue rose Rs. 7 crore year on year in H1FY27 and Rs. 2 crore in Q2FY27, when it reached Rs. 12 crore. Management described export markets as having longer lead times and said it continued to invest in dossiers, product registrations and site approvals. A few of those activities had turned into commercial supplies, according to management, which linked that conversion to the 26% quarterly and 46% half-year export growth.
Got a follow-up? Ask IRIS
Did Windlas sustain the shift in the second quarter?
Windlas sustained the CDMO-led mix shift in Q2FY27, with CDMO increasing 34% to Rs. 215 crore while Trade Generics & Institutional declined 30% to Rs. 36 crore. Exports rose 26% to Rs. 12 crore. The quarterly pattern broadly matched the half-year outcome: the largest vertical grew faster than total company revenue, while the domestic trade and institutional vertical remained lower year on year.
Total Q2FY27 net revenue from operations was Rs. 264 crore, up 19% from Rs. 222 crore in Q2FY26, marking Windlas' 15th consecutive quarter of record revenue according to the presentation. CDMO's Rs. 55 crore quarterly increase exceeded the Rs. 42 crore increase in reported company revenue, while the Rs. 16 crore Trade Generics & Institutional reduction partly offset CDMO and export expansion.
The comparison also shows a difference in scale between the growth drivers. CDMO accounted for Rs. 215 crore of the Rs. 264 crore Q2FY27 revenue total, whereas exports accounted for Rs. 12 crore despite their 26% rate of growth. Windlas' stated manufacturing base includes five World Health Organization Good Manufacturing Practices-compliant plants and tablet and capsule capacity of 8,522 million units, providing context for its larger CDMO business.
What did the revenue shift mean for Windlas' earnings?
Windlas reported higher adjusted earnings in H1FY27 alongside the 18% revenue increase, although reported margins were affected by non-cash employee stock option plan expenses. Adjusted earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 23% to Rs. 70 crore and its margin increased to 13.7% from 13.2%. Adjusted profit after tax, or PAT, rose 33% to Rs. 50 crore, with margin reaching 9.7% from 8.6%.
Reported H1FY27 EBITDA was Rs. 56 crore, only 2% above Rs. 55 crore in H1FY26, and the reported EBITDA margin declined to 10.9% from 12.7%. Reported PAT was Rs. 36 crore versus Rs. 35 crore, with its margin declining to 7.0% from 8.2%. The presentation attributes the distinction between adjusted and reported figures to Rs. 14.06 crore of non-cash ESOP expense in H1FY27, compared with Rs. 1.9 crore in H1FY26.
Windlas recorded adjusted gross profit of Rs. 197 crore in H1FY27 against Rs. 166 crore a year earlier, while gross margin rose 12 basis points to 38.5%. In Q2FY27, adjusted EBITDA was Rs. 36 crore and adjusted PAT was Rs. 25 crore, compared with Rs. 30 crore and Rs. 19 crore respectively in Q2FY26. These figures show increased adjusted profit alongside a mix more concentrated in CDMO, without attributing the margin movement solely to any individual vertical.
Conclusion
Windlas entered H1FY27 with a more CDMO-concentrated business mix: CDMO rose from 74% to 82% of reported vertical revenue, while Trade Generics & Institutional declined from 22% to 13%. Export revenue expanded 46% to Rs. 23 crore but remained a 5% contributor. At company level, net revenue rose 18% to Rs. 512 crore and adjusted PAT increased 33% to Rs. 50 crore.
The next items to watch are the pace of the Trade Generics & Institutional portfolio replacement, the conversion of export dossiers, registrations and site approvals into commercial supplies, and the operational contribution from Plant-6. Management said Plant-6 was commercialised in September 2026, while Plant-4 and Plant-5 received European Union Good Manufacturing Practices certification during Q2FY27 as part of the long-term export strategy.