










Windlas ESOP expense held H1 FY27 reported PAT growth to 1%
Key highlights
- Windlas reported H1FY27 revenue of Rs 512 crore, up 18% from Rs 432 crore in H1FY26.
- Windlas’s PAT excluding ESOP expense rose 33% to Rs 50 crore, while reported PAT rose 1% to Rs 36 crore.
- Windlas recorded Rs 14.06 crore of non-cash ESOP expense in H1FY27, compared with Rs 1.94 crore in H1FY26.
- Windlas schedules Rs 8.08 crore of non-cash ESOP expense in FY 2026-27 H2.
powered by IRIS
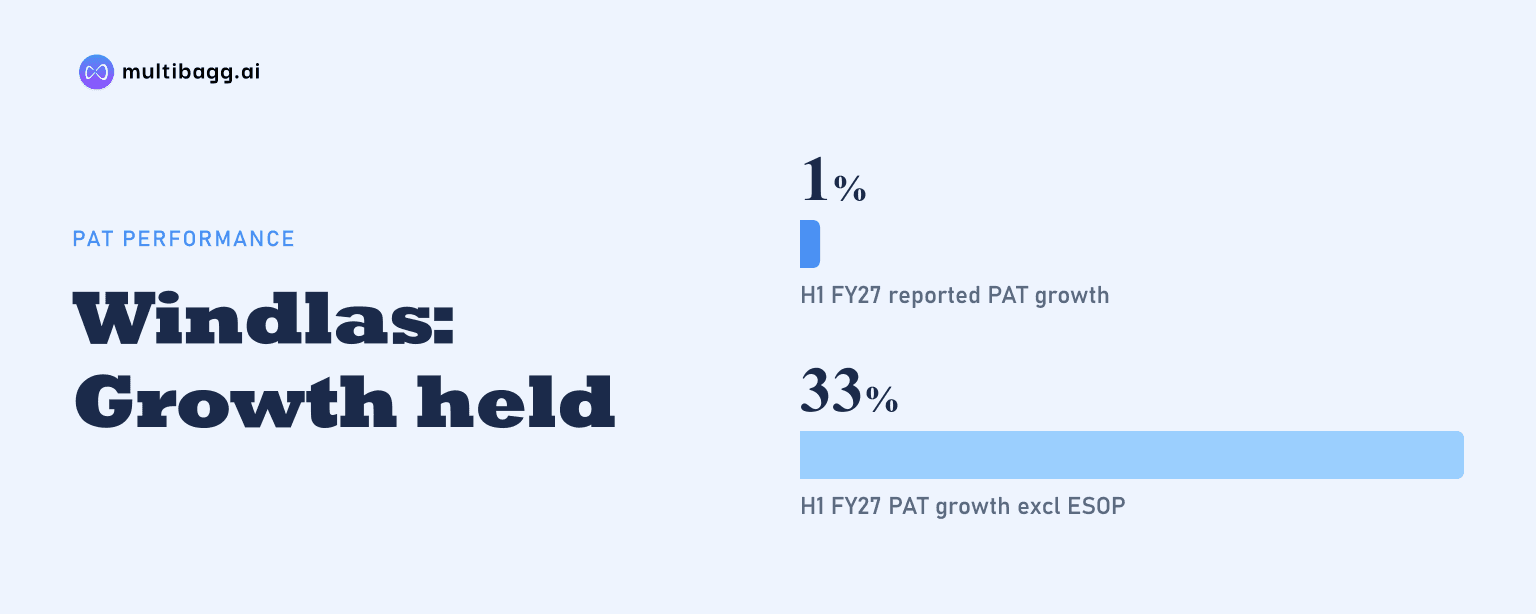
Windlas reported profit after tax growth of 1% to Rs 36 crore in H1FY27, while profit after tax excluding a Rs 14.06 crore non-cash employee stock option plan charge rose 33% to Rs 50 crore. Revenue increased 18% to Rs 512 crore, but the larger ESOP expense reduced reported margins.
Know Windlas Biotech inside out
Results, valuation, peers and who's buying, in one view.
Why did Windlas’s reported H1FY27 PAT grow only 1%?
Windlas’s reported profit after tax, or PAT, increased 1% to Rs 36 crore in H1FY27 from Rs 35 crore in H1FY26 because ESOP expense rose to Rs 14.06 crore from Rs 1.94 crore. Windlas describes the ESOP charge as a non-cash expense in its profit and loss account that does not affect operating cash flows.
PAT excluding ESOP expense rose by Rs 13 crore to Rs 50 crore from Rs 37 crore, equivalent to 33% growth. The difference between adjusted and reported H1FY27 PAT is consistent with the Rs 14.06 crore charge, subject to rounding in the presentation’s reported profit figures.
The impact also appeared before tax. Reported profit before tax declined 1% to Rs 46 crore in H1FY27 from Rs 47 crore, whereas profit before tax excluding ESOP expense increased 24% to Rs 60 crore from Rs 49 crore. Taxes were Rs 11 crore in both periods, leaving the change in ESOP expense as the stated difference between the adjusted and reported profit trends.
How did the ESOP expense affect Windlas’s margins?
Windlas’s reported PAT margin declined to 7.0% in H1FY27 from 8.2% in H1FY26, while PAT margin excluding ESOP expense increased to 9.7% from 8.6%. The reported margin was therefore 2.7 percentage points below the adjusted margin in H1FY27.
Reported earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 2% to Rs 56 crore from Rs 55 crore, while its margin fell to 10.9% from 12.7%. EBITDA excluding ESOP expense increased 23% to Rs 70 crore from Rs 57 crore, and its margin rose 51 basis points, or bps, to 13.7% from 13.2%.
The Q2FY27 figures showed the same split. EBITDA excluding ESOP expense increased 20% to Rs 36 crore and PAT excluding ESOP expense rose 29% to Rs 25 crore, while reported EBITDA and PAT were Rs 29 crore and Rs 18 crore respectively. The Q2FY27 ESOP expense was Rs 6.90 crore, compared with the Rs 2 crore rounded charge shown for Q2FY26 in the profit and loss table.
Gross profit rose 19% to Rs 197 crore in H1FY27 from Rs 166 crore, and gross margin increased 12 bps to 38.5%. Employee expenses excluding ESOPs increased to Rs 78 crore from Rs 67 crore, while other expenses rose to Rs 49 crore from Rs 42 crore; Windlas separately identifies ESOP expense as the item reconciling adjusted and reported EBITDA.
Got a follow-up? Ask IRIS
Did Windlas’s operations improve before ESOP charges?
Windlas’s operating results improved before ESOP charges, with H1FY27 revenue rising 18% to Rs 512 crore and EBITDA excluding ESOP expense increasing 23% to Rs 70 crore. The associated EBITDA margin rose to 13.7% from 13.2%, while adjusted PAT margin increased 107 bps to 9.7%.
Generic Formulations contract development and manufacturing organisation, or CDMO, revenue rose 32% to Rs 422 crore in H1FY27 from Rs 321 crore in H1FY26. Its share of revenue increased to 82% from 74%, while Trade Generics and Institutional revenue fell 31% to Rs 66 crore from Rs 96 crore and its mix fell to 13% from 22%.
Exports increased 46% to Rs 23 crore from Rs 16 crore, taking their revenue mix to 5% from 4%. The Rs 80 crore increase in total revenue therefore coincided with a larger contribution from Generic Formulations CDMO, even as the separate ESOP accounting expense constrained reported profit growth.
Cash-flow data also distinguish the non-cash charge from cash generation. Operating profit before working-capital changes increased to Rs 70 crore in September 2026 from Rs 58 crore in September 2025, but net cash from operating activities was Rs 53 crore versus Rs 56 crore after a Rs 9 crore working-capital outflow and Rs 8 crore of direct taxes paid.
What ESOP expense does Windlas expect after H1FY27?
Windlas expects non-cash ESOP expense of Rs 8.08 crore in FY 2026-27 H2, below the Rs 14.06 crore recorded in FY 2026-27 H1. Its schedule then lists Rs 7.63 crore in FY 2027-28 H1 and Rs 4.26 crore in FY 2027-28 H2.
ESOP Plan 2025 contributed Rs 13.74 crore of the Rs 14.06 crore total in FY 2026-27 H1, while ESOS Plan 2023 contributed Rs 0.32 crore. For FY 2026-27 H2, Windlas schedules Rs 7.73 crore for ESOP Plan 2025 and Rs 0.35 crore for ESOS Plan 2023, making the 2025 plan the main source of both the recorded and expected expense.
The schedule declines further to Rs 3.96 crore in FY 2028-29 H1, Rs 1.84 crore in FY 2028-29 H2, Rs 1.64 crore in FY 2029-30 H1 and Rs 0.07 crore in FY 2029-30 H2. Windlas says the projections assume all granted options vest and may change slightly with lapsed options or further grants.
The charge has not declined in a straight line historically. Total actual expense was Rs 1.94 crore in FY 2025-26 H1, increased to Rs 14.68 crore in FY 2025-26 H2, and was Rs 14.06 crore in FY 2026-27 H1. Windlas also says changes in share price after grant do not alter the expense for options already granted.
Conclusion
Windlas’s H1FY27 results show higher revenue and profit before the ESOP charge alongside limited reported PAT growth. Revenue increased by Rs 80 crore to Rs 512 crore, EBITDA excluding ESOP expense increased by Rs 13 crore to Rs 70 crore, and PAT excluding ESOP expense increased by Rs 13 crore to Rs 50 crore, while reported PAT was Rs 36 crore.
The next disclosed item to watch is the Rs 8.08 crore ESOP expense scheduled for FY 2026-27 H2, compared with Rs 14.06 crore in FY 2026-27 H1. Windlas notes that the projected amounts can change if options lapse or it makes further grants, even though its schedule assumes all currently granted options vest.