










Windlas Biotech Limited Q2 revenue rises 19% to ₹264 crore
Key highlights
- Windlas Biotech reported Q2 FY27 revenue of ₹264 crore, up 19% year on year.
- H1 FY27 revenue reached ₹512 crore, up 18% year on year and above the ₹500 crore mark for the first time.
- Reported Q2 FY27 EBITDA was ₹29 crore, while EBITDA excluding ESOP expenses was ₹36 crore.
- Plant 6 was commercialised in September 2026, and Plants 4 and 5 received EU GMP certification.
powered by IRIS
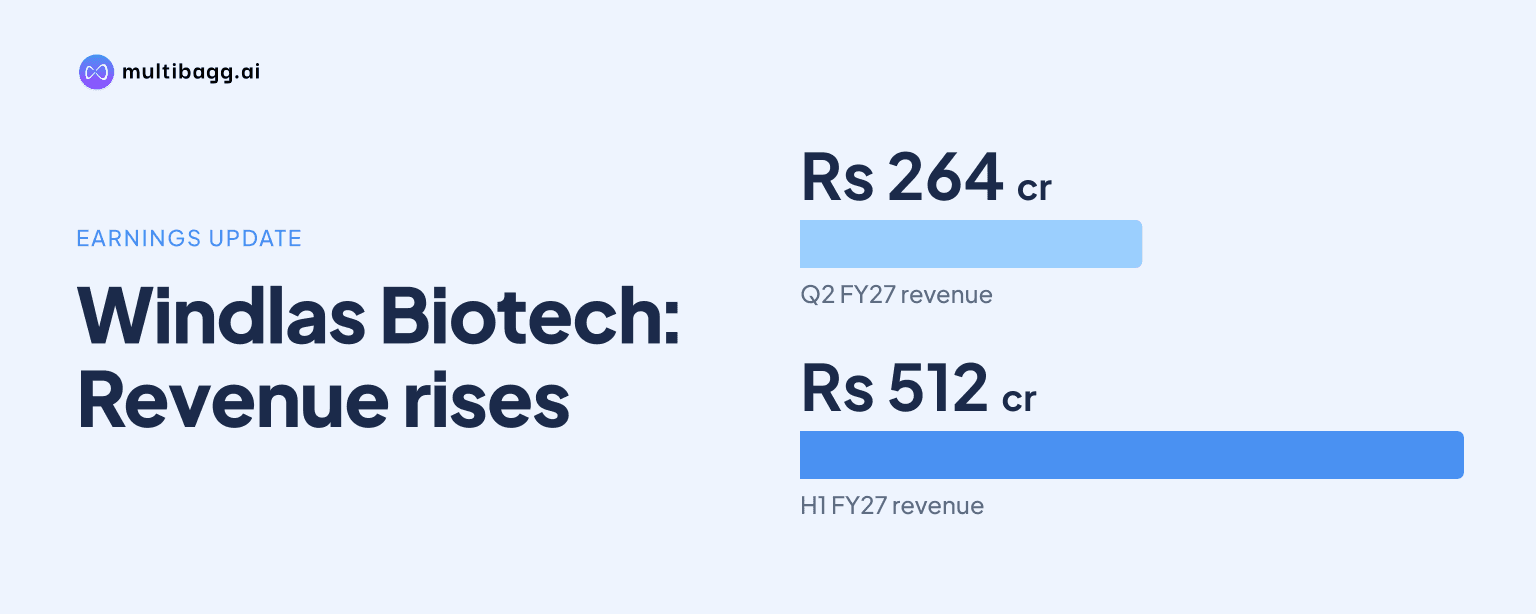
Windlas Biotech Limited reported Q2 FY27 revenue of ₹264 crore, up 19% year on year, extending its record-revenue run to 15 consecutive quarters as generic formulation CDMO demand increased. For the half year ended September 30, 2026, revenue reached ₹512 crore, while the company commercialised Plant 6 and received EU GMP certification for Plants 4 and 5.
Know Windlas Biotech inside out
Results, valuation, peers and who's buying, in one view.
How did Windlas Biotech perform in Q2 and H1 FY27?
Windlas Biotech recorded revenue of ₹264 crore in Q2 FY27, a 19% year-on-year increase, and ₹512 crore in H1 FY27, up 18% year on year. The half-year revenue figure marked the first time the company crossed ₹500 crore in revenue for a six-month period. Management said the quarterly result continued a streak of 15 consecutive record-revenue quarters.
Reported EBITDA was ₹29 crore in the quarter and ₹56 crore for the first half. Reported profit after tax was ₹18 crore in Q2 FY27 and ₹36 crore in H1 FY27. Excluding non-cash ESOP expenses, Q2 EBITDA was ₹36 crore, with a margin of 13.7%, while adjusted PAT was ₹25 crore, or 9.5% of revenue. For H1, adjusted EBITDA was ₹70 crore, also at a 13.7% margin, and adjusted PAT was ₹50 crore, or 9.7% of revenue.
What drove Windlas Biotech's revenue growth?
Windlas Biotech said generic formulation CDMO remained its anchor business and was the main driver of the quarter's growth. The company stated that customers gave it a larger share of their portfolios and additional new products, supporting the rise in Q2 and H1 revenue.
The generic formulation CDMO vertical generated ₹36 crore of revenue in Q2 FY27 and ₹66 crore in H1 FY27. The company also noted that the Indian pharmaceutical market reported volume growth of 2.3% during the quarter. Windlas Biotech's 19% quarterly revenue growth was therefore materially higher than that market volume-growth figure, although the measures are not directly comparable because company revenue can also reflect product mix and customer additions.
Management's commentary indicated that its operating approach is centred on building capacity organically rather than pursuing acquisitions quickly. The stated objective is to preserve operational efficiency and maintain disciplined capital allocation as the business expands.
What does Plant 6 commercialisation mean for Windlas Biotech?
Windlas Biotech commercialised Plant 6 in September 2026, adding a new operating facility to its manufacturing network. Management said the plant's costs and depreciation would begin to flow through the financial statements from Q3 FY27, following its commercialisation.
The company did not provide a revenue contribution from Plant 6 during the call. Its immediate financial relevance is therefore the addition of operating and depreciation costs from the December quarter, alongside the capacity that the facility is intended to provide. Investors will need subsequent disclosures to assess utilisation, customer onboarding and the plant's contribution to sales.
The company also received EU GMP certification for Plants 4 and 5. Management presented this certification as a step that positions these plants for future export expansion. EU GMP certification is relevant for manufacturing facilities seeking to serve regulated export markets, but Windlas Biotech did not disclose specific export orders, customers or revenue targets linked to the approval.
Got a follow-up? Ask IRIS
Why do the results and capacity additions matter to investors?
The result shows continued revenue growth alongside a higher capacity base. Windlas Biotech's reported Q2 EBITDA of ₹29 crore was lower than the ₹36 crore figure excluding ESOP expenses, making the treatment of non-cash ESOP costs important when comparing reported and adjusted profitability.
The H1 performance provides a broader view of the business than a single quarter. Revenue of ₹512 crore, reported EBITDA of ₹56 crore and reported PAT of ₹36 crore indicate that the company sustained profitability through the first six months of FY27. The adjusted H1 figures of ₹70 crore EBITDA and ₹50 crore PAT show the stated impact of ESOP expenses on the reported numbers.
For the broader pharmaceutical manufacturing industry, the update reflects the importance of customer relationships, product development and compliant capacity. Windlas Biotech said activities such as clinical trials, bioequivalence studies and new formulation development are classified as new drugs by the Indian regulator. These development activities form part of the regulatory and operational work involved in supplying pharmaceutical products.
What should investors monitor after the Q2 FY27 update?
Investors should monitor the financial effect of Plant 6 as its costs and depreciation enter results from Q3 FY27. The facility's revenue ramp-up was not quantified in the available management commentary, so future quarterly disclosures will be important for evaluating capacity utilisation and operating leverage.
They should also track progress from the EU GMP-certified Plants 4 and 5, particularly any disclosed export business, as well as the CDMO segment's contribution to growth. Windlas Biotech's focus on organic expansion rather than rushed acquisitions means execution at its existing and newly commercialised facilities remains central to its stated long-term plan.
Conclusion
Windlas Biotech delivered Q2 FY27 revenue of ₹264 crore, up 19% year on year, and crossed ₹500 crore in H1 revenue for the first time at ₹512 crore. The result was supported by generic formulation CDMO demand, while reported profitability was affected by non-cash ESOP expenses relative to the adjusted figures shared by management.
The next disclosed operating milestone is the inclusion of Plant 6 costs and depreciation from Q3 FY27. Investors will also watch for updates on Plant 6 utilisation, the export opportunity from EU GMP-certified Plants 4 and 5, and continued growth in the generic formulation CDMO business.