










Amber Enterprises India Cuts FY27 Growth Outlook to 15-20%
Key highlights
- Amber Enterprises India reported Q2 FY27 revenue of ₹2,627 crore, up 60% year-on-year.
- H1 FY27 revenue increased 28% to ₹6,515 crore and operating EBITDA rose 29% to ₹464 crore.
- FY27 revenue-growth guidance was lowered to 15-20% amid commodity, currency and wage pressures.
- Amber Enterprises India plans annual capital expenditure of ₹1,800-2,000 crore and targets 14-16% durables EBITDA margin by FY29.
powered by IRIS
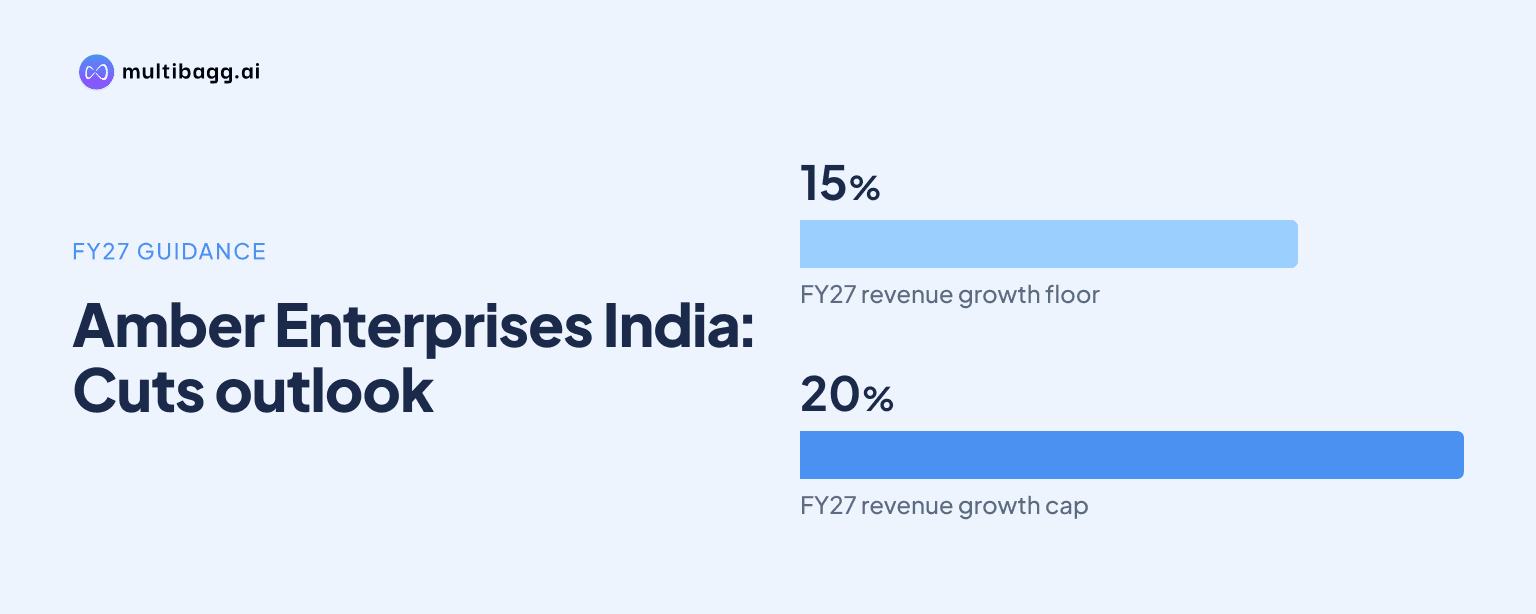
Amber Enterprises India Limited reported Q2 FY27 revenue growth of 60% year-on-year to ₹2,627 crore, while lowering its FY27 revenue-growth guidance to 15-20% as commodity costs, wage increases and production ramp-up pressures weighed on margins.
Know Amber Enterprises India inside out
Results, valuation, peers and who's buying, in one view.
Why did Amber Enterprises India lower its FY27 growth outlook?
Amber Enterprises India lowered its FY27 revenue-growth guidance to 15-20% despite reporting strong quarterly revenue growth. The company had a 60% year-on-year rise in consolidated Q2 revenue, but management indicated that cost pressures were affecting profitability and the outlook for the full year.
The key pressures cited were commodities, currency-related costs and wage hikes. These factors affected margins during the quarter even as revenue increased. The company also referred to ramp-up pressures, which can arise when new operations or businesses are being scaled and absorption of fixed costs is still developing.
The revised outlook matters because it separates the strong reported growth in the September quarter from management's expectations for the remaining part of FY27. It indicates that the pace of revenue expansion recorded in Q2 is not being used as the basis for the full-year forecast.
What were Amber Enterprises India's Q2 and H1 FY27 financial results?
Amber Enterprises India reported consolidated Q2 FY27 revenue of ₹2,627 crore, compared with ₹1,647 crore a year earlier, representing growth of about 60%. Operating EBITDA for the quarter rose to ₹127 crore from ₹98 crore, a 30% year-on-year increase.
However, the increase in operating profit was slower than the increase in revenue. The quarterly operating EBITDA included a ₹13.5 crore inventory purchase-price-allocation adjustment. The company reported a consolidated net loss of ₹66.4 crore for Q2 FY27. Call-related summaries also referred to an adjusted loss after tax of ₹57 crore before a ₹9.5 crore exceptional loss.
For the first half of FY27, consolidated revenue increased 28% year-on-year to ₹6,515 crore from ₹5,096 crore. Operating EBITDA rose 29% to ₹464 crore from ₹361 crore. Group Chief Financial Officer Sudhir Goyal said the operating EBITDA measure was before ESOP expenses and other non-operating income and expenses.
Which businesses supported the quarterly revenue increase?
Amber Enterprises India said its electronics business grew 94% year-on-year in Q2, while the durables business grew 41%. These growth rates point to contributions from more than one operating segment during the quarter, rather than a single-business increase.
The company is also working to simplify its group structure. During the quarter, IL JIN acquired the remaining 40% stake in Power-One and a 1.5% stake in Ascent Circuits through the issuance of compulsorily convertible preference shares under a share-swap arrangement.
This transaction was disclosed by Executive Chairman, Chief Executive Officer and Whole-Time Director Jasbir Singh during the earnings call. The call was attended by Managing Director Daljit Singh, Whole-Time Director Sachin Gupta, Group CFO Sudhir Goyal and President of New Businesses Sanjay Arora.
The operating update shows a company balancing expansion in electronics and durables with the execution requirements of integrating and scaling businesses. The reported revenue performance was strong, but the margin commentary makes cost management a central issue for investors assessing the quality of that growth.
Got a follow-up? Ask IRIS
What is Amber Enterprises India's margin and investment plan?
Amber Enterprises India expects its durables EBITDA margin to normalise at 14-16% by FY29. The target provides a longer-term reference point, while management's FY27 comments show that margins are currently facing commodity, currency, wage and ramp-up pressures.
The company has also outlined annual capital expenditure of ₹1,800-2,000 crore. Such spending indicates continued investment across its operations and new businesses, but it also makes capital allocation and execution important considerations as the company pursues growth.
The FY29 margin normalisation target does not indicate that the stated range will be achieved in FY27. Rather, it sets out management's longer-term objective for the durables segment. Investors will therefore be able to track future quarterly disclosures for evidence of easing input costs, improved operating leverage and progress in new-business ramp-ups.
How does the revised outlook affect investors and the industry?
For investors, the main takeaway is the contrast between the 60% Q2 revenue increase and the more moderate 15-20% FY27 growth outlook. Revenue growth alone did not translate into a comparable expansion in operating EBITDA, as Q2 operating EBITDA increased 30% and the company reported a quarterly net loss.
The earnings call also highlights cost sensitivity in manufacturing businesses supplying consumer durables and electronics. Commodity prices, currency movements and labour costs can affect profitability even when volumes and sales are rising. Amber Enterprises India's results provide a reported example of this relationship during Q2 FY27.
The annual capex plan of ₹1,800-2,000 crore further places attention on balance between investment and returns. The source material does not provide a revised capex target, a detailed funding plan or a timetable beyond the FY29 durables margin objective. Those details remain relevant for evaluating how growth investments translate into financial performance.
Conclusion
Amber Enterprises India delivered strong Q2 FY27 revenue growth, led by expansion in electronics and durables, and maintained positive first-half growth in revenue and operating EBITDA. But management's reduction of FY27 revenue-growth guidance to 15-20% and its comments on cost pressures show that higher sales have not removed near-term margin constraints.
The next points to watch are the company's quarterly progress against its 15-20% FY27 revenue-growth outlook, the effect of commodity, currency and wage costs on profitability, and progress toward the stated 14-16% durables EBITDA-margin normalisation target by FY29. Investors can also monitor the execution of the annual ₹1,800-2,000 crore capital-expenditure programme.