










Amber cuts railway growth outlook to 15-20% as legacy margins lag
Key highlights
- Amber cut Railways Subsystems & Defence revenue-growth guidance to about 15%-20%.
- Railways Subsystems & Defence revenue rose 15% year on year to Rs 152 crore in Q2 FY27.
- The division reported operating EBITDA of Rs 7 crore in Q2 FY27.
- Management expects normalised railway EBITDA margins of about 14%-16% by FY29.
powered by IRIS
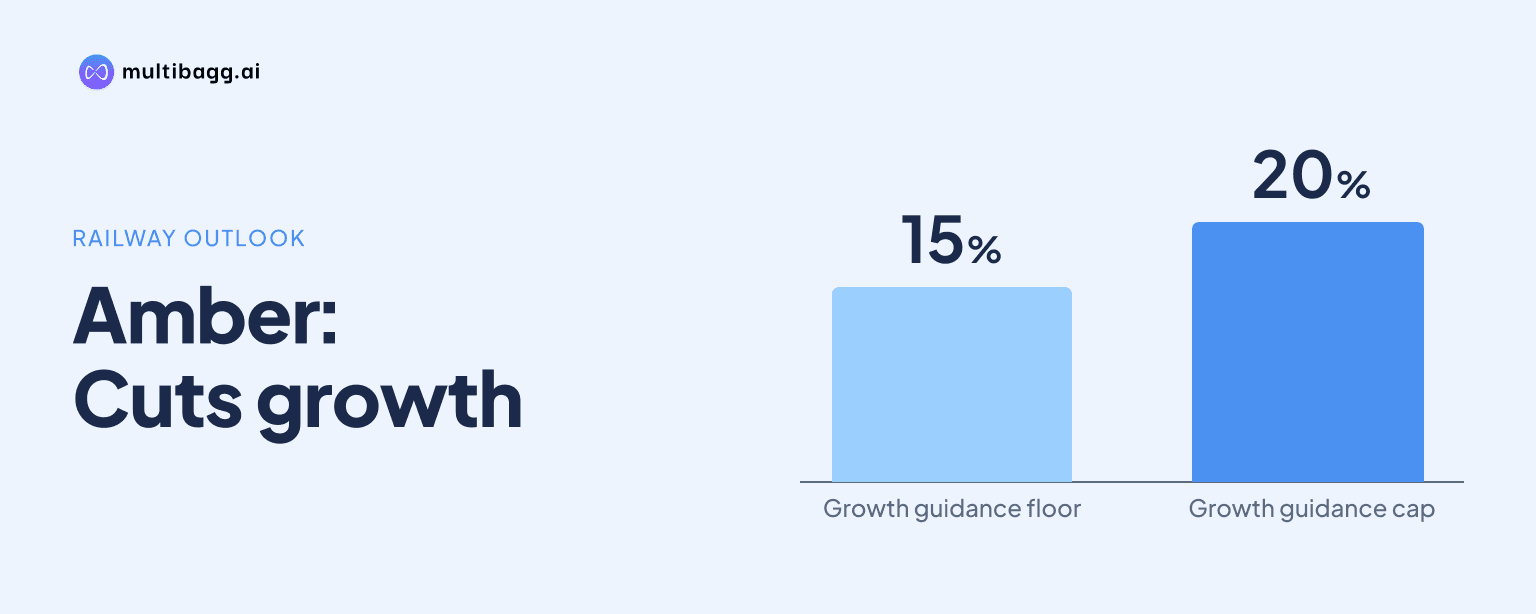
In Q2 FY27, Amber Enterprises India Limited cut its Railways Subsystems & Defence revenue-growth outlook to about 15%-20% after the division grew 15% year on year to Rs 152 crore and reported Rs 7 crore of operating EBITDA, or earnings before interest, tax, depreciation and amortisation. Management cited delayed future project offtakes and fixed-price legacy contracts facing higher costs.
Know Amber Enterprises India inside out
Results, valuation, peers and who's buying, in one view.
Why did Amber cut its railway growth outlook?
Amber cut the division's growth outlook because future project offtakes have been delayed, management said on its November 13, 2026 earnings call. Amber now expects Railways Subsystems & Defence revenue growth of about 15%-20%, below its earlier expectation, despite the division recording 15% year-on-year revenue growth in Q2 FY27.
The lower outlook concerns the timing of customer offtake rather than a disclosed reduction in the order book. Managing Director Daljit Singh said Amber's guidance to double railway-business revenue in two years remained intact because the order book had become stronger, although he did not disclose its value or provide a revised timetable beyond FY28 and FY29.
How did Amber's rail and defence division perform in Q2 FY27?
Amber's Railways Subsystems & Defence division generated Rs 152 crore of revenue and Rs 7 crore of operating EBITDA in Q2 FY27, compared with revenue of Rs 132 crore in Q2 FY26. The Rs 20 crore revenue increase represented 15% year-on-year growth, while the reported operating EBITDA equated to an implied margin of about 4.6% in Q2 FY27.
Amber said the revenue and operating EBITDA figures it presented for divisions are not comparable with its published segmental results. It did not disclose Q2 FY26 operating EBITDA for Railways Subsystems & Defence, so the earnings call does not permit a year-on-year EBITDA comparison for the division.
What is depressing Amber's railway margins?
Amber said commodity inflation, foreign-currency fluctuations and minimum-wage revision affected Railways Subsystems & Defence margins in Q2 FY27. The effect was greater on certain fixed-price contracts, where selling prices do not adjust for input-cost changes, contributing to operating EBITDA of Rs 7 crore on quarterly revenue of Rs 152 crore.
Management said some older railway contracts lack price-variation clauses and that customer-side picking has been delayed. The delay extends execution of projects negotiated under earlier commodity conditions, while newer contracts contain price-variation clauses and use newer commodity prices in their commercial terms.
Amber did not provide a specific FY27 EBITDA-margin forecast for Railways Subsystems & Defence. Management instead described a recovery path in which old fixed-price projects are delivered over the next two to three quarters and the contract mix progressively shifts to newer projects with price-variation clauses.
Got a follow-up? Ask IRIS
When does Amber expect railway margins to recover?
Amber expects railway margins to begin rebounding from next year's second quarter after old fixed-price projects are delivered, according to management's prepared remarks. In the question session, Daljit Singh said a partial improvement could take another two to three quarters, indicating that the recovery would be gradual.
Management identified a normalised EBITDA-margin range of about 14%-16% by FY29. When an analyst asked whether the business would return to its earlier 19%-20% margin range, Daljit Singh said improvement would be gradual and cited 14%-16% as the normalised level instead.
The Q2 FY27 outcome was below that FY29 range: the division's Rs 7 crore operating EBITDA on Rs 152 crore of revenue implied a margin of about 4.6%. Amber did not quantify the separate effects of commodity costs, currency movements, wage changes and delayed delivery of fixed-price projects.
Does Amber still expect to double railway business revenue?
Amber said its two-year guidance to double railway-business revenue remains intact, citing a strengthened order book. That means management retained its longer-term revenue objective while cutting the nearer-term growth outlook to 15%-20% because project offtakes are delayed.
Amber also said Sidwal's greenfield Faridabad facility for heating, ventilation and air conditioning, doors and gangways is operational and scaling production capacity. The call did not disclose the plant's capacity, capital cost or expected FY27 contribution to Railways Subsystems & Defence revenue.
At the consolidated level, Amber expects FY27 capital expenditure of about Rs 1,800 crore to Rs 2,000 crore and reported net debt of Rs 2,582 crore. Management did not provide a segment-wise capital-expenditure split, saying that IL JIN Electronics' draft red herring prospectus filing limited further segment-level discussion on the call.
Conclusion
Amber's lower 15%-20% railway growth outlook reflects delayed future project offtakes, while Q2 FY27 profitability was affected by old fixed-price contracts exposed to higher commodity, currency and wage costs. The division still increased revenue by 15% to Rs 152 crore, but its Rs 7 crore operating EBITDA showed the near-term cost of the current contract mix.
The next milestones are delivery of old projects over the next two to three quarters, the expected margin rebound from next year's second quarter, and management's FY29 target of 14%-16% normalised EBITDA margins. Amber's retained two-year revenue-doubling objective and production ramp-up at Sidwal's Faridabad facility will also depend on delayed project offtakes resuming.