










Arisinfra H1 mix supplied 92% of segment EBITDA as revenue rose
Key highlights
- Arisinfra said contract manufacturing and DaaS generated 64% of H1 FY27 revenue and approximately 92% of segment EBITDA.
- H1 FY27 revenue rose 32% to Rs 599 crore, while EBITDA increased 63% to Rs 66 crore.
- Contract manufacturing revenue increased 72% year on year to Rs 329 crore in H1 FY27.
- DaaS GDV under execution exceeded Rs 2,750 crore across 15 active projects as of November 4, 2026.
powered by IRIS
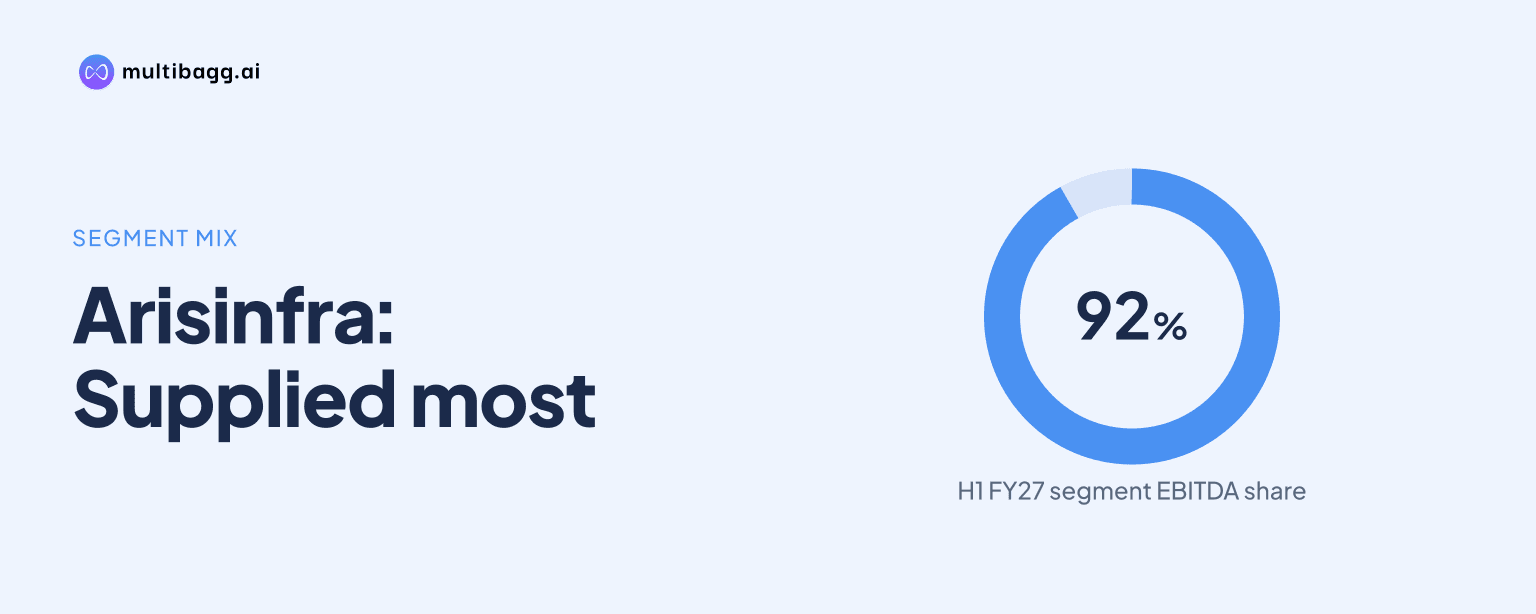
Arisinfra Solutions Limited said contract manufacturing and Developer as a Service, or DaaS, generated 64% of H1 FY27 revenue and approximately 92% of segment EBITDA before non-cash Indian Accounting Standards adjustments, as revenue rose 32% year on year to Rs 599 crore and EBITDA margin expanded 210 basis points to 11.1%.
Know Arisinfra Solutions inside out
Results, valuation, peers and who's buying, in one view.
What drove Arisinfra's H1 FY27 EBITDA mix shift?
Arisinfra's H1 FY27 mix shift came from contract manufacturing and DaaS, which together supplied 64% of revenue and approximately 92% of segment earnings before interest, tax, depreciation and amortisation, or EBITDA. Management specified that the EBITDA contribution is measured before non-cash Indian Accounting Standards, or Ind AS, adjustments, meaning the comparison is not a share of reported consolidated EBITDA.
The revenue mix had already changed in the second quarter. Contract manufacturing and DaaS accounted for 66% of Q2 FY27 revenue, compared with 53% in Q2 FY26, a 13-percentage-point increase. Management said these activities have higher returns and deeper customer engagement, while the materials business provides customer access, procurement relationships and demand intelligence.
The difference between revenue and EBITDA growth supports management's explanation of the mix effect. H1 FY27 revenue from operations increased 32% year on year to Rs 599 crore, while EBITDA rose 63% to Rs 66 crore. EBITDA margin consequently increased to 11.1% from 9.0%, based on the stated 210-basis-point expansion, with 100 basis points equal to one percentage point.
How did Arisinfra's profitability change in Q2 and H1?
Arisinfra reported growth in revenue, EBITDA and profit after tax, or PAT, in Q2 FY27 and H1 FY27. Q2 revenue was Rs 308 crore, up 28% year on year and 6% sequentially, while EBITDA increased 58% year on year to Rs 36 crore. Q2 EBITDA margin reached 11.6%, up 220 basis points year on year.
Arisinfra's H1 FY27 PAT was Rs 43 crore, compared with Rs 20 crore in H1 FY26, while Q2 PAT rose 50% year on year to Rs 23 crore. The H1 EBITDA margin of 11.1% was lower than Q2's 11.6%, but management said both quarterly and first-half profitability improved despite the seasonal moderation it associates with the monsoon period.
How is contract manufacturing changing Arisinfra's supply network?
Arisinfra's contract manufacturing revenue grew 72% year on year to Rs 329 crore in H1 FY27 and represented 55% of total first-half revenue. Management described the model as exclusive partnerships with manufacturing plants, allowing Arisinfra to secure supply and participate further in the value chain without owning plant assets.
Partner manufacturing capacity rose from 9.1 million tonnes to about 11.7 million tonnes during H1 FY27 across aggregates, ready-mix concrete and asphalt. Management clarified that it had about 15 plants at June 30, 2026, counted by plant, and added about eight in Q2. It said ready-mix concrete and asphalt plants carry lower tonnage but higher value per tonne than aggregate plants, so plant count can rise faster than capacity.
Arisinfra said the contract manufacturing platform covers four markets and 11 partners, with no partner accounting for more than one-quarter of capacity. Management put current utilisation at 42% to 45% and said the secured 11.7 million-tonne capacity provides headroom for at least six to nine months without additional capacity. Vendor deposits declined by Rs 13 crore as capacity expanded, according to management.
Got a follow-up? Ask IRIS
How quickly is Arisinfra expanding its DaaS portfolio?
Arisinfra said DaaS gross development value, or GDV, under execution exceeded Rs 2,750 crore as of the November 4, 2026 earnings call. That compared with Rs 1,839 crore at the end of Q1 FY27 and Rs 1,267 crore at the end of FY26. The active-project count rose to 15 from 10 in the preceding quarter.
DaaS covers planning, approvals, funding coordination, materials procurement, project execution, sales and collections. Management said DaaS projects can create demand for Arisinfra's materials and contract manufacturing network, linking the real-estate execution portfolio to the company's supply activities rather than treating it as an entirely separate business.
Management said it typically charges gross DaaS fees of 10% to 14% of GDV. Revenue recognition combines a fixed time-based fee, a portion based on sales achieved and a portion tied to construction milestones. The current DaaS pipeline has execution periods ranging from six months to 30 months, so the Rs 2,750 crore-plus GDV is not equivalent to immediate revenue.
What supports Arisinfra's cash conversion and planned mix change?
Arisinfra reported H1 FY27 operating cash flow of Rs 60 crore, equivalent to 91% of its Rs 66 crore EBITDA. Net working-capital days improved to 54 days from 84 days in September of the previous year. Management linked this outcome to working-capital discipline and an asset-light manufacturing-partnership model.
The company's proprietary technology platform has read more than 14 lakh delivery notes, including handwritten documents. It links purchase orders, goods receipt notes, challans and invoices with pricing intelligence and customer credit limits. Management said the mechanism is intended to reduce manual reconciliation and provide real-time visibility over delivery-level margins and credit exposure.
Management said it has moved away from lower-value trading in selected materials categories and is directing repeat demand towards contract-manufactured supply where feasible. In response to an analyst, management said contract manufacturing and DaaS together could be close to 75% of anticipated sales, while it did not give a numerical target for future capacity additions.
Conclusion
Arisinfra's H1 FY27 results show that the two businesses driving its changing mix contributed more to stated segment EBITDA than to revenue: contract manufacturing and DaaS produced 64% of revenue but approximately 92% of segment EBITDA before non-cash Ind AS adjustments. The same period delivered Rs 599 crore of revenue, Rs 66 crore of EBITDA and Rs 60 crore of operating cash flow.
The next disclosed indicators are utilisation of the 11.7 million-tonne partner capacity, currently at 42% to 45%, and progress across 15 DaaS projects with six-to-30-month execution periods. Management's statement that contract manufacturing and DaaS could approach 75% of anticipated sales makes future revenue mix, working-capital days and DaaS milestone execution central measures to monitor.