










Awfis targets 12% cash EBITDA margin floor from FY28 onward
Key highlights
- Awfis reported a 10.8% cash EBITDA margin in Q2 FY '27, with cash EBITDA of Rs 49 crore.
- Management expects cash EBITDA margin to reach at least about 11.5% in Q4 FY '27 and around 12% in March.
- Awfis said it expects 12% to be the cash EBITDA margin floor as FY '28 begins.
- Premium seats rose 58% year on year to 33,000, with pricing around 35% above the flagship product.
powered by IRIS
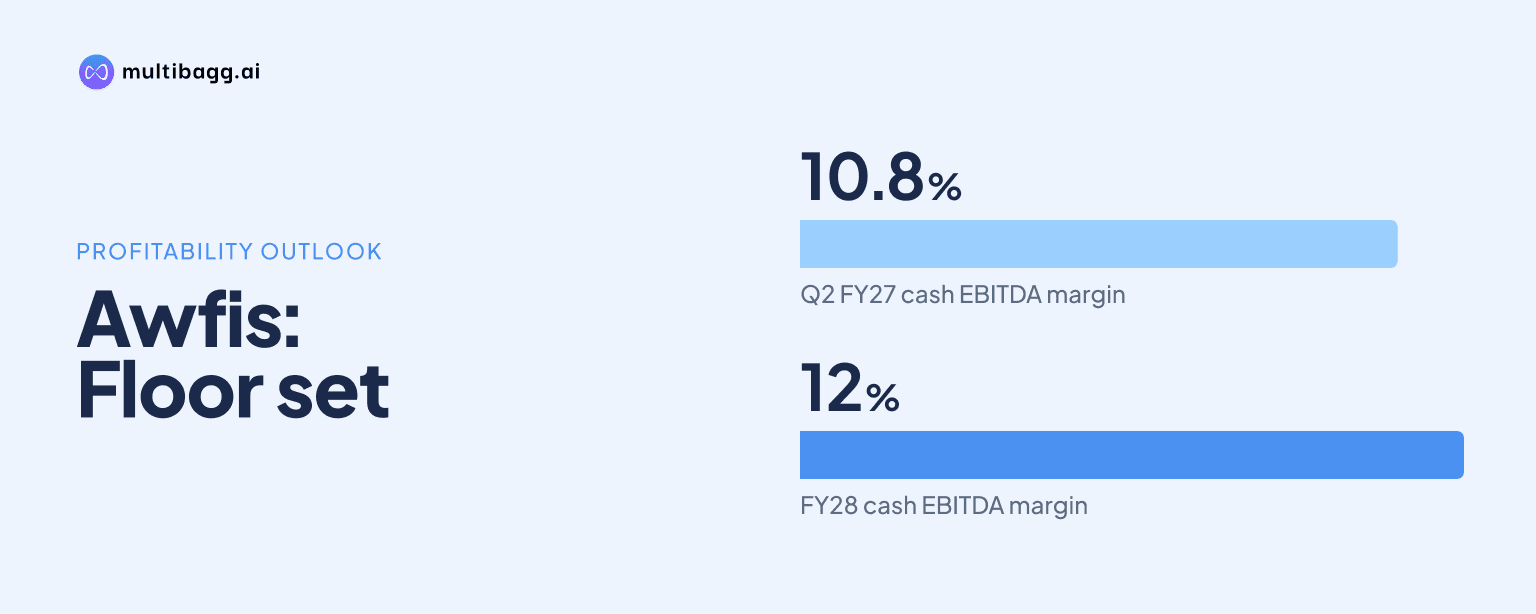
Awfis Space Solutions Limited expects its cash earnings before interest, tax, depreciation and amortisation (cash EBITDA) margin to touch about 12% in the March financial year (FY) '27 exit month, after reporting 10.8% in the second quarter (Q2). Management said 12% should be the floor from the start of FY '28, supported by occupancy gains and maturing premium centres.
Know AWFIS Space Solutions inside out
Results, valuation, peers and who's buying, in one view.
What cash EBITDA margin is Awfis targeting by March FY '27?
Awfis expects cash EBITDA margin to rise sequentially in the second half (H2) of FY '27, reach at least about 11.5% in Q4, and touch around 12% in the March exit month. In response to an analyst's question on 12% as the FY '28 floor, Sumit Lakhani said management would expect that level to be the floor as the company begins FY '28.
This is an exit-margin objective rather than a stated full-year FY '27 margin target. Management's full-year guidance is cash EBITDA of Rs 190 crore to Rs 200 crore, with H2 stronger than the first half (H1) as recently launched centres build occupancy and the premium cohort matures. Awfis reported Rs 93 crore of cash EBITDA in H1 FY '27.
The Q2 margin of 10.8% was 0.3 percentage points above the H1 margin of 10.5%, although H1 includes the prior quarter. Cash EBITDA is Awfis's adjusted cash operating measure rather than reported EBITDA. Awfis said MSKA and Associates LLP validated the metric under an agreed-upon procedure engagement.
Why does Awfis expect margins to rise?
Awfis attributes the planned move toward 12% to better occupancy and a larger, maturing premium portfolio, rather than to seat growth alone. The company said the premium portfolio added about 12,180 seats over the last year and achieves around 35% higher pricing than its overall flagship product.
Gold and Elite centres reached 39 at 30 September 2026, up from 37 at the end of June, comprising 29 Gold and 10 Elite locations. Premium seats rose 58% year on year to 33,000 out of Awfis's more than 164,000 operational seats. Management said 100% of new supply is in Grade A and A+ assets in high-demand micro-markets, which it views as the natural setting for its premium formats.
The premium offering uses more space per billable seat, at roughly 58 to 65 square feet for Gold and Elite centres compared with about 50 square feet for the overall portfolio. Management nevertheless expects higher realisations, longer lock-ins and greater attachment of allied services to offset that cost as newer sites mature. That is the disclosed mechanism behind the expected margin progression, not a reported margin split between premium and flagship locations.
Got a follow-up? Ask IRIS
How does Awfis's current margin compare with its FY '27 plan?
Awfis's Q2 FY '27 cash EBITDA of Rs 49 crore increased 45% year on year, faster than its 26% increase in normalised revenue to Rs 451 crore. The resulting 10.8% cash EBITDA margin provides the starting point for management's stated expectation of at least about 11.5% in Q4 and around 12% in March.
For H1 FY '27, normalised revenue rose 30% year on year to Rs 888 crore and cash EBITDA rose 40% to Rs 93 crore, producing a 10.5% margin. Reported revenue under Indian Accounting Standards (Ind AS) was lower at Rs 864 crore in H1, because certain long-term lease arrangements accounted for under Ind AS 116 affect the timing of revenue recognition.
Awfis calculates cash EBITDA after adjusting for finance-lease accounting, deducting actual cash lease rentals paid in the period and excluding certain non-cash costs. The company reported Q2 EBITDA of Rs 174 crore and profit before tax of Rs 31 crore, but these are not comparable with cash EBITDA without those adjustments. The 12% floor therefore refers specifically to cash EBITDA margin.
Which operating data support Awfis's margin outlook?
Awfis's operating data show rising occupancy while capacity expanded during Q2 FY '27. Occupancy at centres operating for more than 12 months increased to 84.1% from 83.0% in Q1, while blended portfolio occupancy rose to 76.2% from 76.0%, even as operational capacity increased to more than 164,000 seats from about 159,000 at the end of June.
During Q2, Awfis added about 7,000 gross seats and launched six centres, while exiting around 2,200 seats across four centres through portfolio optimisation. For H1, it added about 12,000 gross seats and 13 new centres. Management expects gross additions of 22,000 to 25,000 seats in FY '27 and total closures of around 5,500, of which nearly 4,000 had already closed in H1.
Longer customer commitments could also provide a steadier occupancy base. Weighted average client tenure was 38 months and lock-in tenure was 27 months at 30 September 2026, compared with a 26-month lock-in at the end of June. Awfis said 77% of seats had tenure of at least 24 months and another 18% had tenure of 12 to 23 months, meaning 95% of the base was committed for at least one year.
The enterprise mix is relevant to the premium-centre plan. Enterprises and multinational companies represented 64% of Awfis's client base, while global capability centres contributed approximately 24% of rental revenue across more than 105 clients in nine cities. The company also said clients with more than 500 seats accounted for 37% of seats, a customer segment it associates with managed-office and premium-space demand.
Conclusion
Awfis has set out a measurable profitability path: a 10.8% cash EBITDA margin in Q2 FY '27, at least about 11.5% expected in Q4, and around 12% targeted for the March exit month. Management's view is that premium pricing of roughly 35% above the flagship product, alongside occupancy increases to 84.1% in mature centres and 76.2% across the portfolio, can support a 12% margin floor from FY '28.
The next disclosures to watch are whether Awfis reaches more than 174,000 operational seats by the end of March after planned gross additions of 22,000 to 25,000 and about 5,500 closures in FY '27. Investors can also assess whether H2 delivers the management-guided Rs 190 crore to Rs 200 crore of full-year cash EBITDA as new premium centres ramp up and the March margin target approaches.