










Carraro India Limited Q2 revenue rises 19% to INR696.5 crore
Key highlights
- Carraro India Limited's Q2 FY27 revenue from operations rose 19% year-on-year to INR696.5 crore.
- Q2 FY27 EBITDA increased 10% year-on-year to INR65.2 crore.
- H1 FY27 revenue from operations rose 15% year-on-year to INR1,241.1 crore.
- Q1 FY27 exports declined about 14% year-on-year, according to management.
powered by IRIS
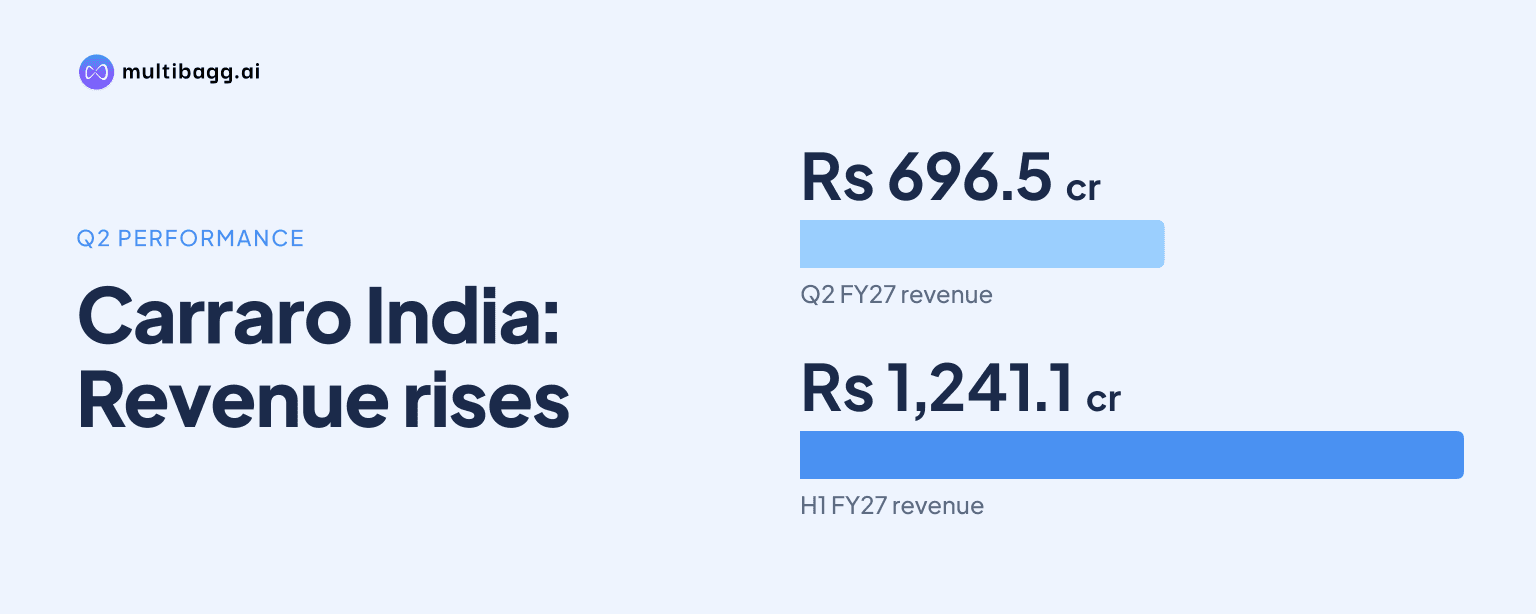
Carraro India Limited reported revenue from operations of INR696.5 crore in Q2 FY27, up 19% year-on-year and 28% sequentially, while EBITDA rose 10% year-on-year to INR65.2 crore. The performance indicates continued domestic-market support despite the export and cost pressures discussed in the company’s earlier quarterly call.
Know Carraro India inside out
Results, valuation, peers and who's buying, in one view.
What did Carraro India report for Q2 FY27?
Carraro India reported Q2 FY27 revenue from operations of INR696.5 crore, compared with a year earlier, representing 19% year-on-year growth. Revenue also increased 28% from Q1 FY27. Total income for the quarter rose 19% year-on-year to INR705.8 crore.
EBITDA was INR65.2 crore in Q2 FY27, up 10% year-on-year and 13% from the preceding quarter. The gap between revenue growth and EBITDA growth means the reported operating earnings expanded at a slower rate than sales during the quarter. The company did not provide a Q2 net-profit figure in the supplied call material.
Management said the domestic market continued to provide a more supportive demand environment. It described the quarter as one of healthy growth in both revenue and absolute earnings. The Q2 FY27 earnings conference call was held on November 6, 2026, with Whole Time Director and CFO Davide Grossi, Whole Time Director and COO Sudhendra Mannikar, and Director Sales and Business Development Ashok Rai among the participants.
How did the first half of FY27 progress?
Carraro India recorded revenue from operations of INR1,241.1 crore for the first half of FY27, an increase of 15% year-on-year. The H1 figure includes Q1 revenue of INR544.7 crore and Q2 revenue of INR696.5 crore, based on the quarterly figures disclosed in the earnings calls.
The second-quarter revenue figure was higher than the first-quarter level, consistent with the company’s stated 28% sequential increase. This strengthened the first-half revenue outcome even as conditions varied across its markets. The supplied material does not state H1 EBITDA, profit after tax, or a full-year financial outlook.
In Q1 FY27, the company said domestic revenue rose approximately 26% year-on-year. It also said domestic demand across key end markets helped offset temporary export weakness. That first-quarter commentary provides context for management’s statement in the Q2 call that domestic conditions remained more supportive.
Got a follow-up? Ask IRIS
What market conditions shaped Carraro India’s performance?
Carraro India attributed its Q2 revenue growth to a supportive domestic demand environment, while its Q1 commentary had highlighted pressure on exports. In Q1 FY27, exports declined approximately 14% year-on-year because of geopolitical disruptions and supply-chain challenges in certain international markets.
The company’s Q1 performance showed how these opposing trends affected the business. Revenue from operations grew 10% year-on-year to INR544.7 crore, while total income rose 12% to INR558.7 crore. Domestic growth therefore played an important role in maintaining overall sales growth when international demand was weaker.
Q1 EBITDA was INR57.9 crore, up 6% year-on-year, with an EBITDA margin of 10.4%. Management cited higher energy and raw-material costs and lower labour availability as factors affecting that margin. Q1 profit after tax increased 8% year-on-year to INR31.4 crore, and the PAT margin was 5.6%.
The Q1 total-income figure also included an INR8.8 crore one-time provision write-back related to customs proceedings after a company reassessment. This was identified as other income, rather than revenue from operations, and should be considered separately when comparing total income with operating sales.
Why does the Q2 result matter to investors?
The Q2 result matters because Carraro India delivered faster revenue growth than in Q1, with sales rising 19% year-on-year in the second quarter against 10% in the first. The 28% sequential revenue increase also lifted first-half revenue growth to 15% year-on-year.
Operating earnings increased in both Q1 and Q2, although the available information shows EBITDA growth lagged sales growth in Q2. EBITDA rose 10% year-on-year to INR65.2 crore while Q2 revenue rose 19%. The reported figures establish growth in absolute operating profit but do not disclose a Q2 EBITDA margin in the supplied material.
For investors, the call commentary keeps attention on the balance between domestic demand and export conditions. The company’s prior update identified geopolitical disruptions and supply-chain challenges in international markets, while domestic revenue and demand were described as stronger. No specific forecast for export recovery, margins, or FY27 earnings was provided in the supplied text.
Carraro India has also continued to make earnings-call materials available through its investor resources and exchange filings. The company informed the exchange that the audio recording of the November 6, 2026 earnings conference call was available, while earlier calls and transcripts were also referenced in its corporate announcements.
Conclusion
Carraro India’s Q2 FY27 update showed a clear acceleration in revenue, with operations revenue reaching INR696.5 crore and EBITDA reaching INR65.2 crore. First-half revenue rose 15% to INR1,241.1 crore, supported by the domestic market, while the earlier Q1 discussion showed that export weakness and input-cost pressures remained relevant operating considerations.
The next point to watch is whether domestic demand continues to offset the export disruptions and supply-chain challenges identified by management in Q1 FY27. Investors will also look for future disclosures on margins, profitability and any updated commentary on international-market conditions, as these details were not provided in the available Q2 call extract.