










ECL Finance Limited ends SR book as loans more than double
Key highlights
- ECL Finance wound down its wholesale SR book from $1,875 million in March 2019 to zero.
- ECL Finance's gross loan book rose to $265 million in Q2FY27 from $121 million in Q2FY26.
- ECL Finance reported Q2FY27 disbursals of $58 million, described by management as tripled year on year.
- ECL Finance's GNPA ratio declined to 2.10% from 3.35%, a 125-basis-point reduction.
powered by IRIS
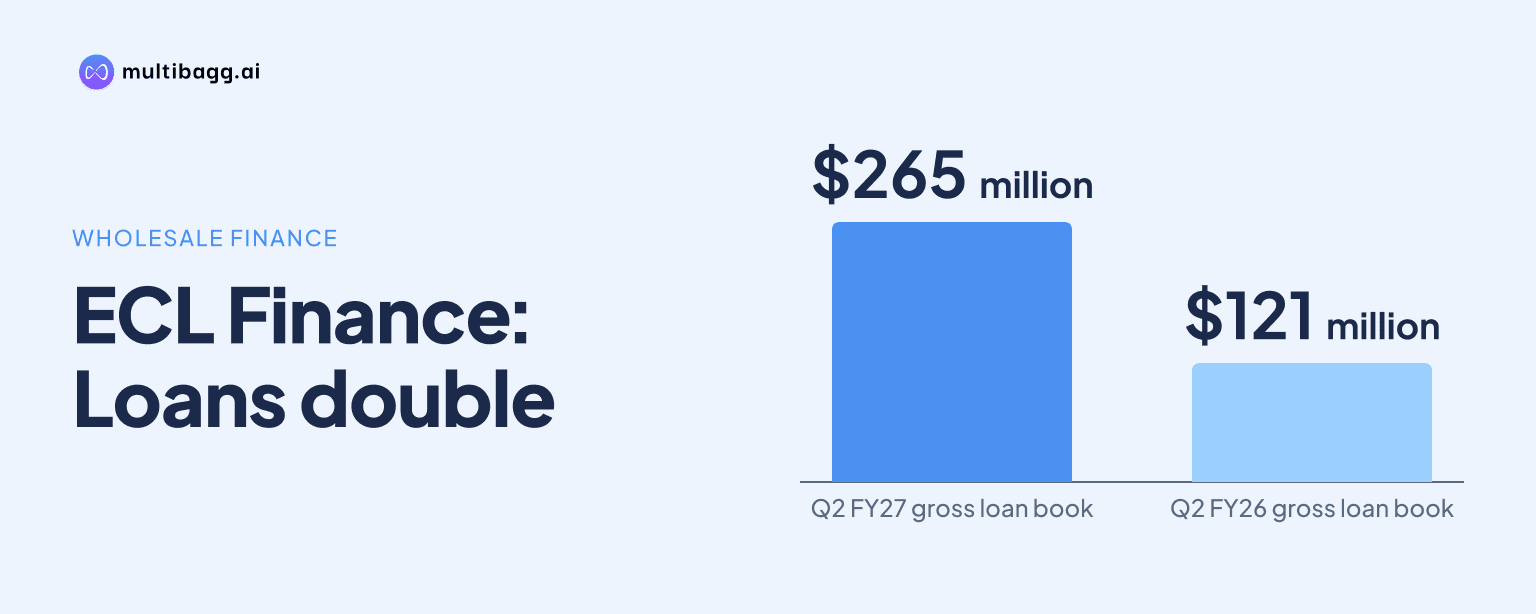
ECL Finance Limited ended its wholesale security-receipt book at zero in Q2FY27, compared with $1,875 million in March 2019, while its gross loan book rose to $265 million from $121 million a year earlier. ECL Finance also reported quarterly disbursals of $58 million, described as tripled year on year, and gross non-performing assets of 2.10%, down 125 basis points.
Know Edelweiss Financial Services inside out
Results, valuation, peers and who's buying, in one view.
What happened to ECL Finance's wholesale SR book?
ECL Finance wound down its wholesale security-receipt, or SR, book to zero from $1,875 million in March 2019. The presentation identifies this as the outcome for the legacy wholesale SR exposure, with the current zero balance disclosed in its Q2FY27 business-performance snapshot rather than as a quarter-on-quarter change.
The presentation does not provide borrower-level, asset-class, recovery or write-off details for the $1,875 million wholesale SR portfolio. It therefore establishes the full wind-down of that legacy exposure, but does not show the route by which the balance was reduced or the dates of individual transactions.
The current balance-sheet measures disclosed alongside the zero SR balance were $172 million of equity, $90 million of liquidity and a 23% capital-adequacy ratio. ECL Finance also reported assets under management, or AUM, of $265 million, the same figure shown as its gross loan book as of September in Q2FY27.
How much did ECL Finance's loan book grow?
ECL Finance's gross loan book increased to $265 million in Q2FY27 from $121 million in Q2FY26, an increase of $144 million. The September loan book was therefore more than twice its year-earlier level, while quarterly disbursals reached $58 million and were described by management as tripled year on year.
The $144 million expansion in the loan book was larger than the $1 million increase in gross revenue, which rose to $19 million from $18 million. Net revenue doubled to $8 million from $4 million, but the presentation does not disclose loan yields, product mix, borrower categories, loan tenors or the reasons for the difference between loan-book and revenue growth.
The supplied presentation does not identify any part of the $265 million loan book as micro, small and medium enterprise, or MSME, lending. Its $58 million disbursal figure supports a faster pace of overall lending activity, but it does not substantiate an MSME-specific acceleration or disclose the MSME share of the portfolio.
How did ECL Finance's asset quality change?
ECL Finance's gross non-performing asset, or GNPA, ratio fell to 2.10% in Q2FY27 from 3.35% in Q2FY26, a reduction of 125 basis points. One basis point equals one hundredth of a percentage point, and the presentation separately highlights the same 125-basis-point year-on-year improvement.
Net non-performing assets, or NNPA, declined to 1.19% from 1.94%, a 75-basis-point reduction. Both reported asset-quality ratios declined while the gross loan book increased by $144 million to $265 million, meaning the lower percentages were reported alongside a substantially larger loan portfolio.
ECL Finance reported credit cost of $1 million in Q2FY27, compared with $0.3 million in Q2FY26. The presentation does not explain the increase in quarterly credit cost despite the lower GNPA and NNPA ratios, and it does not disclose provision coverage, write-offs, recoveries or the gross value of impaired loans.
Got a follow-up? Ask IRIS
What did ECL Finance report for revenue and profit?
ECL Finance reported net revenue of $8 million in Q2FY27, double the $4 million reported in Q2FY26, while profit after tax was unchanged at $0.4 million. Gross revenue rose by $1 million to $19 million, so the increase in reported net revenue exceeded the change in gross revenue.
Operating expenditure, or opex, increased to $6 million from $3 million, while credit cost rose to $1 million from $0.3 million. Those two disclosed cost lines increased by a combined $3.7 million, compared with a $4 million increase in net revenue, while profit after tax remained $0.4 million in both periods.
The Q2FY27 financial snapshot does not provide interest expense, tax expense, margins, return on equity or a reconciliation from gross revenue to profit after tax. The disclosed figures therefore show the period-on-period movements in revenue, opex, credit cost and profit, but do not establish the operational drivers behind the unchanged profit.
What funding and capital measures did ECL Finance disclose?
ECL Finance disclosed $78 million of borrowing support available from banks, $90 million of liquidity and $172 million of equity in Q2FY27. Management described bank interest as strong, but the presentation states available borrowing support rather than borrowings drawn, lender names, pricing or repayment terms.
The company reported a 23% capital-adequacy ratio alongside AUM of $265 million and quarterly disbursals of $58 million. The presentation does not state the applicable regulatory minimum, the composition of capital or a Q2FY26 comparison for available borrowing support, so it does not permit a period-on-period funding assessment.
The $90 million liquidity measure was reported in the same Q2FY27 snapshot as the $265 million AUM figure. ECL Finance does not define liquidity in the supplied pages or split it among cash, undrawn facilities and other sources, leaving the makeup and maturity profile of that amount undisclosed.
Conclusion
ECL Finance's disclosed transition combines the elimination of a $1,875 million wholesale SR book from March 2019 with a gross loan book that increased from $121 million in Q2FY26 to $265 million in Q2FY27. Over the same comparison, GNPA fell by 125 basis points to 2.10%, NNPA declined by 75 basis points to 1.19%, and net revenue doubled to $8 million, while profit after tax stayed at $0.4 million.
The next issues to watch are whether ECL Finance converts the $78 million of available bank borrowing support into funding and whether future disbursals extend the $58 million reported in Q2FY27. The presentation also leaves unresolved the loan-product and borrower mix, the makeup of $90 million in liquidity, and the reason credit cost increased to $1 million from $0.3 million as reported bad-loan ratios fell.