










Emami Raises Strategic Investments Target to Rs 800-850 Crore
Key highlights
- Emami raised its FY27 strategic-investments revenue target to Rs 800-850 crore.
- Strategic investments grew 73% like-for-like in Q2 FY27, compared with 61% in Q1 FY27.
- Strategic investments contributed approximately 26% of Emami’s domestic business in Q2 FY27.
- Management said the Q2 strategic-investments run rate implied Rs 1,000-1,100 crore of annualised revenue.
powered by IRIS
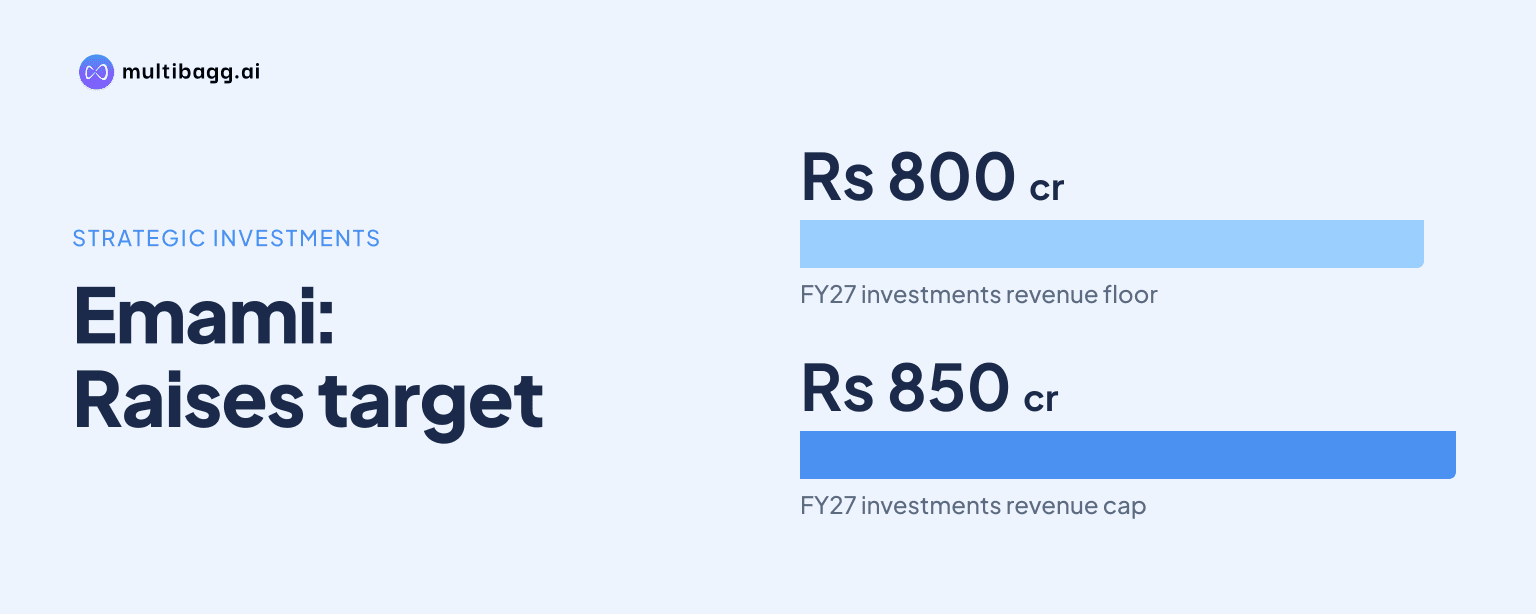
Emami Limited raised its FY27 strategic-investments revenue target to Rs 800-850 crore after the portfolio grew 73% on a like-for-like basis in Q2 FY27, while management said its current run rate implied Rs 1,000-1,100 crore. The portfolio accounted for about 26% of domestic business during the quarter ended September 30, 2026.
Know Emami inside out
Results, valuation, peers and who's buying, in one view.
Why did Emami raise its strategic-investments revenue target?
Emami raised the FY27 target for its strategic-investments portfolio to Rs 800-850 crore, from the Rs 750-800 crore range referred to by an analyst as the Q1 FY27 guidance. Chief Growth Officer Dhruv Aggarwal said the business would deliver more than Rs 800 crore in FY27, and Vice Chairman Mohan Goenka then specified the Rs 800-850 crore range.
The revised range follows a quarterly pace that management described as about Rs 240 crore in Q2 FY27. Goenka said an annualised calculation based on that run rate would imply Rs 1,000-1,100 crore, although this was a run-rate observation rather than a revised full-year target. The difference indicates management retained a lower formal target than the simple quarterly annualisation.
The portfolio’s 73% like-for-like growth in Q2 FY27 also marked an acceleration from 61% in Q1 FY27, according to Aggarwal. He said the Q2 result was 12 percentage points above Q1’s growth rate, while noting that growth at roughly 70% was aggressive and was unlikely to continue indefinitely.
What drove Emami's 73% strategic-investments growth?
Emami said the 73% like-for-like increase reflected contributions from all four strategic brands: Brillare, The Man Company, Axiom and IncNut. Axiom and Brillare each more than doubled sales, IncNut grew by more than 50%, and The Man Company grew by more than 30% in Q2 FY27.
Channel expansion formed part of the growth mechanism. Emami expanded Axiom into modern-trade chains and quick-commerce channels, while investing in visibility for its AloFrut brand. For IncNut, the company moved beyond its direct-to-consumer, or D2C, base into marketplaces, began quick-commerce operations and entered new international markets.
The strategic-investments portfolio contributed approximately 26% of Emami’s domestic business in Q2 FY27. That contribution came as domestic sales rose 49%, driven by 43% volume growth; on a like-for-like basis excluding prior-period revenue of Axiom and IncNut Digital, domestic business grew 32% and volume rose 26%.
Which strategic-investment brands are scaling fastest at Emami?
Emami identified Axiom and Brillare as the fastest-growing strategic brands in Q2 FY27 because both more than doubled sales. IncNut’s growth exceeded 50%, while The Man Company increased sales by more than 30%, giving the portfolio growth across beauty, grooming and digital-first consumer offerings rather than a single-brand result.
The Man Company had previously been relatively stagnant, according to Aggarwal, but its growth moved into the high-20% range before exceeding 30% in Q2 FY27. Management attributed its plan to reformulation, improving the product offering and marketing products in ways it said matched consumer preferences.
Management did not disclose revenue, profit or margin figures for the individual strategic brands. Aggarwal said every one of the four brands had different growth levers and that the overall 73% result required all of them to perform, meaning a slowdown in even one brand would affect the combined growth rate.
Got a follow-up? Ask IRIS
Is Emami reporting improved profitability from strategic investments?
Emami did not provide a portfolio-level profitability figure or confirm a quarter-on-quarter improvement in strategic-investment profits for Q2 FY27. In response to an analyst’s question about profit metrics, management focused on operating plans, new talent, research and development, or R&D, and product launches rather than providing earnings figures.
For The Man Company, Aggarwal said management had moved the brand to high-20% margins, but the call did not define the margin measure, disclose the prior-period margin or provide equivalent data for Brillare, Axiom or IncNut. The available disclosure therefore supports brand-level progress at The Man Company but not a quantified conclusion for the whole portfolio.
Emami’s wider consolidated profitability was affected by commodity costs and business mix in Q2 FY27. Gross margin moderated by 520 basis points year on year, with management attributing 400 basis points to raw-material costs and the balance to mix following acquired-business integration; earnings before interest, tax, depreciation and amortisation, or EBITDA, still rose 25% to Rs 222 crore.
How does the strategic portfolio fit Emami's broader FY27 plan?
Emami is using strategic investments to broaden its domestic business beyond traditional fast-moving consumer goods, or FMCG, personal care and healthcare brands into premium beauty, grooming, digital-first brands and emerging consumer platforms. Management said this diversification was intended to expand the company’s growth runway and balance exposure across consumption cycles.
The company’s organised channels represented 37% of domestic business in Q2 FY27, supporting the strategy’s reliance on modern trade, e-commerce and quick commerce. Quick commerce alone accounted for around 15% of Emami’s digital sales, while management said both modern trade and e-commerce maintained momentum during the quarter.
The core portfolio also posted broad category growth in Q2 FY27, providing the larger base alongside which strategic brands are being scaled. Skincare grew 31%, hair and scalp care rose 30%, healthcare increased 11%, and 7 Oils in One nearly doubled sales, while international revenue declined 2% because of floods in Nepal and supply-chain disruption in Gulf markets.
Conclusion
Emami’s Rs 800-850 crore FY27 strategic-investments target is a management upgrade supported by 73% like-for-like growth, up from 61% in Q1 FY27, and by contributions from all four identified brands. The portfolio’s approximately 26% share of domestic business shows that the digital-first businesses have become material to domestic growth, even though portfolio-wide profitability was not disclosed.
Investors should watch whether the portfolio can sustain growth while moving toward the revised target, particularly as management said 70%-plus growth may not persist. Other disclosed markers to monitor are expansion of IncNut into marketplaces and international markets, Axiom’s rollout in modern trade and quick commerce, product launches and R&D investment, and management’s stated full-year advertising and promotion spending range of 18-19% of sales.