










Iris Clothings Expects Infantwear to Reach 20% of Sales
Key highlights
- Iris Clothings expects infantwear to increase from roughly 12%-13% to about 20% of sales in the next couple of quarters.
- The dedicated infantwear plant has capacity of around 2,500 pieces per day and is expected to add Rs 3 crore to Rs 4 crore in annual revenue.
- Q2 FY '27 total income rose 40.3% year on year to Rs 62.22 crore, while profit after tax increased 23.3% to Rs 5.08 crore.
- Iris Clothings is targeting revenue of around Rs 500 crore over the next two years and is evaluating a greenfield manufacturing project.
powered by IRIS
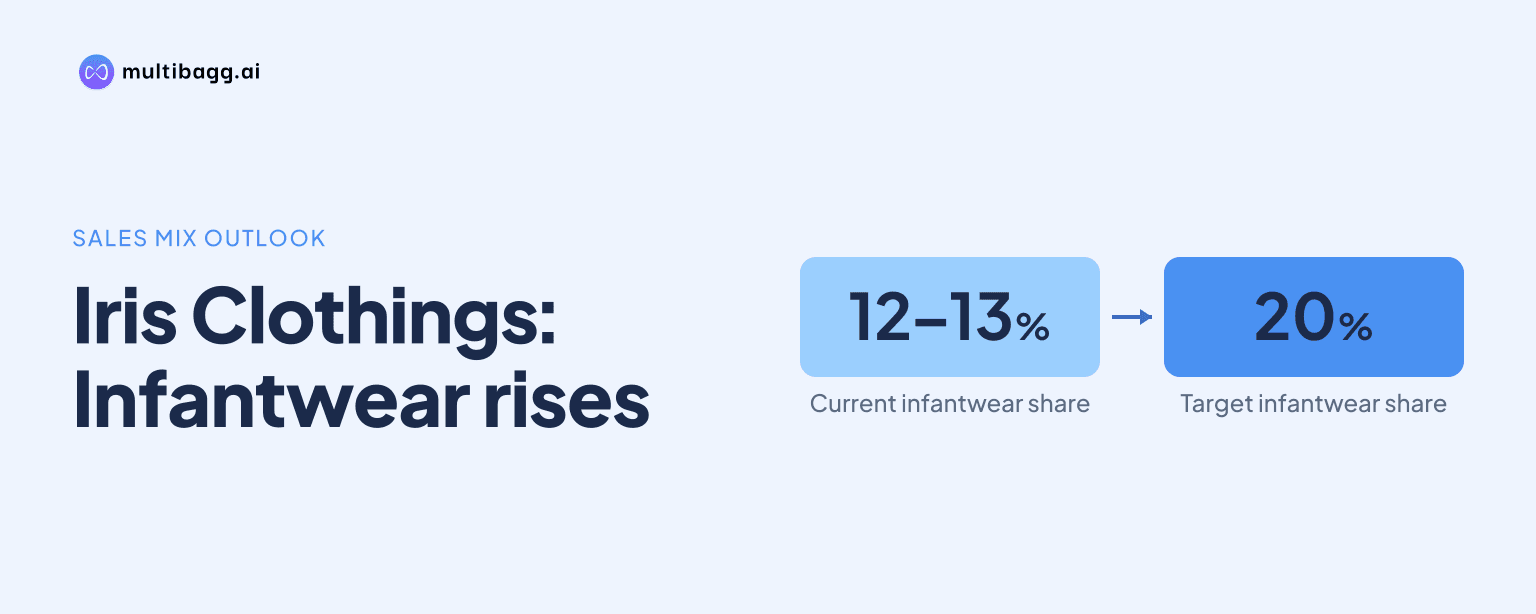
Iris Clothings Limited expects infantwear to rise from roughly 12%-13% to about 20% of overall sales in the next couple of quarters. Management is supporting that aim with a dedicated infantwear plant capable of producing around 2,500 pieces daily, which it expects to add Rs 3 crore to Rs 4 crore of annual revenue.
Know Iris Clothings inside out
Results, valuation, peers and who's buying, in one view.
How much infantwear capacity is Iris Clothings adding?
Iris Clothings has set up a dedicated infantwear plant with current capacity of around 2,500 pieces per day. Management said the facility is intended to support the growing infantwear portfolio and provide operational flexibility as demand and product offerings develop.
Management expects the plant to generate Rs 3 crore to Rs 4 crore of additional annual revenue. The call did not disclose the plant's capital expenditure, expected utilisation, commissioning date or the timeline for reaching that revenue range, so the figure remains management's expectation rather than reported revenue.
The plant is part of a wider manufacturing expansion. Iris Clothings said it had started a new in-house embroidery unit using machines imported from Japan, allowing it to develop premium embroidered collections. Management also said two new units established during the last couple of quarters had increased employee-benefit expenses, with productivity expected from those units over the next two quarters.
Iris Clothings continues to combine in-house production with outsourcing. Management said around 15% of overall revenue comes from outsourced products that are not manufactured internally, and that these products have slightly lower gross margins. It said the arrangement helps broaden the portfolio, including categories such as jeans raised during the analyst discussion.
What share of sales does Iris Clothings expect from infantwear?
Iris Clothings expects infantwear to increase from roughly 12%-13% of overall revenue to around 20% in the next couple of quarters. The planned change would lift the category's sales mix by about 7 to 8 percentage points, subject to plant output and demand for the expanded range.
Management described infantwear as a segment receiving promising responses. Iris Clothings has also launched newborn gift sets in four-piece and six-piece formats across multiple sales channels, adding products aimed at the newborn category. The company did not disclose infantwear revenue in rupees or category-level margins.
The targeted increase comes alongside expansion in other apparel categories. Iris Clothings is adding woven pants to its woven night-suit offering and expects woven apparel to account for around 10% of revenue by the end of next year. That is a later target than the infantwear objective of about 20% in the next couple of quarters.
Management attributed Q2 FY '27 growth primarily to volume rather than higher realisation per piece. It said volume growth came from broader product categories and greater production capacity within existing categories, linking the infantwear plant to a wider effort to enlarge the DOREME range.
Got a follow-up? Ask IRIS
How will Iris Clothings sell its expanded infantwear range?
Iris Clothings is using digital channels, marketplaces and quick commerce alongside its existing distribution network to broaden access to its products. Management said digital revenue, including marketplaces, represents around 10% of overall revenue, while the company has been selling through FirstCry for the last three to four years.
At the time of the Q2 and H1 FY '27 call, Amazon had been live for about three weeks and Myntra had signed an agreement, with a launch expected by the end of the following week. Management said the encouraging digital response received so far had mostly come from its own doreme.in platform, supplemented by its expanding FirstCry presence, rather than the newly launched marketplaces.
Iris Clothings has also entered quick commerce in Bengaluru and Hyderabad through a partnership with Big Basket. Management said it plans to add product categories across multiple quick-commerce platforms and to market doreme.in in more cities. It did not provide revenue splits for distributors, retail, quick commerce, exclusive brand outlets, exports or individual marketplaces.
Management said margins on doreme.in are higher than on external platforms, although Iris Clothings is spending on advertising to build direct website traffic. Advertising represented around 2% of overall revenue at the time of the call, and management intends to increase it to around 3.5% by the end of the year. It said website-level margins would be discussed when volumes are larger.
What financial position accompanies the infantwear expansion?
Iris Clothings reported Q2 FY '27 total income of Rs 62.22 crore, up 40.3% year on year from Rs 44.35 crore in Q2 FY '26. Profit after tax increased 23.3% to Rs 5.08 crore, while earnings before interest, tax, depreciation and amortisation, or EBITDA, stood at Rs 9.47 crore and the EBITDA margin was 15.2%.
For H1 FY '27, Iris Clothings reported EBITDA of Rs 17.57 crore and an EBITDA margin of 16%, compared with 15.1% in the corresponding prior-year period. First-half profit after tax rose 34.7% to Rs 9.09 crore, and the profit-after-tax margin was 8.3%. Management did not quantify infantwear's contribution to those reported results.
Management said higher raw-material prices were creating challenges for margin growth, but it expected basis-point improvement for the full year. It also said current employee and operating expenses should form the base going forward, with their percentage of revenue expected to return towards prior levels as revenue grows over the next few quarters and the two new units become more productive.
Over the next two years, management is targeting revenue of around Rs 500 crore. Iris Clothings is evaluating a greenfield manufacturing project and said it could provide more concrete details in the second half of the year or the next quarter. Management said funding would mostly be through internal accruals, although debt remained possible because the company had no long-term debt at the time of the call.
Conclusion
The dedicated 2,500-piece-a-day plant gives Iris Clothings a defined capacity mechanism for its plan to increase infantwear from roughly 12%-13% to about 20% of revenue. The expected Rs 3 crore to Rs 4 crore annual revenue addition sits alongside newborn gift sets, broader digital access and further category development, including a target for woven apparel to reach around 10% of revenue by the end of next year.
The next points to watch are management's next-couple-of-quarters infantwear mix objective and its expectation that two recently added units will deliver productivity over the next two quarters. Management also plans to provide more detail on the proposed greenfield project in the second half of the year or next quarter, while advertising spending is intended to rise from around 2% to around 3.5% of revenue by year-end.