










JK Lakshmi Cement Q2 profit falls 75% to Rs 20.88 crore
Key highlights
- JK Lakshmi Cement reported Q2 FY27 PAT of Rs 20.88 crore, down 75% from Rs 82.33 crore a year earlier.
- JK Lakshmi Cement’s Q2 FY27 sales volume rose 5% to 29.83 lakh tonnes and net sales rose 6% to Rs 1,616.92 crore.
- JK Lakshmi Cement’s Q2 FY27 PBIDT fell 29% to Rs 164.49 crore from Rs 232.86 crore.
- JK Lakshmi Cement’s net debt-to-EBITDA ratio increased to 2.31 times from 1.25 times a year earlier.
powered by IRIS
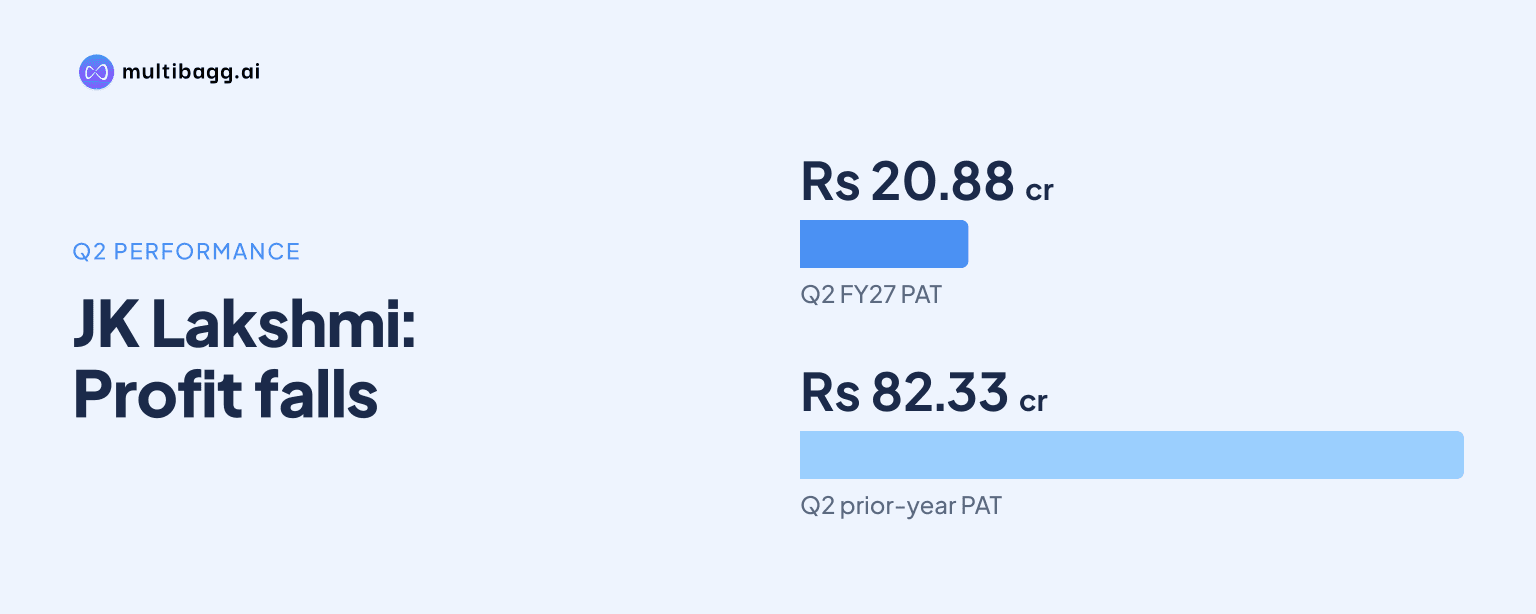
JK Lakshmi Cement Limited reported net profit of Rs 20.88 crore for July-September 2026, down 75% from Rs 82.33 crore a year earlier, as PBIDT fell to Rs 164.49 crore despite a 5% rise in sales volume to 29.83 lakh tonnes and net sales growth to Rs 1,616.92 crore.
Know JK Lakshmi Cement inside out
Results, valuation, peers and who's buying, in one view.
How did JK Lakshmi Cement perform in Q2 FY27?
JK Lakshmi Cement’s profit after tax, or PAT, was Rs 20.88 crore in Q2 FY27, versus Rs 82.33 crore in July-September 2025, while profit before tax, or PBT, declined to Rs 29.02 crore from Rs 104.97 crore. The company disclosed the unaudited results on November 4, 2026, after its board approved financial results for the quarter and six months ended September 30, 2026.
Net sales increased 6% year on year to Rs 1,616.92 crore in Q2 FY27 from Rs 1,531.77 crore, while sales volume increased to 29.83 lakh tonnes from 28.43 lakh tonnes. However, profit before interest, depreciation and tax, or PBIDT, decreased 29% to Rs 164.49 crore from Rs 232.86 crore. Higher reported revenue and volume therefore did not translate into a higher operating-profit measure.
Why did JK Lakshmi Cement earnings fall while sales volume rose?
JK Lakshmi Cement’s disclosed figures show that PBIDT fell by Rs 68.37 crore in Q2 FY27, while PBT fell by Rs 75.95 crore and PAT declined by Rs 61.45 crore. The release does not provide a quarterly cost bridge or identify a single quantified cause for the earnings decline, so the reported evidence is that operating profitability dropped despite higher volume and net sales.
Management said cement demand is expected to improve during the second half, or H2, of FY27 with the peak construction season. It also said elevated petcoke prices and geopolitical uncertainties are likely to keep fuel, freight and packaging costs under pressure, while margins would depend on improved price realisations, input-cost moderation and operational efficiencies. These are management outlook statements rather than reported Q2 cost-line figures.
What were JK Lakshmi Cement’s first-half FY27 results?
JK Lakshmi Cement reported PAT of Rs 127.65 crore for April-September 2026, down from Rs 234.00 crore in the corresponding six months of FY26, even as net sales rose to Rs 3,521.70 crore from Rs 3,272.70 crore. Six-month sales volume increased 7% to 65.81 lakh tonnes from 61.69 lakh tonnes, continuing the pattern of higher sales activity alongside lower earnings measures.
PBIDT for the first six months fell to Rs 438.26 crore from Rs 568.35 crore, while PBT decreased to Rs 168.90 crore from Rs 311.27 crore. This represented Rs 249.00 crore more net sales but Rs 130.09 crore less PBIDT year on year. JK Lakshmi Cement has one business segment, Cementitious Materials, so the filing does not provide a segment-level revenue or profit split.
Got a follow-up? Ask IRIS
How did JK Lakshmi Cement’s debt and cash position change?
JK Lakshmi Cement reported net debt to earnings before interest, tax, depreciation and amortisation, or EBITDA, of 2.31 times at September 30, 2026, compared with 1.25 times a year earlier. Net debt to equity was 0.51 times, compared with 0.38 times in July-September 2025. Both reported leverage ratios increased while quarterly PBIDT declined from Rs 232.86 crore to Rs 164.49 crore.
Standalone cash and cash equivalents were Rs 13.40 crore at September 30, 2026, compared with Rs 65.80 crore at the beginning of the year. For the six months, standalone net cash used in operating activities was Rs 8.11 crore, compared with net cash from operating activities of Rs 355.31 crore a year earlier. Inventory rose to Rs 986.47 crore from Rs 644.85 crore at March 31, 2026, and trade receivables increased to Rs 187.43 crore from Rs 110.83 crore.
What expansion and efficiency projects has JK Lakshmi Cement disclosed?
JK Lakshmi Cement is building a railway siding at its Durg cement plant at a stated cost of Rs 325 crore, funded by Rs 225 crore of debt and the balance through internal accruals. The company said the first phase has been completed. It is also pursuing a Durg expansion comprising a 2.30 million tonnes per annum, or MTPA, clinkerisation line and three grinding units with total cement capacity of 4.6 MTPA.
The Durg capacity project is expected to cost Rs 3,000 crore and be funded through a mix of debt and internal accruals, with completion expected by March 2028. Separately, JK Lakshmi Cement is implementing a phased project at its Sirohi cement plant to raise thermal substitution rate, or TSR, from 4% to 16%. Renewable or green power represented 48% of its power mix during Q2 FY27.
JK Lakshmi Cement stated that its existing combined cement capacity is about 18 MTPA across three integrated plants and four split-location grinding units. Its expansion roadmap covers about 7 MTPA of additional capacity across six locations, which the company expects to take total cement capacity to about 25 MTPA by FY2030. Those capacity figures and dates are company plans, not completed capacity additions.
Conclusion
JK Lakshmi Cement’s Q2 FY27 results showed that sales volume rose by 1.40 lakh tonnes and net sales increased by Rs 85.15 crore year on year, but PBIDT declined by Rs 68.37 crore and PAT fell by Rs 61.45 crore. The first-half comparison showed the same direction, with Rs 249.00 crore higher net sales alongside a Rs 130.09 crore reduction in PBIDT and a Rs 106.35 crore decline in PAT.
Next, readers can watch JK Lakshmi Cement’s stated expectation of improved cement demand in H2 FY27, as well as its commentary on petcoke, freight and packaging costs. The company also plans to complete its Rs 3,000 crore Durg capacity project by March 2028, while an arbitral tribunal has listed a January 6, 2027 hearing on its Rs 130 crore claim linked to the cancelled Assam mining development and operations contract.