










Kirloskar Ferrous Industries Limited Q2 revenue rises 17% year on year
Key highlights
- KFIL’s standalone Q2 FY2027 revenue rose 17% year on year to Rs 2,046.7 crore.
- Steel volume reached a record 26,606 MT, while gross casting sales crossed 50,000 MT in Q2 FY2027.
- Q2 EBITDA increased 4% to Rs 223.0 crore, but the EBITDA margin fell to 10.9% from 12.2%.
- First-half FY2027 profit after tax declined 44% to Rs 179.9 crore, while revenue rose 11% to Rs 3,818.2 crore.
powered by IRIS
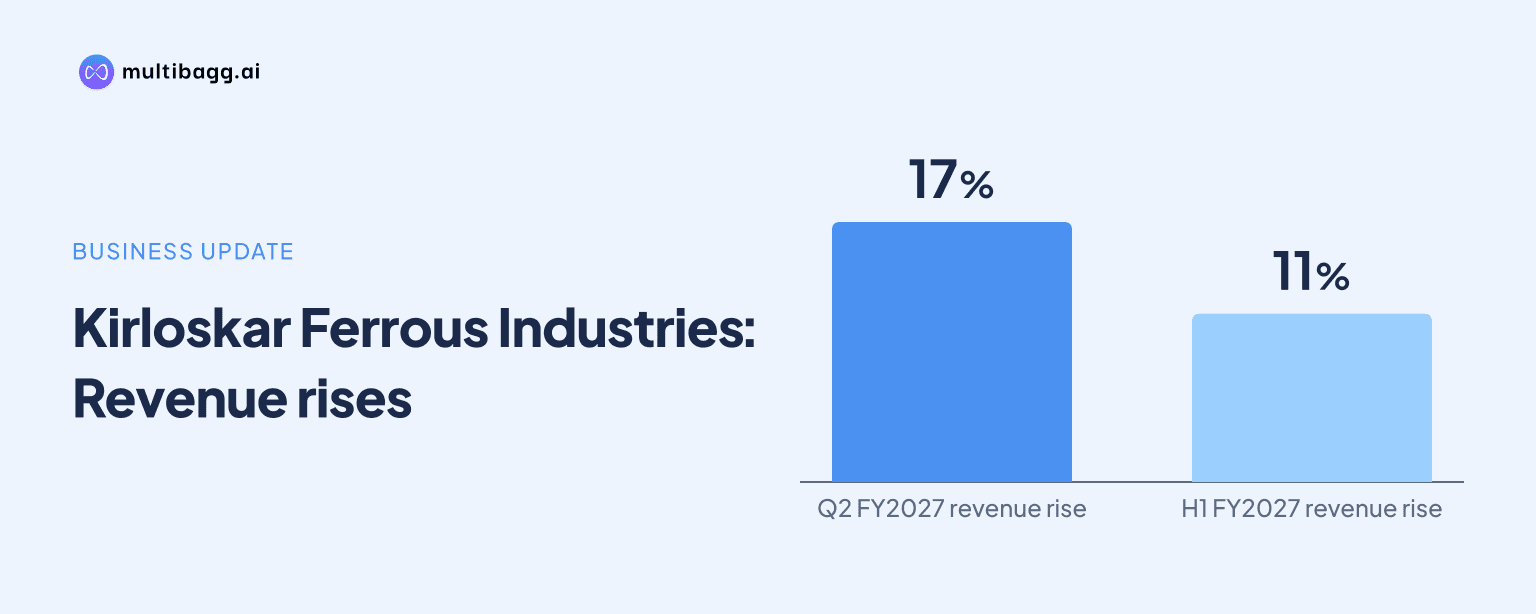
Kirloskar Ferrous Industries Limited reported standalone revenue of Rs 2,046.7 crore for Q2 FY2027, 17% above Q2 FY2026, as steel volume reached a record 26,606 metric tonnes (MT) and gross casting sales crossed 50,000 MT. KFIL’s earnings before interest, tax, depreciation and amortisation (EBITDA) margin was 10.9%, versus 12.2% a year earlier.
Know Kirloskar Ferrous Industries inside out
Results, valuation, peers and who's buying, in one view.
What drove KFIL’s Q2 FY2027 revenue growth?
KFIL’s standalone revenue rose by Rs 291.4 crore to Rs 2,046.7 crore in Q2 FY2027 from Rs 1,755.3 crore in Q2 FY2026. Management attributed the 17% increase to optimised capacity utilisation, citing record steel volume of 26,606 MT and gross casting sales crossing 50,000 MT as the quarter’s operating milestones.
The release reported the same revenue figures on a consolidated basis: Rs 2,046.7 crore in Q2 FY2027 and Rs 1,755.3 crore in Q2 FY2026. KFIL did not disclose revenue by casting, pig iron, steel or seamless-tube product line, so the contribution of each business to the Rs 291.4 crore increase cannot be determined from the announcement.
How did KFIL’s Q2 profit and margins change?
KFIL reported EBITDA before exceptional items of Rs 223.0 crore in Q2 FY2027, up 4% from Rs 214.4 crore a year earlier. Revenue rose 17%, faster than EBITDA, and the EBITDA margin decreased by 1.3 percentage points to 10.9% from 12.2%.
Profit before tax after exceptional items increased 15% to Rs 137.8 crore from Rs 119.9 crore, while profit after tax rose 10% to Rs 97.6 crore from Rs 88.5 crore. Management said cost-management measures helped protect margins despite increases in coking-coal prices and rupee depreciation, without quantifying either movement.
The standalone and consolidated quarterly figures differed slightly for EBITDA, with consolidated EBITDA of Rs 222.98 crore versus standalone EBITDA of Rs 223.0 crore. Consolidated profit before tax was Rs 137.8 crore and consolidated profit after tax was Rs 97.5 crore, compared with standalone figures of Rs 137.8 crore and Rs 97.6 crore respectively.
Got a follow-up? Ask IRIS
What do KFIL’s first-half FY2027 figures show?
KFIL’s standalone revenue for the six months ended 30 September 2026 was Rs 3,818.2 crore, an 11% increase from Rs 3,453.4 crore in YTD FY2026. EBITDA before exceptional items rose 2% to Rs 438.7 crore from Rs 431.3 crore, while the margin declined to 11.5% from 12.5%.
Standalone profit before tax after exceptional items declined 2% to Rs 242.9 crore from Rs 247.1 crore in the previous first half. Profit after tax fell 44% to Rs 179.9 crore from Rs 324.0 crore, contrasting with the 10% increase in quarterly profit after tax during Q2 FY2027.
KFIL said FY2026 comparative figures were restated after the merger of Oliver Engineering Private Limited and Adicca Energy Solutions Private Limited during FY2026-27. It also said a deferred tax asset recognised on the scheme’s appointed date, 1 April 2025, was utilised across previous quarters and the six months ended 30 September 2026; the company said prior-year numbers consequently included an effect from negative tax.
What operating milestones and plans did KFIL disclose?
KFIL reported steel volume of 26,606 MT in Q2 FY2027, calling it a record, and said gross casting sales crossed 50,000 MT. The announcement did not provide Q2 FY2026 steel or casting volumes, so year-on-year volume growth rates cannot be calculated from the disclosed data.
KFIL operates manufacturing facilities at Koppal, Hiriyur, Solapur and Rajpura, with the capability to produce grey-iron castings of up to 1,000 kilograms per piece. Its listed products include SG iron grade, basic steel grade and foundry-grade pig iron; following the merger, its range also extends to ISMT Steel, seamless tubes and alloy steel.
Management said favourable demand signals were encouraging expansion of steel and casting capacity, and that KFIL would focus on newly commissioned solar-energy capacity and key expansion projects to improve cost competitiveness. The 30 October 2026 release did not disclose capital expenditure, planned capacity additions, commissioning dates or expected financial effects for those projects.
Conclusion
KFIL combined a 17% increase in Q2 FY2027 revenue to Rs 2,046.7 crore with record steel volume of 26,606 MT and gross casting sales above 50,000 MT. EBITDA increased 4% to Rs 223.0 crore, but the EBITDA margin declined to 10.9% from 12.2%, while profit before tax increased 15% to Rs 137.8 crore.
The next disclosed developments to watch are management’s planned expansion of steel and casting capacity and its use of newly commissioned solar capacity and expansion projects. Comparisons with FY2026 will also continue to use restated figures following the merger and reflect the disclosed deferred-tax-asset effect dated 1 April 2025.