










PhysicsWallah targets roughly double FY26 pre-Ind AS EBITDA in FY27
Key highlights
- PW reported FY26 revenue of Rs 3,900 crore, up 35% year on year.
- H1 FY27 revenue reached Rs 2,293 crore, up 21%, and Q2 revenue was a record Rs 1,242 crore.
- PW generated Rs 456 crore of H1 FY27 free cash flow after capital expenditure, leases and Sarrthi.
- FY26 pre-Ind AS EBITDA was Rs 300 crore, and management is targeting roughly twice that level in FY27.
powered by IRIS
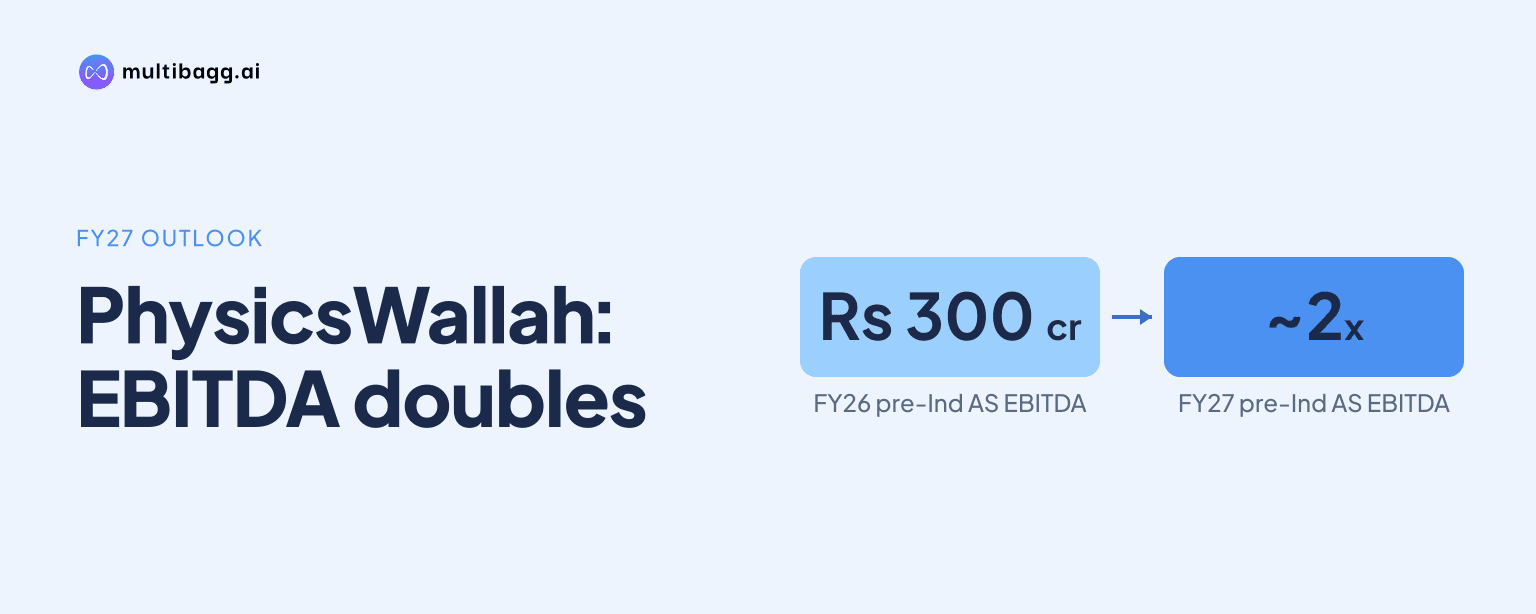
PhysicsWallah targets FY27 pre-Ind AS EBITDA at roughly twice FY26’s Rs 300 crore after generating Rs 456 crore of H1 FY27 free cash flow. Management’s outlook follows 21% H1 revenue growth, a 450-basis-point rise in group EBITDA margin to 8.3%, and Rs 55 crore of H1 profit after tax.
Know Physicswallah inside out
Results, valuation, peers and who's buying, in one view.
What is PW targeting for FY27 profitability?
PW is targeting roughly twice its FY26 pre-Ind AS EBITDA in FY27, after reporting Rs 300 crore in FY26 and a 7.7% EBITDA margin. EBITDA means earnings before interest, tax, depreciation and amortisation. The FY27 target is management’s outlook rather than a reported result, following Rs 94 crore of EBITDA and a 3.2% margin in FY25.
The first-half result provides the basis for that plan: group H1 FY27 EBITDA margin was 8.3%, up 450 basis points year on year, while profit after tax, or PAT, was Rs 55 crore compared with a Rs 57 crore loss a year earlier. PW also said FY27 is expected to be its first full year of reported profit as a listed company. Its quarterly pattern remains seasonal, with pre-Ind AS EBITDA improving from a Rs 43 crore loss in Q1 FY27 to a record Rs 233 crore in Q2.
How fast is PW's revenue engine growing?
PW reported FY26 revenue of Rs 3,900 crore, up 35% from Rs 2,887 crore in FY25 and at the upper end of its earlier 32% to 35% guidance range. Revenue increased from Rs 233 crore in FY22, while annual growth moderated from 219% in FY23 and 161% in FY24 as the revenue base expanded.
H1 FY27 revenue was Rs 2,293 crore, including 29% online growth and 34% growth in core online operations. Q2 FY27 revenue reached Rs 1,242 crore, PW’s highest quarterly level. In FY26, PW reported online revenue of Rs 2,011 crore, or 52% of the mix, and offline revenue of Rs 1,844 crore, or 47% of the mix.
How did PW generate H1 FY27 free cash flow?
PW generated Rs 828 crore of operating cash flow in H1 FY27 and Rs 456 crore of free cash flow after capital expenditure, leases and Sarrthi. H1 operating cash flow was close to the Rs 833 crore reported for all of FY26, following Rs 507 crore in FY25 and Rs 212 crore in FY24. The presentation states that collections lead revenue recognition through the academic year.
FY26 collections were about Rs 4,200 crore against Rs 3,900 crore of revenue, while group fees received in advance stood at Rs 1,731 crore on 30 September, compared with Rs 1,209 crore in March. PW separately reported Rs 1,040 crore of online liabilities against Rs 175 crore of online assets on 30 September, and Rs 521 crore of online EBITDA in FY26. Treasury was Rs 5,268 crore on 30 September, compared with more than Rs 2,500 crore before listing.
Got a follow-up? Ask IRIS
Which operating changes support PW's margin plan?
PW’s cost ratios declined while revenue rose 21% in H1 FY27. Operating expenses plus leases were 91.7% of revenue, down 450 basis points year on year; employee costs excluding employee stock-option-plan expense were 42.3%, down 235 basis points; and other costs were 23.4%, down 114 basis points. Marketing expense was 9.4% of H1 revenue, down from 10.6% in H1 FY26, while management indicated a 7% to 8% level at scale.
PW increased technology spending to Rs 104 crore in H1 from Rs 70 crore, with the spending directed towards artificial intelligence, or AI. It reported that AI resolved 80% of student-support queries and that guided AI tutoring reduced cost per question by 84%. Faculty increased 7% and total headcount increased 4%, below revenue growth. In Vidyapeeth centres, students per teacher rose from 69 in FY24 to 79 in FY26, while faculty cost declined from Rs 18.8 lakh to Rs 16.3 lakh.
PW disclosed 56 centres in H1, compared with 128 in its prior expansion reference, and said it now plans 25 to 30 openings a year. Its capital-allocation framework requires an offline centre to be on track for a 13% to 15% margin at maturity. The 2022, 2023 and 2024 centre cohorts were at break-even or better in FY26, with margins of 3%, 0% and 2%, respectively; the 2025 cohort had a 6% loss. H1 capital expenditure was Rs 157 crore for fit-outs and technology.
Conclusion
PW’s FY27 outlook combines management’s target for roughly double FY26 pre-Ind AS EBITDA with first-half results of Rs 2,293 crore in revenue, Rs 456 crore in free cash flow and Rs 55 crore in PAT. Compared with FY26, percentage revenue growth was lower, but group cost ratios declined and H1 operating cash flow nearly matched the prior full-year total within six months.
The next disclosed markers are the seasonal second-half quarters, when PW says revenue and margins typically peak in Q3 and Vishwas Divas collections occur in Q4. PW also plans 25 to 30 annual centre openings subject to its 13% to 15% maturity-margin hurdle, while its staged-control plan includes increasing Sarrthi ownership to 85% by FY31.