










Pyramid Technoplast Limited expects Rs 15 crore solar savings
Key highlights
- Pyramid Technoplast recorded approximately Rs 3.89 crore of solar savings in H1 FY27.
- Pyramid Technoplast expects around Rs 15 crore of annual savings from 14.25 MW of solar capacity.
- Pyramid Technoplast has invested Rs 60 crore in solar and estimates a payback of about four years.
- Pyramid Technoplast’s H1 FY27 EBITDA rose 55% year on year to Rs 41.6 crore, with margin at 9%.
powered by IRIS
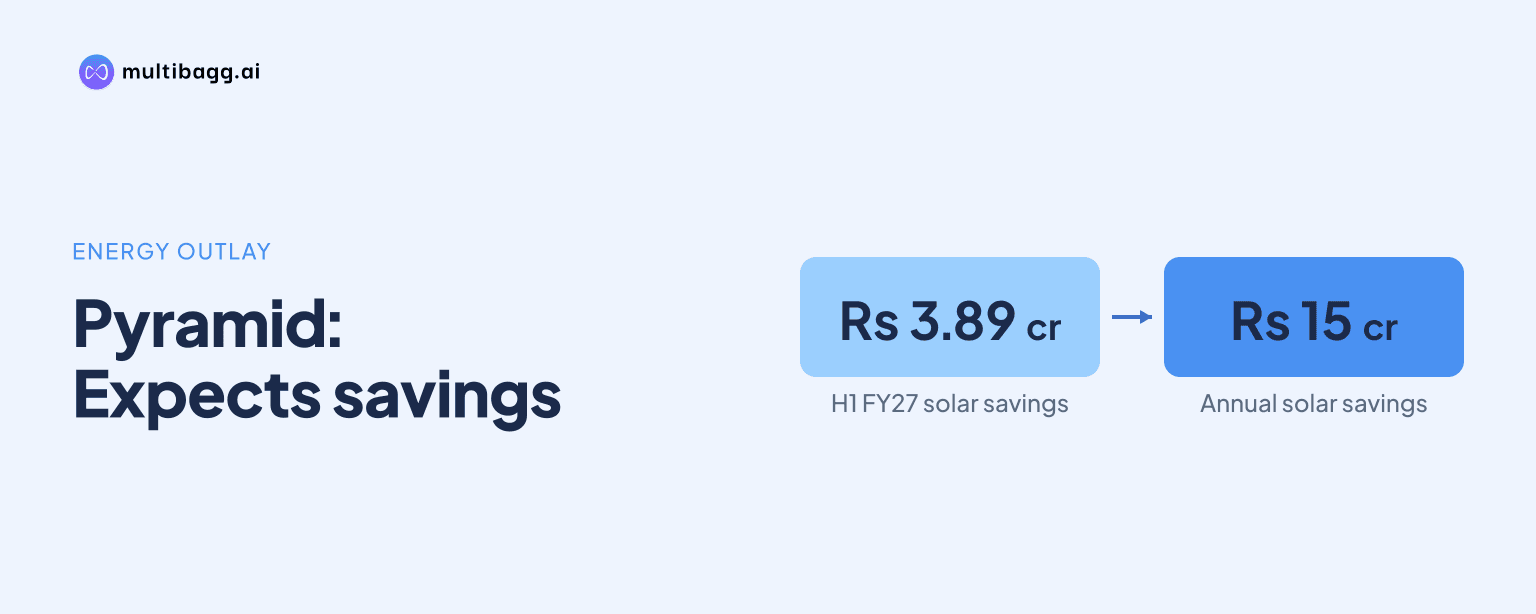
Pyramid Technoplast Limited expects its Rs 60 crore, 14.25-megawatt solar programme to deliver around Rs 15 crore of annual savings at full capacity, after recording approximately Rs 3.89 crore of savings in H1 FY27. Management estimated the project’s payback at about four years during its November 6, 2026 earnings call.
Know Pyramid Technoplast inside out
Results, valuation, peers and who's buying, in one view.
What does Pyramid Technoplast’s solar programme include?
Pyramid Technoplast’s solar programme comprises 14.25 megawatts, or MW, of capacity across Maharashtra and Bharuch, with 13.25 MW already commissioned by the time of the H1 FY27 call. Management said a 6 MW plant and 2.25 MW in Maharashtra were commissioned in October 2025, followed by a 5 MW Bharuch plant in February 2026.
The final 1 MW at Bharuch was in installation and pre-charging as of November 6, 2026. Management said the installation and pre-charging work had been completed and expected that unit to begin providing benefits in the following month. The full-capacity annual-savings estimate therefore depends on this last phase starting to contribute.
Solar forms part of a wider efficiency and capacity programme. Pyramid Technoplast said its Wada facility was operating across small packaging drums, intermediate bulk containers, or IBCs, and mild-steel drums, while a Kutch project is intended to add capacity of 10,000 IBCs per month by March 2027. The company said the Kutch site is designed to lower freight costs, speed deliveries and improve service in western India.
How much does Pyramid Technoplast expect to save from solar?
Pyramid Technoplast expects around Rs 15 crore of annual savings from the complete 14.25 MW solar programme, against approximately Rs 3.89 crore recorded in H1 FY27. Management put the total investment at Rs 60 crore and estimated that the programme would repay this investment in about four years.
The gap between H1 savings and the annual estimate reflects the commissioning timetable disclosed by management. The 5 MW Bharuch addition had been commissioned in February 2026, while the final 1 MW had not yet started delivering benefits at the November 2026 call. Pyramid Technoplast did not disclose savings by plant, electricity consumption, or a quarterly run-rate target.
Management identified the full benefit of solar savings as one of four levers for improving profitability in the second half of FY27. The other three were higher capacity utilisation, a larger contribution from the recycling plant, and operating leverage alongside product mix. These were management’s stated factors rather than a quantified allocation of the Rs 15 crore savings target.
Got a follow-up? Ask IRIS
How are solar savings linked to Pyramid Technoplast’s FY27 earnings?
Solar savings are expected to support FY27 margins, but Pyramid Technoplast did not separately quantify their contribution to reported earnings. H1 FY27 revenue rose 42% year on year to Rs 460.5 crore, while earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 55% to Rs 41.6 crore and the EBITDA margin rose to 9% from 8.2% a year earlier.
In Q2 FY27, revenue rose 48% year on year to Rs 238 crore and EBITDA increased 61% to Rs 20.3 crore. The EBITDA margin was 8.5%, compared with 7.8% in Q2 FY26. Management attributed the revenue increase to a 22% rise in average realisation to about Rs 1.61 lakh per tonne and a 21% increase in volume.
The asset build-out also affected below-EBITDA charges in Q2 FY27. Pyramid Technoplast said finance costs increased 147% year on year and depreciation rose 37%, citing expanded capacity and the solar investment. Even so, profit before tax rose 53% to Rs 12.5 crore and profit after tax rose 54% to Rs 9.5 crore.
Management’s FY27 objective is about 15% revenue growth and an EBITDA margin of 11% to 12%. During the call, management said it expected the core business to reach about a 9.5% margin, with a further 1.5 percentage points from government subsidies. Solar was described as a margin lever, but management did not say that the subsidy-related improvement would come from solar.
What operating factors could affect Pyramid Technoplast’s savings plan?
The immediate factor is the final 1 MW Bharuch solar unit beginning to contribute after its pre-charging stage. Management expected benefits to begin in the month following the November 6, 2026 call, but did not give a specific commissioning date or the savings expected from that unit. The four-year payback is management’s estimate for the programme as a whole.
Factory utilisation is another factor management linked to second-half operating leverage. Q2 FY27 capacity utilisation was about 70%, compared with 62% in Q1 FY27 and 62% in Q2 FY26. H1 FY27 volume was 27,789 metric tonnes at average utilisation of about 66%, and management expected overall Wada utilisation to reach around 80% during FY27.
Freight costs remain relevant to the broader cost base despite the solar savings programme. Management said about Rs 2 crore of a sequential increase in other expenses came from transportation costs for long-distance dispatches. The planned Kutch IBC facility, with FY27 capital expenditure of about Rs 20 crore to Rs 25 crore, is intended to move production closer to customers and reduce freight costs after its expected March 2027 commissioning.
The recycling facility is a separate earnings initiative. Commissioned in October 2025 with investment of around Rs 8 crore to Rs 10 crore, it generated Rs 33 lakh of EBITDA in Q2 FY27. Management expects approximately Rs 2 crore of FY27 EBITDA from recycling and estimated a two- to three-year payback as volumes increase.
Conclusion
Pyramid Technoplast has provided a defined framework for its solar investment: Rs 60 crore of spending, approximately Rs 3.89 crore of H1 FY27 savings, around Rs 15 crore of expected annual savings and an estimated four-year payback. The programme is being introduced alongside higher output, with H1 FY27 EBITDA of Rs 41.6 crore and a 9% margin, up from 8.2% a year earlier.
The next disclosed milestone is the expected start of benefits from the remaining 1 MW Bharuch solar phase in the month after the November 2026 call. Investors can also track whether Wada utilisation reaches management’s 80% FY27 expectation, whether the Kutch IBC facility is commissioned by March 2027, and whether the company progresses toward its stated 11% to 12% FY27 EBITDA-margin objective.