










Repco targets Rs 3,000-3,050 crore H2 disbursements
Key highlights
- Repco reported Rs 1,205 crore of September 2026-quarter disbursements, up from Rs 1,069 crore a year earlier.
- Repco targets approximately Rs 3,000-3,050 crore of disbursements across H2 FY2027.
- Repco's assets under management were Rs 16,425 crore at September 2026, up about 9-9.2% year on year.
- Repco's gross non-performing assets were Rs 396 crore, or 2.4% of assets under management, at September 2026.
powered by IRIS
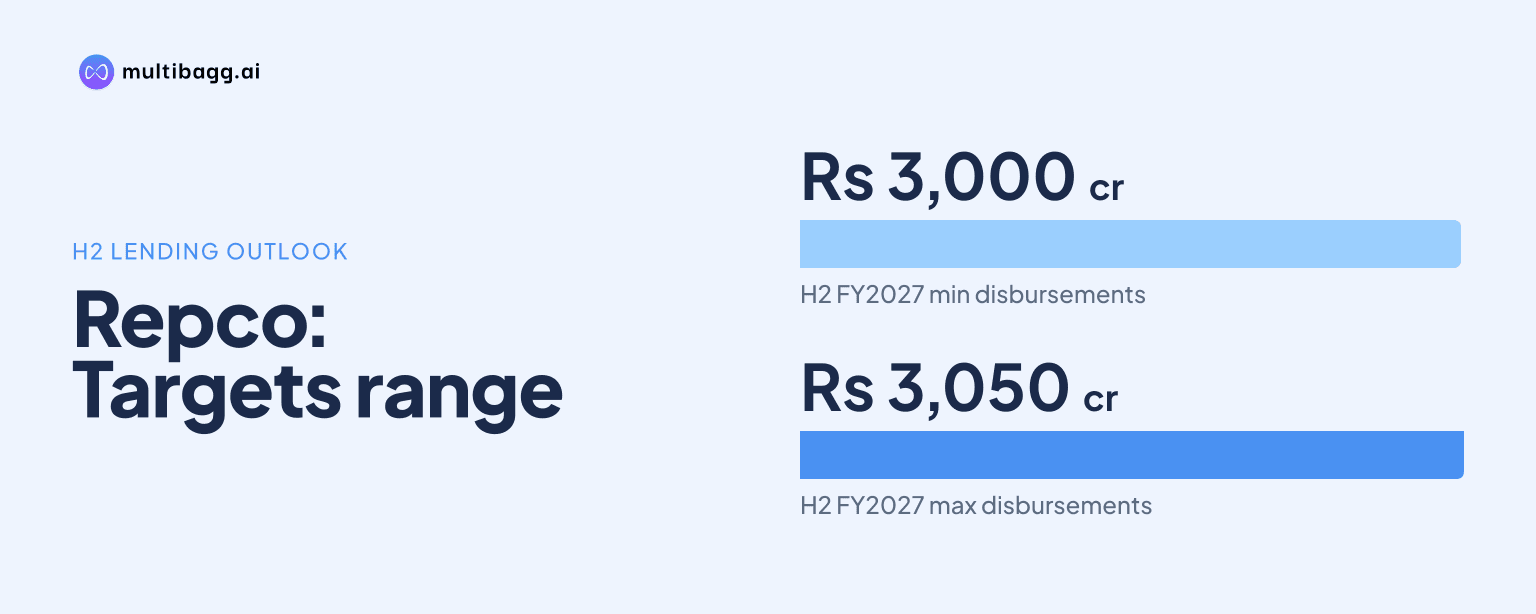
Repco Home Finance Limited is targeting Rs 3,000-3,050 crore of disbursements in the second half of financial year 2027 (H2 FY2027), after disbursements reached Rs 1,205 crore in the quarter ended September 2026, up Rs 136 crore year on year. Management linked the plan to dedicated sales and credit channels, broader sourcing and completed staff transfers.
Know Repco Home Finance inside out
Results, valuation, peers and who's buying, in one view.
How much does Repco plan to disburse in H2 FY2027?
Repco plans Rs 1,300-1,350 crore of disbursements in Q3 FY2027 and Rs 1,650-1,700 crore in Q4 FY2027, producing an approximately Rs 3,000-3,050 crore H2 target. The Q4 range is higher than the Q3 target, indicating that management expects business volumes to build through the second half.
The H2 target exceeds the Rs 2,048 crore disbursed in the first half, based on Rs 843 crore in the June 2026 quarter and Rs 1,205 crore in the September 2026 quarter. Management said the June-quarter outcome was below its approximately Rs 1,000 crore target because transfers and promotions affected activity, while staff subsequently settled into their new roles.
September-quarter disbursements were Rs 136 crore above the Rs 1,069 crore reported in the corresponding quarter a year earlier. Sanctions, or approved loans, rose to Rs 1,359 crore from Rs 1,205 crore over the same comparison, increasing the value of approved business before disbursement.
Management said October disbursements and business achieved through the November 6 earnings call were in line with the Q3 target, but did not disclose an October amount. It also said quarterly disbursements had exceeded Rs 1,000 crore since September 2025, except in the June 2026 quarter.
What changed in Repco's sales and operating model?
Repco said its organisational changes and sourcing expansion support its expectation that Q3 disbursements will exceed Q2 levels. The company moved functions previously handled by branch heads into dedicated sales, recovery, collections, operations and credit verticals, separating responsibilities that management said had earlier overlapped.
Chief Business Officer M. Raja said independent sales and credit channels had sharpened the focus on business generation. Management also said it expanded sourcing channels, recruited additional sales personnel and introduced a connector model, following the Q1 FY2027 staff transfers and promotions that affected June-quarter activity.
Repco has also implemented core and mobile applications as part of a two-phase digitalisation programme. It said the core systems were integrated with external systems to improve turnaround time, while the second phase covers supporting applications; management did not provide a completion date for that phase.
The physical network is expanding alongside the channel changes. Repco had 242 branches, including satellite centres, at September 2026 and plans to add 13-14 branches in FY2027, mainly outside Tamil Nadu, after opening about 50 branches nationally over the prior two to three years.
Got a follow-up? Ask IRIS
Can Repco grow disbursements while maintaining asset quality?
Repco said it will seek higher disbursements without diluting asset quality and is maintaining its target to reduce gross non-performing assets below 2% by the end of FY2027. Gross non-performing assets stood at Rs 396 crore, or 2.4% of assets under management, at September 2026, compared with Rs 475 crore a year earlier.
Stage 2 assets, loans classified as having higher credit risk, declined to Rs 1,154 crore at September 2026 from Rs 1,324 crore in the corresponding period a year earlier. Repco reported a 66% provision coverage ratio and said it had applied provision reversals associated with lower non-performing assets to other impaired accounts rather than releasing them to profit.
The loan-book mix was broadly unchanged. Non-salaried borrowers accounted for 53.6% of assets under management at September 2026 and salaried borrowers represented 46.4%, while housing loans made up 71% and non-housing loans the remaining 29%.
Repco said it had no builder-loan exposure and retained its entire assets-under-management book. Incremental loans had an average ticket size of Rs 23-25 lakh, against about Rs 14 lakh for the overall book, while Tamil Nadu accounted for 57% of the portfolio; management expects business from other states to increase.
What funding and earnings factors support Repco's growth plan?
Repco reported assets under management of Rs 16,425 crore at September 2026, up about 9-9.2% year on year, and capital adequacy of about 37%. Management said the capital position was adequate for its planned expansion, while the overall cost of borrowings was 8.35% and net interest margin was 5.44% at September end.
Banks supplied 86% of borrowings and the funding was spread across about 19-20 banks. National Housing Bank refinance accounted for 7.2%, and Repco had drawn Rs 231 crore by Q2 FY2027 from a Rs 600 crore facility sanctioned for the financial year.
The company raised Rs 75 crore through commercial papers in Q2 at 7.6% and completed a Rs 74 crore pass-through certificate transaction in September at a funding cost of 7.9%. Management said liabilities were almost entirely floating rate, except for a small special-rate National Housing Bank component, while all loans were floating rate and repriced with a three-month lag.
Net profit was about Rs 116 crore in the September 2026 quarter, compared with Rs 114 crore in the June quarter and about Rs 106 crore a year earlier. Management expects FY2027 profit of about Rs 480-490 crore and expects provision charges of Rs 5-6 crore in each of the remaining two quarters; these are management expectations rather than reported results.
Conclusion
The disclosed figures show a plan to convert higher sanctioned loans, channel specialisation and a wider branch network into faster loan growth while retaining a separate focus on collections and credit controls. September sanctions of Rs 1,359 crore, up from Rs 1,205 crore a year earlier, provide a larger approved-loan base than in the comparable quarter.
The next measures to watch are delivery against the Rs 1,300-1,350 crore Q3 FY2027 target and progress toward management's below-2% gross non-performing asset target, from 2.4% at September 2026. Repco also plans 13-14 new branches in FY2027, mostly outside Tamil Nadu, and intends to use National Housing Bank refinance according to funding needs.