










Repco Home Finance targets 3.25-3.3% spread as costs rise
Key highlights
- Repco Home Finance expects overall funding costs to rise by 10-15 bps from the 8.35% reported at September-end.
- Management targets a 3.25% to 3.3% spread, compared with about 3.4% at September-end.
- Repco Home Finance has a Rs 600 crore NHB refinancing sanction and had drawn Rs 231 crore across the first two quarters.
- Management guided for Rs 1,300 crore to Rs 1,350 crore of third-quarter disbursements and gross NPA below 2% by year-end.
powered by IRIS
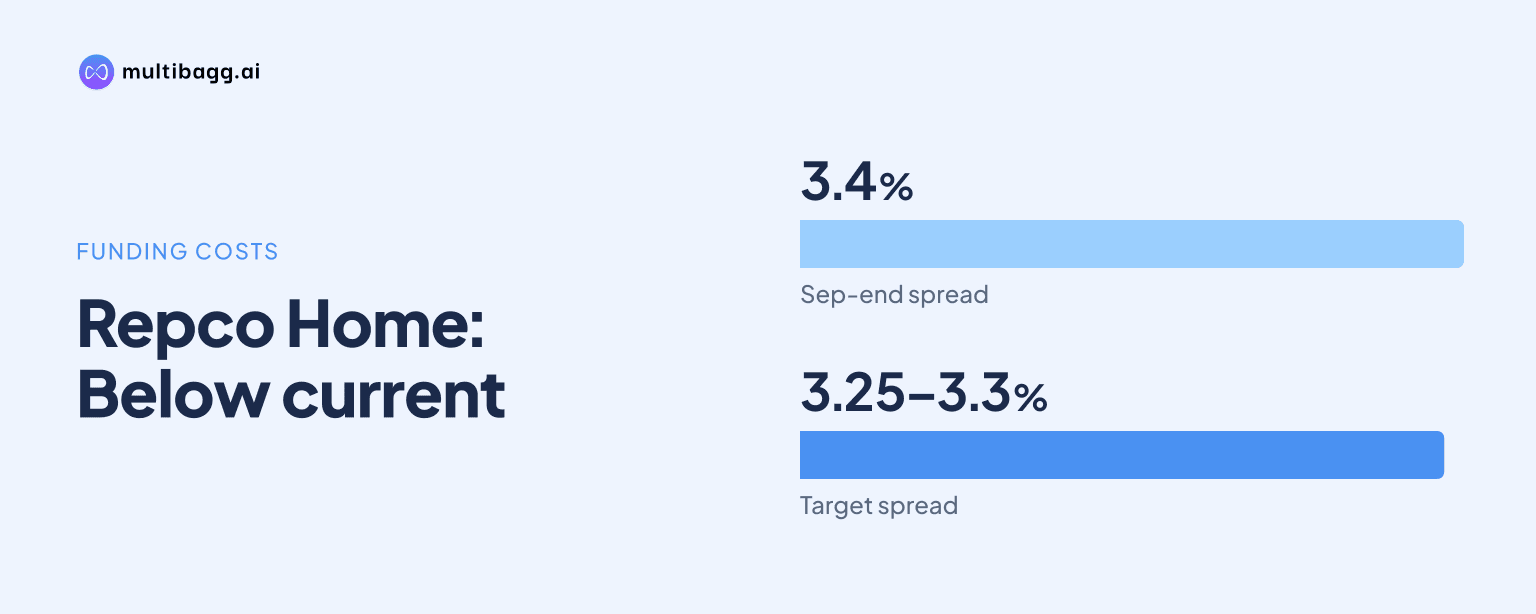
Repco Home Finance Limited expects its overall cost of funds to rise by 10 to 15 basis points after the rate increase, but management said on November 6, 2026 that it intends to maintain a spread of about 3.25% to 3.3%, versus about 3.4% at September-end, through quarterly loan repricing, refinancing and selective customer concessions.
Know Repco Home Finance inside out
Results, valuation, peers and who's buying, in one view.
How will Repco Home Finance protect its spread?
Repco Home Finance said it can pass higher borrowing costs to customers with a lag of about one quarter because its entire loan book is floating rate and is repriced once every three months. Management said almost all liabilities are also floating rate, except for a small amount of National Housing Bank, or NHB, funding under a special-rate scheme.
The expected 10 to 15 basis point, or bps, increase in funding cost follows the rise in borrowing costs management said it had seen after the Reserve Bank of India rate hike. Repco Home Finance reported an overall cost of funds of 8.35% at September-end and a spread of about 3.4%, while management’s near-term 3.25% to 3.3% target incorporates both higher funding costs and retention concessions.
Management said concessions would be selective, applying to customers with at least two years of repayment history, a good CIBIL score and a risk of moving their loan elsewhere. The policy is intended to control balance-transfer outflows, or BT Out, but means the company does not expect loan-rate increases alone to offset all pressure on its spread.
Repco Home Finance reported a return on assets of about 2.9% at September-end, unchanged from the June quarter, and return on equity of about 12.5%. Its net interest margin, or NIM, was about 5.44% at September-end, a separate measure from the 3.4% spread management discussed in relation to borrowing costs and loan yields.
What do Repco Home Finance loan yields show?
Repco Home Finance’s September yields were higher for non-salaried customers than salaried customers, and higher for non-housing loans than the housing portfolio. Its minimum lending rate was about 9.9%, although the actual rate varied by borrower risk profile.
The 13.32% yield on non-housing loans was 2.25 percentage points above the 11.07% average yield on the housing portfolio. Similarly, the 12.07% average yield from non-salaried customers was 0.82 percentage points above the 11.25% yield from salaried customers.
Those differences set the reported yield position before the expected 10 to 15 bps increase in funding costs. Management’s 3.25% to 3.3% spread target also reflects its plan to offer some pricing benefits to established customers who meet its stated repayment and credit-score conditions.
Got a follow-up? Ask IRIS
How much NHB refinancing can Repco Home Finance access?
Repco Home Finance has an NHB refinancing sanction of Rs 600 crore, of which it had drawn Rs 106 crore in the first quarter and Rs 125 crore in the second quarter. Management said it would access the remaining sanctioned amount according to funding requirements as part of its plan to diversify liabilities and reduce its overall cost of funds.
Management did not specify the pricing or a timetable for the remaining NHB drawdown. It said NHB had liberalised some schemes and that it expected more sanctions, while identifying additional NHB refinance as a priority for reducing funding costs.
Other disclosed borrowing activity provides a comparison with the 8.35% overall funding cost at September-end. Repco Home Finance issued commercial paper at 7.6% and completed a Rs 74 crore pass-through certificate in September at a funding cost of about 7.9%.
The company’s capital adequacy ratio was close to 37% at September-end, which management said provided adequate capital for growth. Management’s funding plan combines the NHB facility with market borrowings and loan repricing rather than assigning the spread target to any single funding source.
What else could affect Repco Home Finance margins?
Repco Home Finance’s ability to keep spread within management’s 3.25% to 3.3% range will also depend on business growth, customer retention, operating costs and credit charges. Management guided for disbursements of about Rs 1,300 crore to Rs 1,350 crore in the third quarter and Rs 1,650 crore to Rs 1,700 crore in the fourth quarter.
The company crossed Rs 1,200 crore of disbursements by September after disbursing about Rs 843 crore in the June quarter. Management attributed its confidence in higher third- and fourth-quarter disbursements to expanded direct selling team and direct selling agent channels, a connector model, separate sales and credit channels, and a revised incentive structure.
Operating expenditure increased in the September quarter because Repco Home Finance paid June-quarter incentives together with September-quarter incentives after June disbursements fell short of a roughly Rs 1,000 crore target. Management also cited actuarial valuations for gratuity and leave encashment, recruitment of branch sales managers and recovery staff, and annual staff increments of 5% to 10%.
Management said the cost-to-income ratio should remain stable at the reported level despite the higher salary and sourcing costs. Direct selling agent payouts also rose as disbursements increased from Rs 843 crore in the June quarter to Rs 1,205 crore in the September quarter.
Asset quality remains relevant because management expects provision charges of Rs 5 crore to Rs 6 crore in each of the current and next quarters discussed on the call. Gross non-performing assets, or NPA, were about 2.4% at September-end, compared with about 8% after the November 2021 Reserve Bank of India circular, and management targets a level below 2% by year-end.
Conclusion
Repco Home Finance is planning for a moderate reduction in spread from about 3.4% at September-end to 3.25% to 3.3%, rather than assuming higher funding costs can be offset immediately. The principal mechanism is three-monthly repricing of its floating-rate loan book, supported by NHB refinancing and selective concessions intended to contain BT Out.
The next measures to watch are whether funding costs rise within management’s stated 10 to 15 bps range, how much of the Rs 600 crore NHB sanction is drawn, and whether third-quarter disbursements reach Rs 1,300 crore to Rs 1,350 crore. Management also targets gross NPA below 2% by year-end and said it expects that outcome could support a rating upgrade and improved market-borrowing pricing.