










S.P. Apparels sees UK FTA fashion parity, basics lag
Key highlights
- SPAL said the UK FTA puts India at landed-cost parity with Bangladesh for value-added fashion apparel.
- SPAL said Bangladesh remains more efficient in basic volume orders that can run to several hundred thousand units.
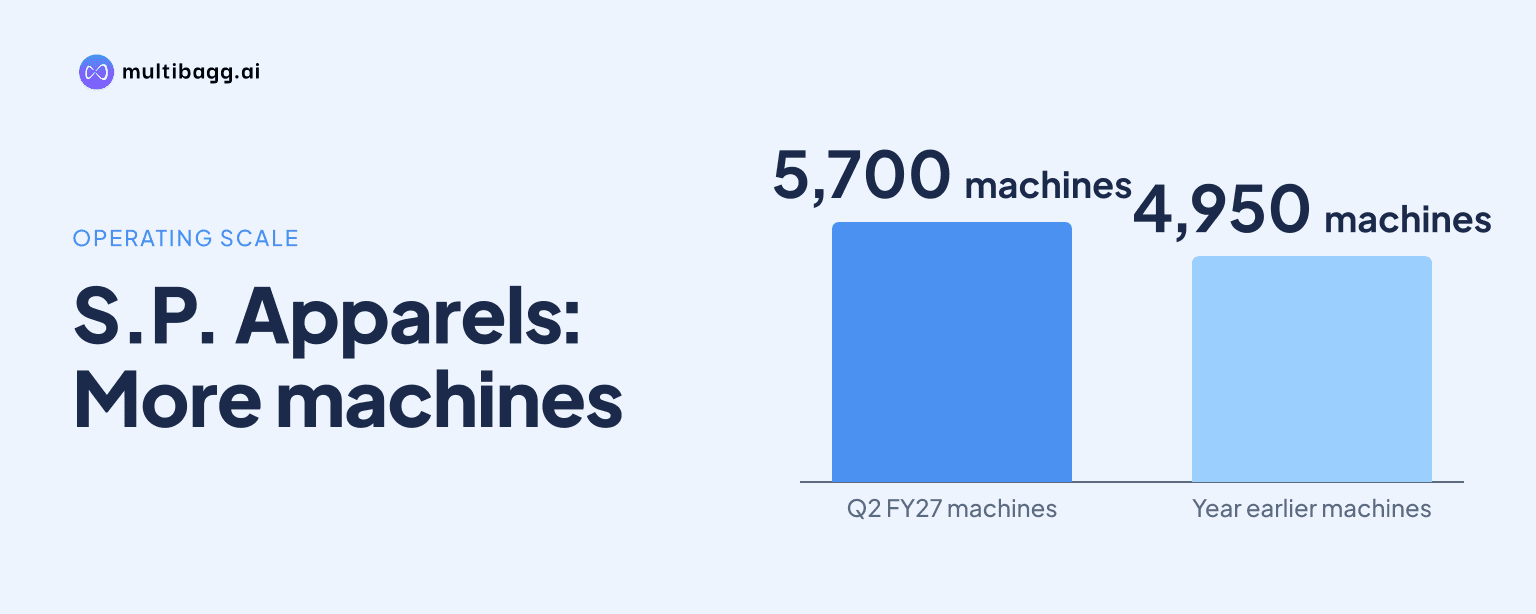
- SPAL operated 5,700 machines at 74% utilisation in Q2 FY27, compared with 4,950 machines a year earlier.
- SPAL reported Garment division adjusted EBITDA of Rs 123.6 crore and a 16.8% margin in H1 FY27.
powered by IRIS
S.P. Apparels said in its H1 FY27 call that the UK FTA has brought India’s landed import cost to parity with Bangladesh for value-added fashion apparel, while Bangladesh remains ahead in basic volume lines that can run to several hundred thousand units because of its manufacturing efficiency.
Know S P Apparels inside out
Results, valuation, peers and who's buying, in one view.
Does the UK FTA put SPAL at parity with Bangladesh?
Yes, SPAL said the UK FTA has put India’s import landed cost at par with Bangladesh for fashion and value-added apparel. Management said this created a level playing field between India, Bangladesh and Sri Lanka for these products, after customers began seeking to reduce their sourcing risk in Bangladesh.
SPAL’s statement was specifically about landed cost, not a disclosed tariff rate or a change in its selling prices. Management said it had received good inquiries after the FTA and that customers were asking it to increase capacity, but it did not disclose customer numbers, order values or converted orders in H1 FY27.
The company had 5,700 machines in Q2 FY27, compared with 4,950 machines in the corresponding quarter a year earlier, and operated at 74% utilisation. Management said the extra capacity was already in place and that higher utilisation in the second half would support revenue growth and fixed-cost absorption as orders ramp up.
Why does Bangladesh retain an edge in basic apparel?
Bangladesh retains an edge in basic apparel because SPAL said its production efficiency remains higher for very large-volume runs. Management described fashion orders as comparatively smaller, while basic and core product orders can run to several hundred thousand units, making scale efficiency more important.
SPAL therefore did not present the FTA as removing Bangladesh’s advantage across all garment categories. Management said India was competitive in fashion products but that Bangladesh continued to be stronger in volume products, despite the FTA’s effect on landed cost.
Management said India could eventually reach Bangladesh’s cost position in volume lines as well, but did not attach a date, capacity plan or financial target to that expectation. The nearer operational metric was Q2 FY27 utilisation of 74% across 5,700 machines, with management expecting customer orders in H2 FY27 to improve plant loading.
The distinction also limits how the company’s inquiry pipeline should be interpreted. Good post-FTA inquiries may be most relevant to value-added fashion work, rather than to the high-volume basics where Bangladesh’s production efficiencies remain a stated competitive advantage.
Got a follow-up? Ask IRIS
Are customers moving fashion-apparel orders to SPAL?
SPAL said customers are moving some quantity to India to reduce Bangladesh-related risk and that it has received good inquiries following the FTA. Management said customers were asking for more capacity, but did not quantify the amount of business transferred, the number of buyers involved or the revenue expected from those inquiries.
SPAL said Young Brand Apparels would seek UK and European customers rather than add other US customers. Management said it intended to capture growth from existing customers under the preferential tariff arrangement, while adding one or two UK customers to diversify Young Brand Apparels’ geographic exposure.
Young Brand Apparels was expected to have 1,500 machines across its units by March, according to management. Its Salem facility had 40 operating machines after production began in August, with the company planning to reach 300 machines within six months through trial orders, training and phased installation.
The group’s second-half plan also depends on recovery in its base business. Management said yarn’s 20% contribution had affected the Avinashi business by about 20% in Q1 and Q2, but said Q3 and Q4 would improve as US customers had returned. That recovery is separate from the UK FTA opportunity, although both affect utilisation and revenue conversion.
How do Sri Lanka operations affect SPAL’s garment margins?
Sri Lanka operations reduced SPAL’s overall garment margin because that business does not receive the 6.5% duty-drawback benefit available elsewhere and was delivering about a 10% margin, management said. SPAL referred to around Rs 60 crore of Sri Lanka revenue when explaining the mix effect and said pre-operative issues were also affecting profitability.
Management said those pre-operative challenges should be resolved within two to three months. It guided for a 15% earnings before interest, tax, depreciation and amortisation (EBITDA) margin for the Garment division, covering SPAL and Sri Lanka, while expecting greater Sri Lanka revenue to dilute fixed overheads.
The Garment division, including Young Brand Apparels, reported adjusted EBITDA of Rs 123.6 crore in H1 FY27, with a margin of 16.8%, compared with 15.9% in H1 FY26. Young Brand Apparels reported adjusted EBITDA of Rs 30.7 crore, up 34.7% year on year, while consolidated EBITDA rose 9.8% to Rs 128 crore and the consolidated margin rose to 15% from 14%.
Sri Lanka’s FY27 revenue outlook has been reduced from the earlier expectation of Rs 190 crore to a range of Rs 150 crore to Rs 170 crore because of the US issue and a delayed customer approval for one of four factories. Management said the fourth factory was under sale-out and that its first shipment could begin in April 2027.
SPAL maintained its expectation of Rs 400 crore of Sri Lanka revenue in FY28 once the fourth facility receives approval and free-on-board orders reach full utilisation. Management also said it planned to add two Sri Lanka factories, or capacity equivalent to 1,000 machines, in the following year.
Conclusion
SPAL’s reported FTA opportunity is narrow but specific: management sees India at landed-cost parity with Bangladesh in value-added fashion apparel, while Bangladesh remains more efficient in high-volume basic lines. The company’s H1 FY27 results show improving group profitability, with consolidated EBITDA rising 9.8% to Rs 128 crore, but the commercial benefit will depend on converting inquiries into factory utilisation and shipments.
The next measures to watch are utilisation above the 74% reported in Q2 FY27, conversion of UK and European customer additions at Young Brand Apparels, and the planned April 2027 first shipment from Sri Lanka’s fourth factory. Management also said it may achieve 95% of its Rs 2,000 crore FY27 revenue guidance, while maintaining its Rs 400 crore FY28 Sri Lanka revenue expectation.