










Tanfac Industries Raises FY27 Revenue Growth Guidance to 35-40%
Key highlights
- Tanfac Industries raised FY27 revenue growth guidance to 35-40% from 30%.
- Tanfac Industries reported Q2 FY27 revenue of ₹234.3 crore, up 38.9% year-on-year.
- H1 FY27 revenue was ₹422.4 crore, up 21.9% year-on-year.
- The ₹495 crore HFC-32 plant has 20,000 tonnes of annual capacity and is targeted for Q3 FY27 commissioning.
powered by IRIS
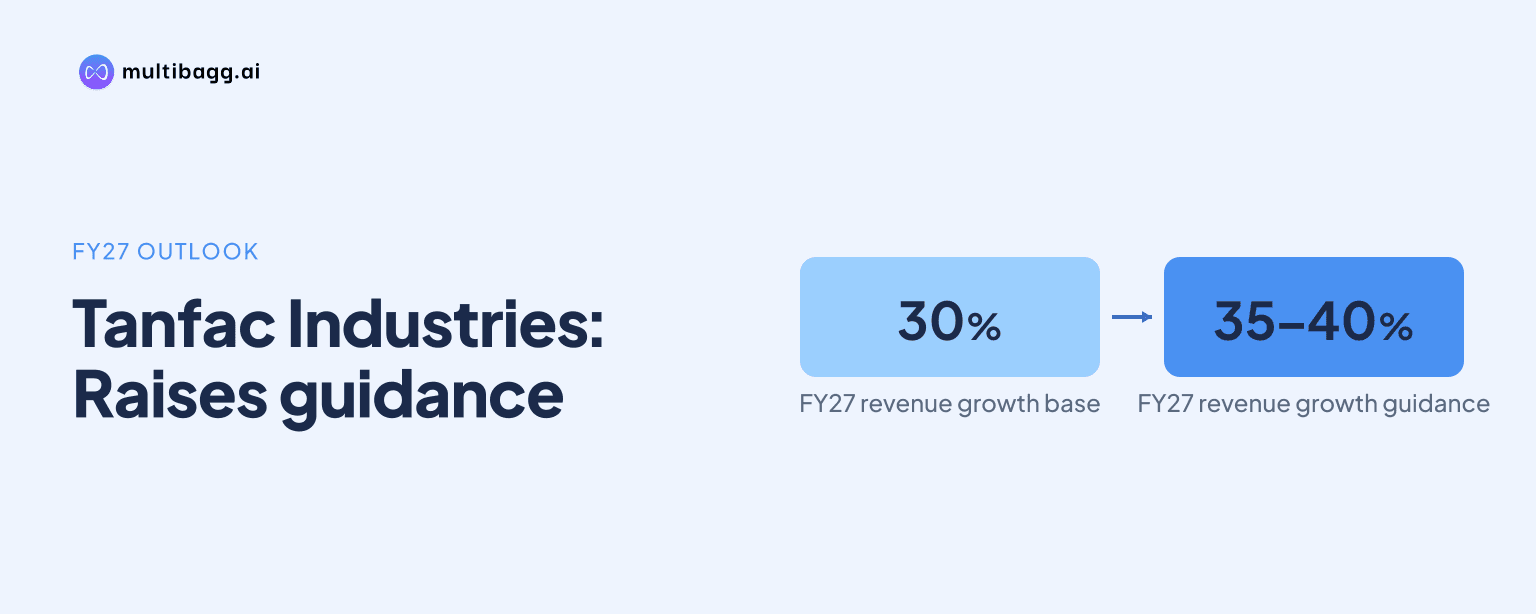
Tanfac Industries Limited raised its FY27 revenue growth guidance to 35-40% from 30% after reporting Q2 FY27 revenue of ₹234.3 crore, a 38.9% year-on-year increase. The revised outlook reflects management’s expectations from realisation growth, specialty products and the planned commercialisation of its HFC-32 project.
Know Tanfac Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did Tanfac Industries raise its FY27 revenue growth guidance?
Tanfac Industries raised its FY27 revenue growth guidance to 35-40%, compared with its earlier guidance of 30%. The update was shared during the company’s Q2 FY27 earnings conference call, which covered the unaudited financial results for the quarter and half year ended September 30, 2026.
The company linked revenue growth to higher realisations and new specialty products. Management also identified HFC-32 commercialisation as an important driver for the next phase of growth. Tanfac Industries has projected revenue growth of about 60% in FY28, subject to the expected contribution from the new product line.
The revised guidance is notable because it follows a quarter in which reported revenue rose sharply from the year-earlier level. However, the available conference-call information also indicates that profitability faced input-cost pressure, making revenue growth and margin performance separate issues for investors to track.
What were Tanfac Industries’ Q2 FY27 financial results?
Tanfac Industries reported Q2 FY27 revenue of ₹234.3 crore, up 38.9% year-on-year, while its H1 FY27 revenue was ₹422.4 crore, up 21.9% year-on-year. Other reported summaries described quarterly revenue at approximately ₹230 crore, but the more detailed result figure was ₹234.3 crore.
Profit before tax for the quarter was ₹24.4 crore. Net profit was reported at ₹19 crore, representing year-on-year growth of 10.77% and quarter-on-quarter growth of 12.95% in the available financial summary.
Operating EBITDA margin stood at 13.3% in Q2 FY27. Management said it expects margin recovery through pass-through pricing and moderating sulphur costs, with support from specialty-product launches. The company did not disclose a specific timetable or margin target for this recovery in the information provided.
How important is the HFC-32 project to Tanfac Industries’ plans?
Tanfac Industries is building a ₹495 crore HFC-32 plant at its Cuddalore, Tamil Nadu site, with annual capacity of 20,000 tonnes. Commissioning is targeted for Q3 FY27, according to the information available with the company’s investor materials.
Nearly two-thirds of the planned capacity had already been contracted with Japanese, multinational and Indian buyers before commissioning. These contracts provide visibility on a significant part of the plant’s initial output, although the disclosed information does not specify contract values, pricing or the timing of revenue recognition.
The project is being developed at Tanfac Industries’ existing 60-acre Cuddalore facility. The company has operated from this site since 1985 and is among India’s largest hydrofluoric acid producers. Hydrofluoric acid is a core input for fluorine chemistry, an area that requires specialised manufacturing and handling capabilities.
Got a follow-up? Ask IRIS
What does the outlook mean for investors and industry operations?
The updated guidance gives investors a clearer indication that Tanfac Industries expects FY27 revenue growth to exceed its earlier estimate. The reported 38.9% increase in second-quarter revenue and the planned HFC-32 start-up are the main disclosed foundations for that view.
At the same time, the 13.3% operating EBITDA margin shows that revenue expansion has not eliminated cost pressures. Sulphur costs and the company’s ability to implement pass-through pricing remain relevant to the earnings profile. Investors assessing the guidance will need to consider both the scale-up in sales and the pace of any margin normalisation.
For customers, contracted HFC-32 capacity suggests that the new unit has identified demand before operations begin. For the broader fluorochemicals sector, the plant adds domestic capacity in a specialised product category. Actual market impact will depend on commissioning, production ramp-up and the execution of contracted supply arrangements.
What did Tanfac Industries disclose after the earnings call?
Tanfac Industries held its Q2 FY27 earnings conference call on November 3, 2026, after its board meeting scheduled for November 2 to approve unaudited results for the quarter and half year ended September 30, 2026. The company subsequently made the audio recording of the call available on its website.
The recording allows shareholders and other market participants to review management’s discussion on revenue growth, margins, raw-material costs and the HFC-32 project. The available disclosures do not provide a separate update on the company’s share-price movement following the results or the conference call.
Conclusion
Tanfac Industries’ revised FY27 revenue growth guidance of 35-40% is supported by a strong reported Q2 revenue increase, specialty-product additions and the planned HFC-32 launch. The company’s ₹234.3 crore quarterly revenue and ₹422.4 crore first-half revenue show sales momentum, while the 13.3% operating EBITDA margin highlights continuing cost considerations.
The next disclosed operational milestone is the targeted Q3 FY27 commissioning of the 20,000-tonne-per-year HFC-32 plant. Investors will watch the start-up of the facility, conversion of contracted capacity into sales, sulphur-cost trends and management’s stated efforts to recover margins through pricing.