










Tata Motors Passenger Vehicles Limited holds No. 2 position
Key highlights
- TMPV delivered about 2 lakh vehicles in Q2 FY27, up 40% year-on-year.
- TMPV held 14.3% domestic market share in Q2 FY27 and 14.8% in October 2026.
- TMPV’s EV market share reached 43%, up nearly 380 basis points quarter-on-quarter.
- Sierra sales exceeded 70,000 units this year, while Aeris sold more than 4,000 units in its first month.
powered by IRIS
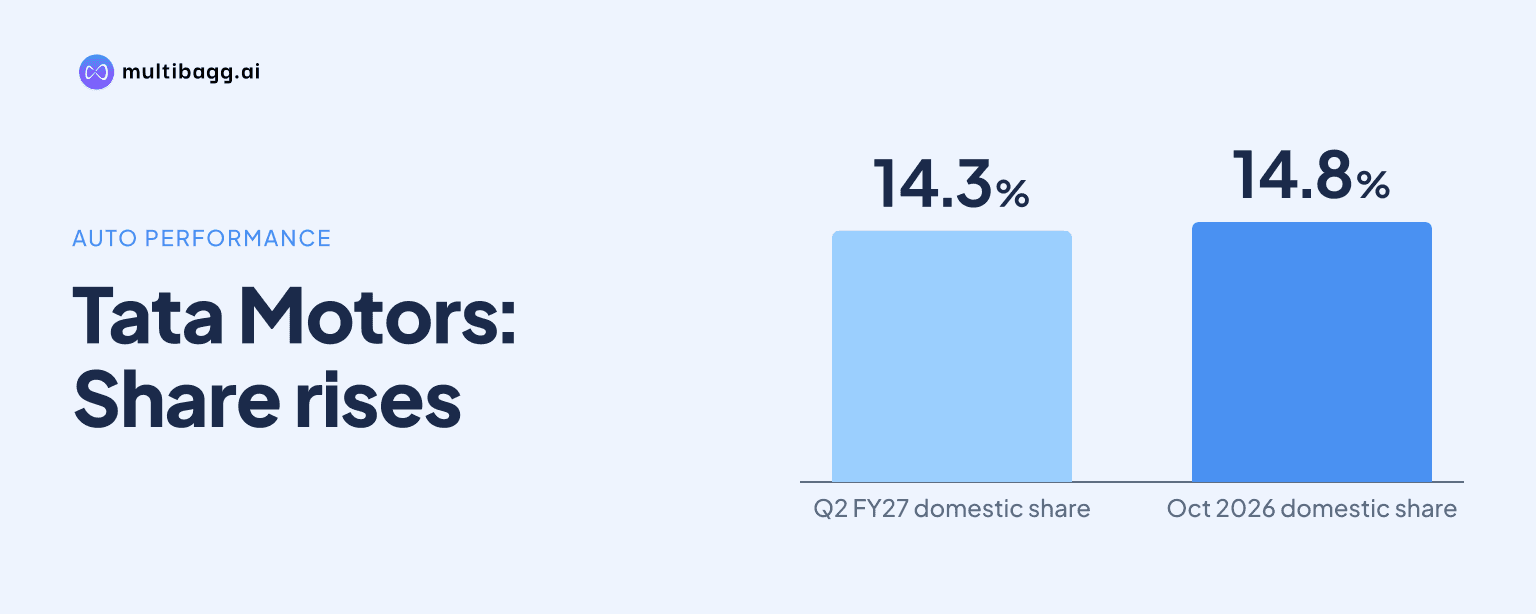
Tata Motors Passenger Vehicles Limited (TMPV) consolidated its number-two domestic industry position in Q2 FY27 with record quarterly volume of about 2 lakh units, up 40% year-on-year, and a 14.3% market share. TMPV’s growth exceeded the passenger-vehicle industry’s approximately 29% increase, supported by Punch, Sierra, Aeris and electric-vehicle volumes.
Know Tata Motors Passenger Vehicles inside out
Results, valuation, peers and who's buying, in one view.
How did TMPV consolidate its number-two position?
TMPV consolidated its number-two position by delivering about 2 lakh vehicles in Q2 FY27, 40% more than a year earlier, while its domestic market share reached 14.3%. Average monthly offtake was 67,000 units, also up 40% year-on-year. By comparison, the passenger-vehicle industry sold 1.36 million units during the quarter, growing approximately 29%, which means TMPV expanded faster than the wider market.
TMPV extended that momentum into October 2026, reporting record volume of 75,000 units and a 14.8% market share, 0.5 percentage points above its Q2 level. Management said festive-period retail sales rose 10% year-on-year despite a high comparison base after GST 2.0. The October result provides a post-quarter indication that demand remained broad-based rather than being confined to Q2 dispatches.
The market-share gain coincided with a shift toward CNG and electric vehicles, or EVs. Management put industry CNG penetration at around 25% and EV penetration at around 8% in Q2 FY27, together accounting for roughly one-third of industry volume. TMPV said alternate powertrains represented more than half of its own volume, with EVs alone at 23%, a materially higher mix than the industry EV penetration cited for the quarter.
Which TMPV models led the record volume growth?
Punch was TMPV’s clearest volume contributor, with management saying it emerged as India’s highest-selling model in Q2 FY27 following its facelift. Nexon was among the country’s five highest-selling models in H1 FY27. Those results show that established models contributed alongside recent launches, rather than the quarterly increase depending solely on new nameplates.
Sierra broadened TMPV’s portfolio into a new segment across internal-combustion-engine, or ICE, and EV versions. TMPV said it had sold more than 70,000 Sierra units this year and was working to raise production capacity further to meet demand. Management described the response to Sierra and Sierra.ev as encouraging, but did not disclose a capacity target or a date for the planned increase.
Aeris added another new nameplate, selling more than 4,000 units in its first month. Management said Aeris sales were limited by production rather than demand and that capacity was being expanded. Elsewhere, the refreshed Tiago and Tiago.ev helped TMPV’s hatchback volumes rise 35% quarter-on-quarter in Q2 FY27, showing that growth was not restricted to its SUV and sedan offerings.
Is TMPV EV demand higher than current production capacity?
Yes. TMPV said EV demand was ahead of available capacity, as average monthly EV offtake reached 16,000 units in Q2 FY27, nearly double the level of a year earlier. EVs accounted for 23% of TMPV volume, and the company recorded its highest-ever quarterly EV volume. Its EV market share reached 43%, up nearly 380 basis points, or 3.8 percentage points, quarter-on-quarter despite greater competition.
Booking and inventory data indicate the extent of the supply constraint. EVs made up roughly 30% of TMPV bookings but about 40% to 45% of pending bookings, while EV inventory stood at only 10 days. Overall inventory was 27 to 28 days, including six to seven days of vehicles in transit. Management plans to raise monthly EV production from roughly 16,000 units over the preceding two to three months towards 20,000 units in the next two to three months.
Punch.ev is TMPV’s most popular EV, according to management, and was the first EV in the market to cross 5,000 units in a month. TMPV’s total EV volumes grew 90% year-on-year in Q2 FY27. Management also said CNG demand was materially ahead of supply, making the expansion of output relevant across both of its principal greener-powertrain offerings.
Got a follow-up? Ask IRIS
Can TMPV convert record revenue into higher profitability?
TMPV reported record quarterly revenue of Rs 20,000 crore in Q2 FY27, up 50% year-on-year, but management said profitability was broadly flat sequentially because of elevated commodity costs. The comparison highlights the current constraint on earnings conversion: vehicle volume increased 40% year-on-year and revenue rose 50%, while higher input costs limited the immediate margin benefit from that scale.
Management said calibrated price increases and cost actions had offset roughly 40% of the commodity increase year to date, with TMPV absorbing the balance. Steel, rubber and copper costs were expected to remain adverse in Q3 FY27, while periodic foreign-exchange resets were another pressure. Management expects the commodity curve to start plateauing in Q4 FY27 and said it would use pricing, cost reductions and Production Linked Incentive, or PLI, support to hold margins.
PLI covered about 40% of TMPV’s portfolio, with two models having secured AAT while awaiting techno-commercial clearance and approval. Cumulative PLI accruals were about Rs 830 crore in H1 FY27, including about Rs 530 crore in Q2 FY27. Management expects at least that quarterly run rate in H2 FY27, although it noted there could be portfolio-related changes in the level of accruals.
TMPV spent Rs 2,700 crore on capital expenditure in H1 FY27 and generated about Rs 2,000 crore of positive free cash flow, aided by favourable working capital and the prior year’s PLI cash release. Management said capital expenditure should rise over the next 18 to 24 months as the next phase of capacity expansion begins. It also said the domestic business remained net-cash-positive despite commodity-led pressure on margins.
What is TMPV planning for the second half of FY27?
TMPV plans to sustain industry-beating growth through its demand pipeline, product portfolio and further launches while increasing production internally and with suppliers. Management expects industry growth rates to moderate in H2 FY27 because of a high base after GST 2.0, even though it described underlying demand as robust. The stated production actions cover EVs, Sierra and Aeris, where demand has exceeded current supply.
On profitability, management said it would accelerate cost-reduction initiatives, seek expedited PLI approvals and use calibrated price increases where required. It said a price increase would occur in Q4 FY27 and that another increase in Q3 FY27 remained possible after assessment of the full commodity impact. This approach reflects management’s effort to balance commodity recovery with preserving demand momentum after Q2’s 40% volume growth.
Conclusion
TMPV’s Q2 FY27 performance combined record volume of about 2 lakh units, 14.3% domestic market share and revenue of Rs 20,000 crore. Punch’s position as the quarter’s highest-selling model, Sierra’s more than 70,000 sales this year and Aeris’s production-limited launch indicate that refreshed and new products collectively supported the company’s number-two market position.
The next measures to watch are TMPV’s stated plan to lift EV production towards 20,000 units a month within two to three months, expand Sierra and Aeris capacity, and manage Q3 FY27 input-cost pressure. Management expects commodity costs to remain adverse in Q3 FY27, sees potential moderation in Q4 FY27, and plans higher capital expenditure over the next 18 to 24 months for capacity growth.