










Vikran says pending certification depressed FY27 margins
Key highlights
- Vikran reported a Q2 FY27 consolidated EBITDA margin of 10.5%, down from 14.4% in Q2 FY26.
- Vikran said Rs 13 crore to Rs 16 crore of non-NOPL price-variation revenue awaits client certification.
- H1 FY27 consolidated EBITDA was Rs 33.53 crore versus Rs 48 crore in H1 FY26.
- Management guided for EBITDA margin of around 15%, plus or minus 1%.
powered by IRIS
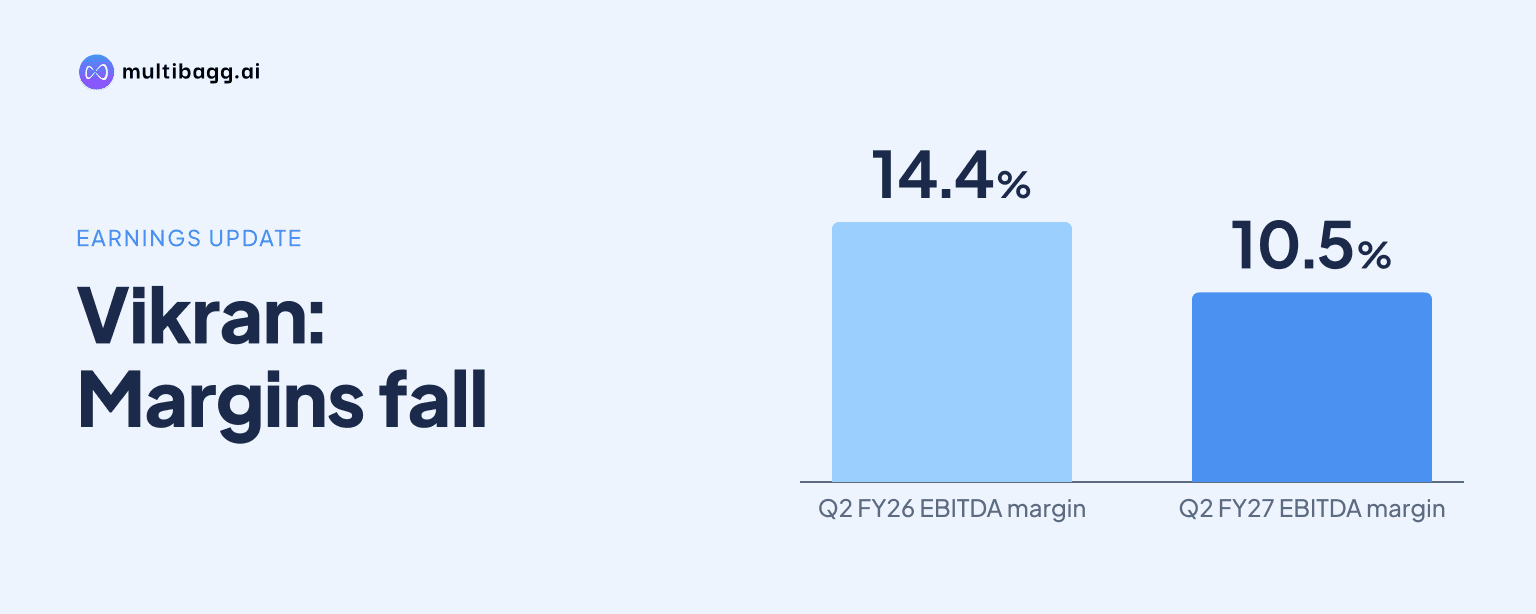
Vikran Engineering Limited said Rs 13 crore to Rs 16 crore of price-variation revenue from non-NOPL projects remained unrecognised in Q2 FY27 pending client certification, contributing to a consolidated EBITDA margin decline to 10.5% from 14.4% a year earlier. Management expects certification in H2 FY27 and said the revenue would then add to EBITDA.
Know Vikran Engineering inside out
Results, valuation, peers and who's buying, in one view.
Why did Vikran's reported margins decline in Q2 FY27?
Vikran said higher direct costs reduced reported consolidated EBITDA and profit after tax margins in Q2 FY27 because costs were booked immediately while related price-escalation revenue could not be recognised until clients certified it. Consolidated EBITDA was Rs 22.26 crore, down from Rs 25.43 crore in Q2 FY26, even as revenue rose 20% to Rs 211.84 crore from Rs 176 crore. The EBITDA margin therefore declined by 3.9 percentage points to 10.5%.
The effect extended below EBITDA. Consolidated profit after tax was Rs 2.75 crore in Q2 FY27, compared with Rs 9.12 crore a year earlier, and the PAT margin declined to 1.3% from 5.2%. Vikran Chief Financial Officer Ashish Bahety attributed both the EBITDA and PAT margin reduction to direct-cost escalation that management says is contractually pass-through eligible through price-variation clauses.
The first-half comparison showed a similar pattern, although revenue growth was slower than during the quarter. Consolidated H1 FY27 revenue reached Rs 353 crore, 5% above Rs 335 crore in H1 FY26, while EBITDA declined to Rs 33.53 crore from Rs 48 crore. EBITDA margin fell to 9.5% from 14.3%, and PAT fell to Rs 6.74 crore from Rs 14.78 crore, reducing the PAT margin to 1.9% from 4.4%.
How much revenue is Vikran waiting to recognise?
Vikran said about Rs 13 crore to Rs 16 crore of price-variation revenue has not yet been recognised because client certification is pending. Whole-Time Director Nakul Markhedkar said this amount relates mainly to non-NOPL projects in Madhya Pradesh and Maharashtra, rather than to the NOPL solar project. In response to an analyst's question, he confirmed that eventual recognition would add directly to EBITDA.
The accounting sequence described by management is central to the gap between cost and revenue recognition. Vikran records the higher direct cost when it is incurred under its conservative accounting policy, but records the corresponding contractual escalation revenue only after client certification. This means the reported Q2 FY27 EBITDA margin of 10.5% includes cost escalation without the associated Rs 13 crore to Rs 16 crore revenue awaiting approval.
Management said it expects certification in H2 FY27, while cautioning that quarterly results could move “plus or minus.” Its stated confidence concerns the full-year margin outcome rather than a specific quarter-by-quarter recovery schedule. The disclosure does not identify individual clients, project-level certification dates, or how much of the Rs 13 crore to Rs 16 crore could be recognised in Q3 FY27 versus Q4 FY27.
Got a follow-up? Ask IRIS
What EBITDA margin does Vikran guide for its EPC business?
Vikran's current guidance is to maintain EBITDA margins of around 15%, plus or minus 1%, according to Nakul Markhedkar. The target was discussed in relation to the company's transmission and distribution, or T&D, order book, where an analyst said roughly 30% of the Rs 6,200 crore order book was from T&D projects, primarily substation engineering, procurement and construction, or EPC, work.
That guidance is above the 9.5% consolidated EBITDA margin reported in H1 FY27 and the 10.5% reported in Q2 FY27. Management said most direct-cost escalation is covered by price-variation provisions, but identified a procurement risk: certain items not covered by price variation had risen in cost amid the West Asia crisis and higher crude-oil prices. Nakul Markhedkar said he hoped oil prices would be at manageable levels when those items are procured.
The standalone and consolidated figures also show different trends. Standalone H1 FY27 revenue increased 26% to Rs 424 crore from Rs 335.45 crore, while standalone EBITDA was broadly stable at Rs 48.13 crore against Rs 48.09 crore, reducing the standalone EBITDA margin to 11.3% from 14.3%. Standalone PAT increased 72% to Rs 25.38 crore from Rs 14.78 crore, with PAT margin rising to 6% from 4.4%.
What else affected Vikran's consolidated profitability?
Vikran said the deferment of NOPL project execution also affected consolidated profitability because it left overheads to be absorbed on a lower level of activity. Nakul Markhedkar said the company chose not to increase its exposure before loan disbursement, instead concentrating on projects where significant work was already complete. He said management expected the disbursement before the following week after call formalities had been completed.
NOPL covers 152 locations in Maharashtra and is planned at 969 megawatt alternating current, equivalent to 1,163 megawatt peak. Vikran said it had commissioned about 18 sites with nearly 90 megawatt of capacity, or close to 10% of the project, and was in advanced stages on a further 100 megawatt. Management expects about Rs 40 crore to Rs 50 crore of power-sale revenue in H2 FY27 from commissioned and further planned capacity.
Management said the solar project could improve overhead absorption as execution advances, but this is a forward-looking plan rather than a reported margin result. Vikran intends to push about 500 megawatt during FY27, while citing unresolved land identification for the last 10% to 15% of land as the remaining challenge. It said equipment orders had been placed and capacity had been blocked, and it did not see a procurement delay.
Conclusion
Vikran's reported consolidated margins declined despite revenue growth because the company says direct-cost escalation was recognised before Rs 13 crore to Rs 16 crore of related price-variation revenue received client certification. The numerical contrast is clear: Q2 FY27 consolidated revenue rose to Rs 211.84 crore, but EBITDA fell to Rs 22.26 crore and PAT to Rs 2.75 crore. The timing explanation applies mainly to non-NOPL projects in Madhya Pradesh and Maharashtra.
The next items to watch are client certification of the pending price-variation claims in H2 FY27, whether reported margins move toward management's guidance of around 15%, plus or minus 1%, and NOPL execution. Management expects NOPL completion by the end of Q1 FY28, with possible spillover into Q2 FY28, and says peak generation should begin from Q2 FY28.