










Vikran expects over Rs 500 crore NOPL sales from Q2 FY28
Key highlights
- Vikran expects NOPL completion by the end of Q1 FY28, with possible spillover into Q2 FY28.
- Management expects more than Rs 500 crore of annual NOPL power-sales revenue at peak generation.
- Vikran expects Rs 40 crore to Rs 50 crore of NOPL power-sales revenue in H2 FY27.
- NOPL has a Rs 2,941 crore IREDA financing agreement at 9.15% interest against an estimated Rs 4,200 crore project cost.
powered by IRIS
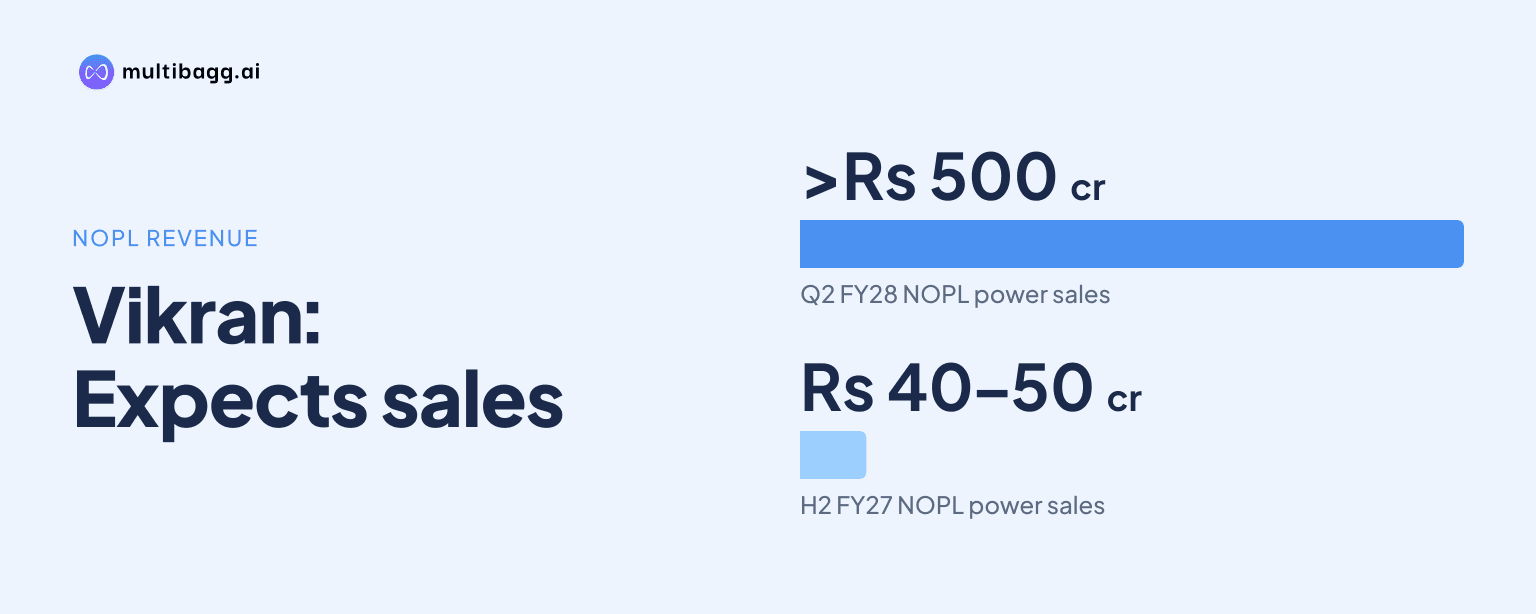
Vikran Engineering expects its NOPL solar project to reach peak generation from Q2 FY28 after completion by the end of Q1 FY28, potentially slipping into Q2, and management said peak output could generate more than Rs 500 crore of annual power-sales revenue. Management also projected an 85% to 88% earnings before interest, tax, depreciation and amortisation (EBITDA) margin at peak.
Know Vikran Engineering inside out
Results, valuation, peers and who's buying, in one view.
When will Vikran complete the NOPL solar project?
Vikran expects NOPL to be completed by the end of Q1 FY28, although management allowed for some spillover into Q2 FY28. Nakul Markhedkar said peak generation would begin from Q2 FY28, making that quarter the planned start of full project output rather than the date when the project first began producing power.
The FY28 schedule depends on accelerating execution during FY27. Management said it planned to push about 500 megawatt (MW) during the current financial year after the project’s financing disbursement was cleared. It said equipment procurement was not expected to cause a delay because orders had been placed and capacity needed for the project had been blocked in advance.
Land is the remaining issue identified by management. It said the final 15% of land presented a challenge, including 10% that had not yet been identified, but expressed confidence that it could resolve the matter before construction reached those parcels. The end-Q1 FY28 completion date is therefore a management expectation, not a completed project milestone.
NOPL has already entered partial operation. Management said around 10% of the project had been commissioned and another 100 MW was at an advanced stage near commissioning. In Q2 FY27, Vikran recognised about Rs 7 crore of NOPL revenue in standalone financials, while management also said the project had produced around Rs 4.66 crore of revenue and free cash flow in the first half or last quarter without separately defining the period.
How much power-sales revenue does Vikran expect from NOPL?
Vikran expects more than Rs 500 crore of annual power-sales revenue from NOPL at peak capacity. Management used Rs 500 crore as the annual benchmark and said the 10% of capacity already commissioned would correspond to about Rs 50 crore of revenue when measured over a full year.
For H2 FY27, management expects Rs 40 crore to Rs 50 crore of revenue from power sales. It said roughly 200 MW commissioned in the first half should contribute during the second half, while a further roughly 150 MW being commissioned in the quarter should add revenue in Q4 FY27. This partial-year estimate is below the peak annual figure because capacity will enter service at different points during H2 FY27.
Management clarified that Rs 50 crore represented annualised revenue from the first 10% of commissioned capacity, rather than revenue expected from that portion during a partial FY27 period. The expected revenue run rate should increase as more capacity is commissioned, but the transcript did not provide a quarterly power-sales target beyond the Rs 40 crore to Rs 50 crore H2 FY27 estimate.
The NOPL project also affects the presentation of Vikran’s financial results. Management said revenue and expenses from full generation would be recorded in consolidated, rather than standalone, accounts. In Q2 FY27, consolidated revenue was Rs 211.84 crore, compared with standalone revenue of Rs 220 crore, while about Rs 7 crore of standalone revenue was attributed to NOPL.
Got a follow-up? Ask IRIS
What profit and cash flow does Vikran project at peak output?
Vikran projects an EBITDA margin of around 85% to 88% for NOPL at peak generation. Management said interest cost would be the main deduction from EBITDA and separately noted that depreciation must be included when assessing profit after tax (PAT), meaning the margin is a project-stage forecast rather than reported profitability.
Management later estimated annual PAT, including depreciation, of around Rs 70 crore to Rs 75 crore, or about 12%, once the project reaches its expected mature operating stage. The estimate was given after management said peak generation should begin from Q2 FY28, so it does not represent a forecast for H2 FY27, when the project is still being commissioned.
The call contained two annual free-cash-flow figures. Ashish Bahety first cited Rs 100 crore of annual free cash flow from the project, while Markhedkar later referred to Rs 130 crore of free cash flow to Vikran. The transcript does not reconcile the Rs 30 crore difference, so these should be treated as separate management statements rather than one formal financial target.
NOPL has a long-term financing agreement with Indian Renewable Energy Development Agency Ltd. (IREDA) for Rs 2,941 crore against an estimated project cost of Rs 4,200 crore, at 9.15% interest. Management said loan disbursements would be aligned with execution across eight clusters and that solar-generation cash flow at peak output should cover interest and subsequent repayment requirements.
What could affect Vikran’s NOPL ramp-up and FY27 results?
Vikran identified financing disbursement and land availability as the main factors affecting the ramp-up. Management said it had deferred some NOPL work because no disbursement had been received and it did not want to increase project exposure, but added that formalities had been completed and it expected disbursement before the following week.
The earlier deferral affected the company’s FY27 revenue plan. Management said its Q2 FY27 internal target had included Rs 100 crore from NOPL and Rs 200 crore from non-NOPL projects, with the shortfall occurring on the NOPL side. It subsequently said it hoped to report roughly Rs 850 crore to Rs 900 crore of revenue in Q3 FY27, with the remaining FY27 revenue in Q4, while acknowledging the task was challenging.
Solar operations may also change Vikran’s working-capital cycle. Management said solar projects have a shorter cash cycle than its power and water businesses, and it targeted a reduction of about 40 to 50 debtor days from the prior year. It also said debtors had already declined by more than Rs 200 crore year on year, though the transcript did not state the closing debtor balance.
Group-level margins remain relevant while NOPL is under construction. Consolidated EBITDA margin was 9.5% in H1 FY27, down from 14.3% in H1 FY26, while consolidated PAT declined to Rs 6.74 crore from Rs 14.78 crore. Management attributed the movement to higher direct costs on non-NOPL projects, where Rs 13 crore to Rs 16 crore of price-variation revenue was not recognised pending client certification, with most expected in H2 FY27.
Conclusion
Vikran’s NOPL plan points to a move from partial commissioning in FY27 to peak generation from Q2 FY28, with management expecting more than Rs 500 crore in annual power sales. The project’s planned economics include an 85% to 88% EBITDA margin and annual PAT of around Rs 70 crore to Rs 75 crore, but these remain management projections dependent on commissioning and full operation.
The next disclosed checkpoints are the planned push of about 500 MW during FY27, resolution of the remaining 15% of land, and project-linked IREDA disbursements under the Rs 2,941 crore facility. Vikran has also set an H2 FY27 power-sales expectation of Rs 40 crore to Rs 50 crore, while its stated completion schedule places peak generation from Q2 FY28.