










Voltas reports record Voltbek Q2 sales, no FY28 target
Key highlights
- Voltbek reported its highest Q2 sales in value and volume in Q2 FY2027.
- Voltbek held approximately 8.8% washing-machine share and 7.0% refrigerator share at YTD September 2026.
- Voltbek ranked number two in semi-automatic washing machines with approximately 14.9% market share at YTD September 2026.
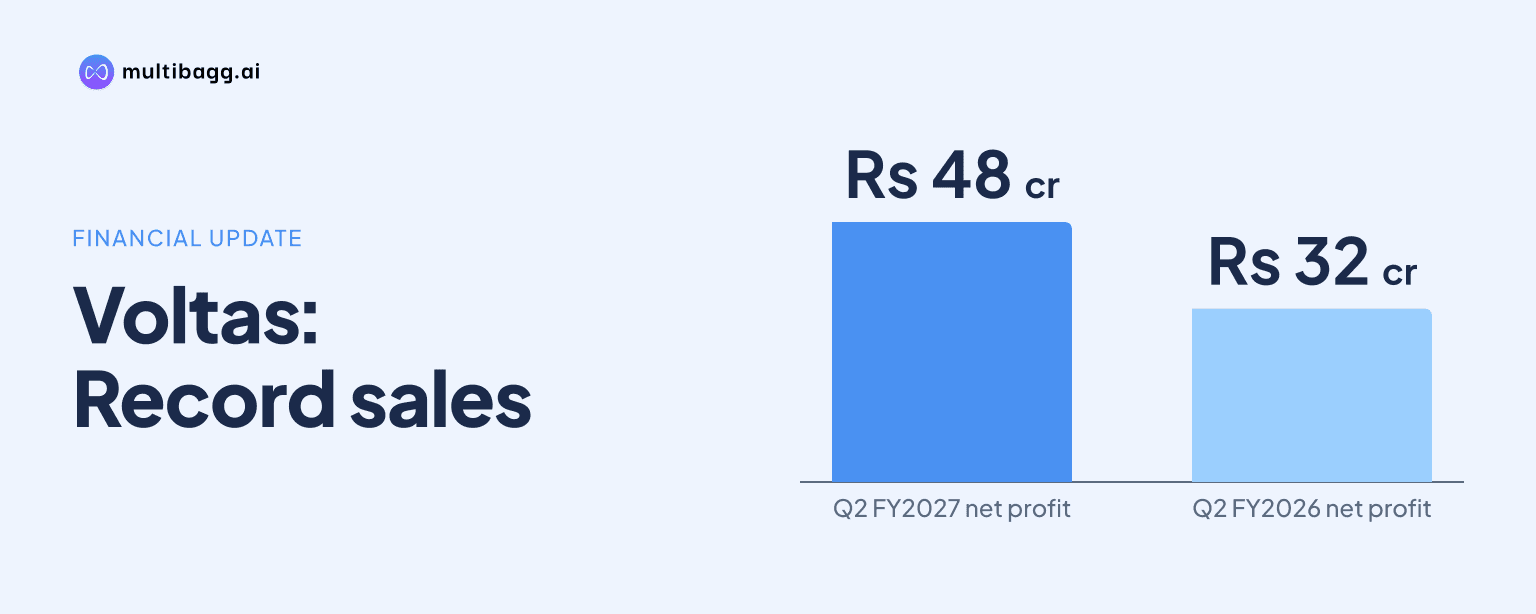
- Voltas reported Q2 FY2027 consolidated net profit of Rs 48 crore, compared with Rs 32 crore in Q2 FY2026.
powered by IRIS
Voltas Limited reported Voltbek’s highest Q2 FY2027 sales in value and volume and an 8.8% washing-machine market share at September 2026, but disclosed no FY28 earnings before interest, tax, depreciation and amortisation, or EBITDA, break-even target. Management instead identified sourcing, manufacturing productivity, new products and distribution expansion as its profitability levers.
Know Voltas inside out
Results, valuation, peers and who's buying, in one view.
Did Voltas set an FY28 Voltbek EBITDA break-even target?
No, Voltas did not disclose an FY28 EBITDA break-even target, a revised break-even date or a quantified profitability forecast for Voltbek in its Q2 FY2027 earnings call. Management said Voltbek delivered its highest second-quarter sales in both value and volume, but did not provide its revenue, EBITDA, operating loss or margin for the quarter ended September 30, 2026.
Voltas said sourcing efficiencies and manufacturing-productivity initiatives are expected to improve cost competitiveness and profitability as Voltbek scales. Its FY2027 priorities also include accelerating scale in washing machines and refrigerators, expanding distribution, and introducing frost-free refrigerators and fully automatic washing machines. These are operational plans rather than a numerical earnings commitment.
The call described commodity inflation and currency volatility as cost pressures for the wider consumer-durables industry in Q2 FY2027. However, Voltas did not quantify plastics, metals, insulation or other input-cost effects specifically for Voltbek, and it did not say that such costs delayed a prior FY28 target. The supplied transcript therefore does not establish a changed break-even timetable.
How is Voltbek building market share in appliances?
Voltbek held approximately 8.8% market share in washing machines and 7.0% in refrigerators for the year to date ended September 2026. In semi-automatic washing machines, Voltbek held approximately 14.9% share and ranked number two, according to Voltas. These positions accompanied the business’s highest Q2 sales in value and volume.
Voltas attributed the market-share positions to a wider product portfolio, rising consumer acceptance and deeper distribution penetration. It said refreshed product lines, improved product architecture, higher-capacity models and sharper consumer segmentation were intended to strengthen Voltbek’s presence in higher-value appliance segments during FY2027.
The company also launched the “Voltas Beko Sense Toh Banta Hai” campaign in Q2 FY2027, supported by refreshed products and consumer-engagement activity. Voltas identified retail visibility, product availability and distribution expansion in established and emerging consumption markets as priorities. It did not disclose the number of stores, cities or new outlets covered by these actions.
What cost pressures did Voltas identify in Q2 FY2027?
Voltas said commodity inflation and currency volatility increased manufacturing and supply-chain costs across consumer durables in Q2 FY2027. For Voltbek, management identified sourcing efficiencies and factory productivity as expected responses, but did not provide a venture-specific cost bridge, gross margin or EBITDA impact for the September 2026 quarter.
For the cooling business, Voltas said it had responded to input and currency pressures through calibrated pricing, strategic sourcing, localisation, product redesign, manufacturing productivity improvements and operating-cost management. The company said these actions, together with revenue growth and operational efficiencies, improved profitability in the Unitary Cooling Products segment compared with the corresponding prior-year quarter.
Voltas reported consolidated total income of Rs 2,746 crore in Q2 FY2027, up from Rs 2,412 crore in Q2 FY2026. Profit before tax increased to Rs 83 crore from Rs 54 crore, while net profit rose to Rs 48 crore from Rs 32 crore. Those figures show group-level improvement, but cannot be used to calculate Voltbek profitability because separate financial results were not disclosed.
Got a follow-up? Ask IRIS
How does Voltbek compare with Voltas’s cooling business?
Voltbek’s disclosed progress was market-share expansion and record Q2 sales, whereas Voltas provided quantified growth data for its Unitary Cooling Products segment. That segment recorded 29% revenue growth in Q2 FY2027, led by 32% room-air-conditioner volume growth, demonstrating that the company disclosed a clearer operating comparison for cooling than for the appliance venture.
Voltas held a 17.4% room-air-conditioner market share for the year to date ended September 2026, approximately 1.5 percentage points above the corresponding prior-year period. Its lead over the nearest competitor was 4.2 percentage points. By comparison, Voltbek’s disclosed shares ranged from 7.0% in refrigerators to 14.9% in semi-automatic washing machines, without prior-period share comparisons.
Management said Q2 is generally a softer quarter sequentially than Q1, and it expects the usual seasonal improvement in Q3 and Q4. That comment related to the broader business and Segment A profitability discussion, not to a disclosed Voltbek EBITDA forecast. Voltas did not provide a seasonal sales or margin outlook for Voltbek itself.
Which plans could improve Voltbek profitability next?
Voltas’s stated route to improved Voltbek profitability is scale combined with sourcing and production improvements, not a fixed-date break-even plan. Management said it would strengthen Voltbek’s washing-machine and refrigerator positions through new frost-free refrigerator and fully automatic washing-machine lines, wider distribution and continued product refreshes in FY2027.
Higher-capacity models, improved product architecture and sharper segmentation are intended to extend Voltbek’s presence in higher-value segments. At the same time, Voltas said sourcing efficiencies and manufacturing productivity should support cost competitiveness. The company did not disclose expected savings, manufacturing capacity, capital expenditure or a target EBITDA margin from these initiatives.
Voltas is also pursuing localisation, strategic sourcing, product engineering and operational-efficiency measures across its broader operations. In the cooling business, it cited possible local sourcing and manufacturing opportunities for critical components, including compressors, to reduce import dependence. The call did not state that compressor initiatives apply to Voltbek or quantify their financial effect on the appliance business.
Conclusion
Voltbek’s Q2 FY2027 disclosure points to growing market presence rather than a measurable break-even timetable. Its highest Q2 sales in value and volume, 8.8% washing-machine share, 7.0% refrigerator share and 14.9% semi-automatic washing-machine share show category progress, while the absence of revenue and profit figures prevents a direct assessment of its earnings trajectory.
The next disclosed developments to watch are Voltbek’s frost-free refrigerator and fully automatic washing-machine launches, distribution expansion and sourcing and manufacturing-productivity measures during FY2027. Voltas also said it enters the FY2027 festive season with these actions underway, while management’s stated priority remains scaling Voltbek and improving profitability without publishing a numerical EBITDA target.