










Wahren capacity reaches 44,000 MTPA as all lines enter production
Key highlights
- Wahren’s pharma-packaging capacity rose 5.5 times from 8,000 MTPA in FY25 to 44,000 MTPA from October 2026.
- The final 12,000-MT Alu Alu line completed trials in August 2026 and began commercial production in October 2026.
- Creative Graphics reported consolidated H1 FY27 revenue of Rs 233.3 crore, up 32.6% year on year.
- Wahren generated Rs 8.3 crore of exports in H1 FY27, while management targets exports of about 25% of pharma-packaging revenue.
powered by IRIS
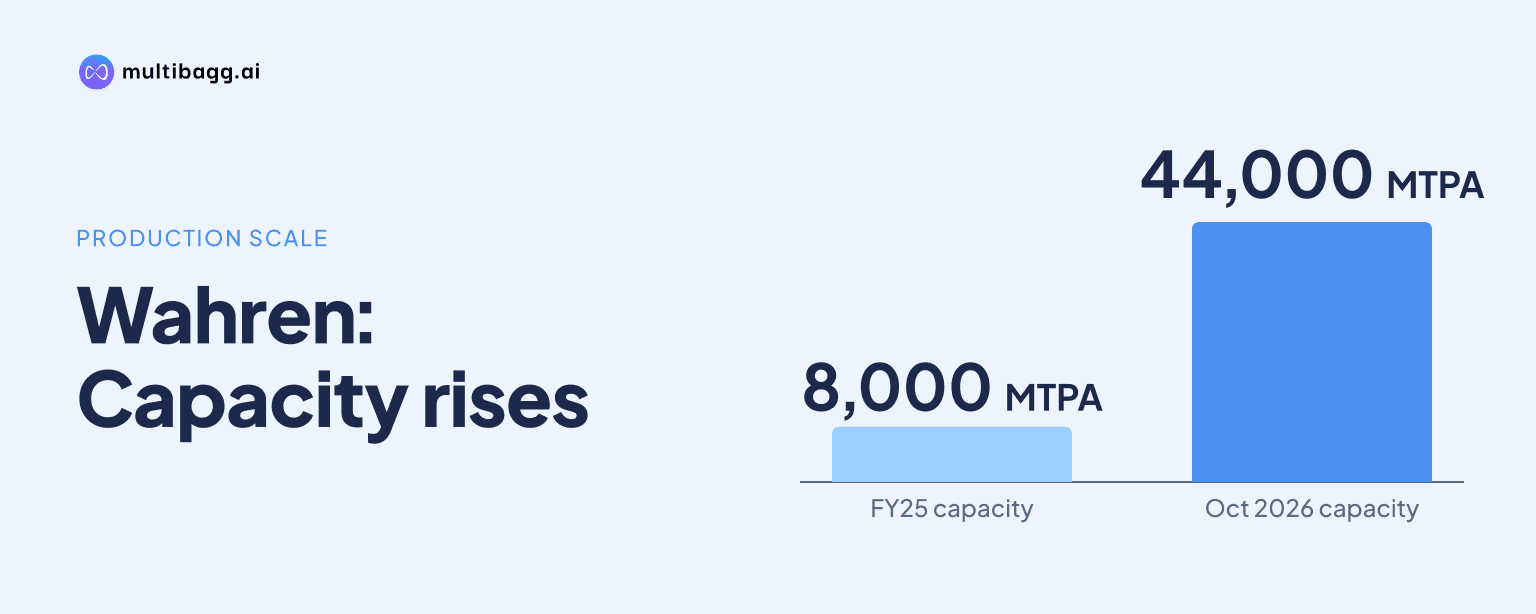
Wahren India Private Limited increased installed pharmaceutical-packaging capacity 5.5 times to 44,000 metric tonnes per annum (MTPA) from 8,000 MTPA, with all four lines in commercial production from October 2026. The final 12,000-MT Alu Alu line completed trials in August 2026 and began commercial output two months later.
Know Creative Graphics Solutions India inside out
Results, valuation, peers and who's buying, in one view.
How much pharma-packaging capacity does Wahren now have?
Wahren now has 44,000 MTPA of installed pharma-packaging capacity, compared with 8,000 MTPA in FY25. The increase adds 36,000 MTPA across three new 12,000-MT lines while retaining the original 8,000-MT Alu Alu capacity. Management says the original 8,000-MTPA Alu Alu capacity is already fully utilised.
The expansion is complete, and Wahren says no major new capital expenditure is required to operate the 44,000-MTPA platform. Creative Graphics Solutions India Limited, Wahren’s listed parent, reported Rs 31 crore of group capital expenditure in FY26. It also said two acquired lines were purchased through a National Company Law Tribunal process at about 10% of their estimated replacement cost.
The difference between installed and operating capacity was resolved in October 2026, when the final 12,000-MT Alu Alu line entered commercial production. This matters because the 44,000-MTPA total includes four product lines rather than an expansion of one existing format, broadening Wahren’s offering across films, laminates and foil.
Which new Wahren lines have entered commercial production?
Wahren’s three new 12,000-MT lines are a PVC/PVDC coating line, a Tandem extrusion line and an Alu Alu coating and lamination line. PVC/PVDC means polyvinyl chloride and polyvinylidene chloride, materials used in higher-barrier pharmaceutical films. Wahren places PVC film at the standard end of its barrier portfolio and Alu Alu cold-form foil at the highest-barrier end.
The German PVC/PVDC line has been in commercial production since H2 FY26 and uses four-stage coating for films ranging from 30 to 180 grams per square metre. The South Korean Tandem extrusion line began commercial production in April 2026, producing dual-stage, three- to five-ply extrusion laminates for applications including sachets, strip foils and multilayer packs.
The Italian Boht EXPERTCOAT 1000 line completed trials in August 2026 before its October commercial start. Wahren also installed an Indian heat-seal lacquer coating machine for lidding foil, adding heat-seal-coated lidding foil to products that already include blister lidding foils and child-resistant formats.
Got a follow-up? Ask IRIS
What does the capacity ramp mean for earnings so far?
The capacity ramp has coincided with higher group revenue but lower year-on-year profitability, as new lines carried fixed costs before volumes reached the new capacity. In H1 FY27, Creative Graphics reported consolidated revenue of Rs 233.3 crore, up 32.6% from Rs 175.9 crore in H1 FY26 and 37.1% from Rs 170.1 crore in H2 FY26.
Consolidated earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 19.5 crore in H1 FY27, compared with Rs 21 crore a year earlier and Rs 12.4 crore in H2 FY26. The EBITDA margin was 8.3%, up from 7.3% in H2 FY26 but below 11.9% in H1 FY26. Management attributed the year-on-year margin reduction to fixed costs from new capacity ahead of volumes and supply-chain disruption linked to the Middle East conflict.
Gross profit rose to Rs 58.2 crore in H1 FY27 from Rs 47.6 crore a year earlier, while the gross margin declined to 24.9% from 27.1%. Depreciation and amortisation increased 60.9% year on year to Rs 4.1 crore, and finance costs rose 77.6% to Rs 5.3 crore. As a result, consolidated profit after tax fell 40.4% to Rs 7.3 crore from Rs 12.2 crore.
Management’s operating-leverage case depends on greater output from the new lines: staff and depreciation costs would be spread across higher production as capacity fills. That is a management explanation rather than a reported outcome, since Wahren had only 32,000 MTPA in commercial production at 30 September 2026 and the final line started in October.
What must happen for Wahren to fill the new capacity?
Wahren must win customer approvals, convert trials into repeat orders and expand sales to larger pharmaceutical companies to fill the added 36,000 MTPA. Its qualification path includes supplier audits, trials on customer production lines, documentation and Drug Master File, or DMF, references, vendor approval, and then commercial batch-by-batch supply.
Wahren reported more than 350 active pharmaceutical clients and quality systems or certifications including good manufacturing practice, ISO, BRC and SGS. It has DMFs in the United States, China and Canada. These qualifications support market access, but the presentation does not disclose a capacity-utilisation percentage for the three new lines or a date by which management expects them to reach a specified utilisation level.
Wahren is also targeting larger pharmaceutical customers and has expanded its sales team, including the hiring of a Head of Export Sales. In H1 FY27, group exports reached Rs 12 crore, equal to 5.2% of revenue and above the Rs 8.1 crore reported for all of FY26. Wahren contributed Rs 8.3 crore of H1 FY27 exports, while the flexography business contributed Rs 3.7 crore.
Management’s stated export objective is for about 25% of pharma-packaging revenue to come from exports. The first pharma export order was received in February 2026, and export factoring has been introduced to fund export receivables soon after shipment. Wahren said it was in discussions with customers in 11 countries, but did not disclose the revenue value or timing of potential orders.
Conclusion
Wahren has completed a major shift in its production base, rising from 8,000 MTPA in FY25 to 44,000 MTPA from October 2026. The expansion adds PVC/PVDC films, extrusion laminates and additional Alu Alu capacity alongside existing foil output, while the parent’s H1 FY27 results show revenue growth occurring before the expanded asset base has lifted year-on-year margins.
The next measures to watch are output and customer approvals for the three 12,000-MT lines, particularly the Alu Alu line that began commercial production in October 2026. Management’s disclosed milestones are its pursuit of larger customers, discussions in 11 export markets and a target for exports to account for about 25% of pharma-packaging revenue.