










Zetwerk Manufacturing Businesses Limited Reports ₹171 Crore Q2 EBITDA
Key highlights
- Zetwerk reported Q2 FY27 revenue of ₹4,599 crore, up 12% quarter-on-quarter and 18% year-on-year.
- Q2 FY27 adjusted EBITDA was ₹171 crore, increasing 66% quarter-on-quarter.
- Zetwerk’s manufacturing order backlog was ₹14,500 crore, up 67% year-on-year.
- H1 FY27 revenue reached ₹8,717 crore, up 33% year-on-year, while adjusted EBITDA was ₹274 crore.
powered by IRIS
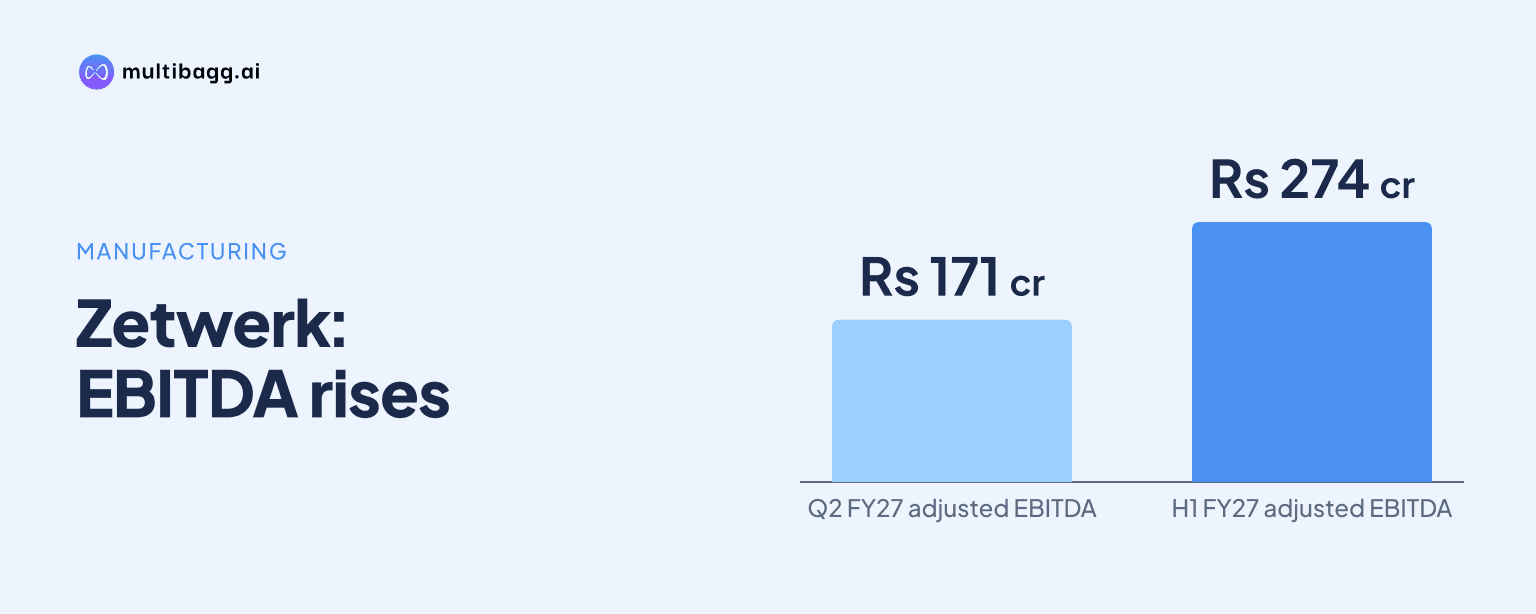
Zetwerk Manufacturing Businesses Limited reported adjusted EBITDA of ₹171 crore for Q2 FY27, up 66% quarter-on-quarter, alongside revenue of ₹4,599 crore and a manufacturing order backlog of ₹14,500 crore. The November 13 earnings call was the company’s first following its October IPO, with management maintaining guidance for 25% growth despite negative operating cash flow.
Know Zetwerk Manufacturing Businesses inside out
Results, valuation, peers and who's buying, in one view.
What did Zetwerk report for Q2 FY27?
Zetwerk reported Q2 FY27 revenue of ₹4,599 crore, a 12% increase quarter-on-quarter and an 18% increase year-on-year. Gross profit increased 39% from the preceding quarter, while adjusted EBITDA rose 66% sequentially to ₹171 crore. The operating performance marked an improvement in profitability measures during the quarter.
For the first half of FY27, revenue stood at ₹8,717 crore, up 33% year-on-year. Gross profit for the half year rose 42% to ₹1,187 crore, while adjusted EBITDA increased 69% to ₹274 crore. The company reported an adjusted EBITDA margin of 3.1% for the half year.
How did margins change during the quarter?
Zetwerk said gross margin was about 15% in Q2 FY27, compared with 13% a year earlier and 12% in the previous quarter. The higher gross profit growth relative to revenue indicates that margin expansion contributed to the quarter’s earnings improvement.
Management indicated a gross-margin target of about 21% for FY27. The company also disclosed that H1 manufacturing gross margins were 24% for its marketplace operations and 25% for captive production. By geography, the stated H1 manufacturing gross margins were 19% in India and 32% in international markets.
The reported figures show that the company’s consolidated profitability remains at a different level from its manufacturing gross-margin measures. Investors assessing the earnings release will therefore need to distinguish between gross-margin data for manufacturing activities and adjusted EBITDA, which was ₹274 crore for the first half.
What does Zetwerk’s ₹14,500 crore backlog indicate?
Zetwerk said its manufacturing order backlog reached ₹14,500 crore, up 67% year-on-year, with an expected conversion period of about two years. Management also described the backlog as offering roughly three years of revenue coverage, pointing to substantial order visibility under its stated assumptions.
The accompanying investor presentation cited a record manufacturing backlog of ₹14,595 crore. The small difference reflects the use of rounded figures in the call summary. Both disclosures indicate that the backlog was at a record level at the end of the reported period.
Management described supply availability as a constraint rather than demand. The order pipeline spans Indian thermal power, renewable energy, electrification and defence, along with activity in the United States. The company identified India and the US as markets benefiting from demand and supply-chain shifts away from China.
Got a follow-up? Ask IRIS
Why is operating cash flow still a key issue for investors?
Operating cash flow remained negative despite the improvement in revenue, gross profit and adjusted EBITDA. Management addressed the issue on the call and was defensive about the timing of interest and cash-flow movements, according to the call summary.
Negative operating cash flow is relevant because earnings growth does not by itself establish the timing of cash generation. The available call information does not provide an operating cash-flow figure, a cash-flow target or a specific timeline for improvement. Investors therefore have reported profitability data, but limited quantified detail on the cash conversion position from this disclosure.
The call was held after Zetwerk’s October IPO, making the cash-flow discussion particularly relevant for public-market investors reviewing the company’s first reported quarterly interaction after listing. No share-price movement or market reaction was provided in the source material.
What did Zetwerk disclose after the earnings call?
Zetwerk hosted its Q2 and half-year FY27 earnings conference call on November 13, 2026, to discuss unaudited standalone and consolidated results for the period ended September 30, 2026. The company subsequently made the audio recording available through its investor relations website.
The disclosure was filed under Regulation 30 of the SEBI Listing Obligations and Disclosure Requirements Regulations, 2015. The filing stated that the call covered both standalone and consolidated financial results, though it did not provide detailed figures within the audio-recording announcement itself.
The company’s 25% growth guidance remains the main forward-looking figure cited in the call summary. Its delivery will depend on backlog conversion, supply availability, margin execution and the movement of cash through operations, none of which received a quantified update beyond the reported operating metrics.
Conclusion
Zetwerk’s Q2 FY27 call highlighted sequential improvement in revenue, gross profit and adjusted EBITDA, supported by a record order backlog. Revenue rose 12% quarter-on-quarter to ₹4,599 crore and adjusted EBITDA increased 66% to ₹171 crore, while negative operating cash flow remained an important counterpoint to the stronger profit metrics.
The next areas to watch are progress toward the company’s 25% growth guidance, conversion of its ₹14,500 crore backlog and movement toward the stated FY27 gross-margin target of about 21%. Any subsequent results disclosures may also provide clearer evidence on cash conversion and interest timing.