










Kanohar Q2 revenue more than doubled, EBITDA margin hit 35%
Key highlights
- Kanohar's Q2FY27 revenue rose 112.4% year on year to Rs 208.6 crore.
- Kanohar's Q2FY27 EBITDA margin increased to 35.0% from 27.8%.
- Kanohar's H1FY27 profit after tax rose 164.8% to Rs 81.2 crore.
- Kanohar's order book reached Rs 2,711.2 crore at 30 September 2026.
powered by IRIS
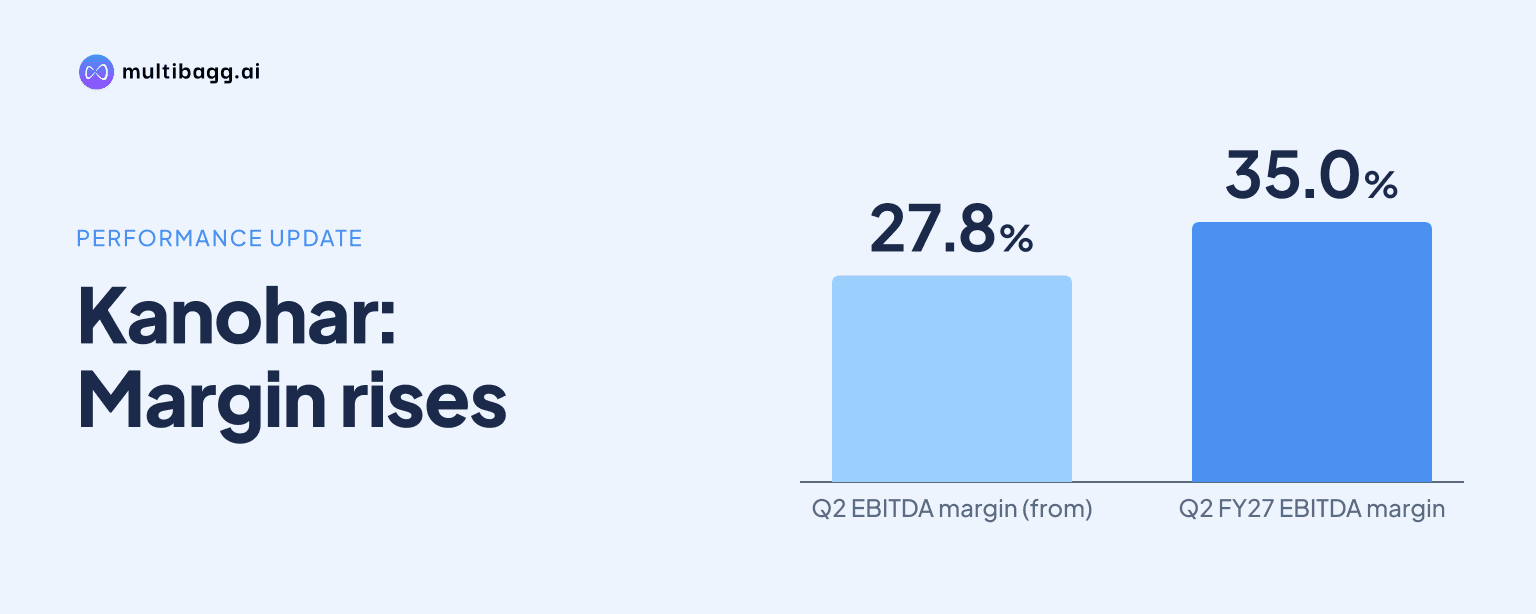
Kanohar Electricals Limited more than doubled consolidated revenue in the second quarter of fiscal year 2027 (Q2FY27) to Rs 208.6 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin rose to 35.0% from 27.8% a year earlier. Gross margin and profit-after-tax margin also increased, alongside a Rs 2,711.2 crore order book at 30 September 2026.
Know Kanohar Electricals inside out
Results, valuation, peers and who's buying, in one view.
How did Kanohar perform in Q2FY27?
Kanohar delivered Rs 208.6 crore of revenue from operations in Q2FY27, up 112.4% from Rs 98.2 crore in Q2FY26. Gross profit increased 125.4% to Rs 95.4 crore, faster than revenue growth, lifting gross margin by 2.7 percentage points to 45.8% from 43.1%.
EBITDA increased 167.2% to Rs 73.1 crore from Rs 27.4 crore, and the EBITDA margin increased 7.2 percentage points to 35.0%. Employee cost rose to Rs 12.6 crore from Rs 8.8 crore, while other expenses increased to Rs 9.7 crore from Rs 6.2 crore, compared with the Rs 53.1 crore increase in gross profit.
Why did Kanohar's Q2 margins increase?
Kanohar's Q2FY27 gross margin increased to 45.8% and EBITDA margin to 35.0%, from 43.1% and 27.8% in Q2FY26, respectively. Management attributed first-half performance to higher volumes and a broader product mix, and said a greater proportion of higher-voltage products improved the margin profile.
Cost of goods sold was Rs 113.2 crore in Q2FY27, against Rs 55.9 crore a year earlier, leaving Rs 95.4 crore of gross profit on Rs 208.6 crore of revenue. Depreciation declined to Rs 0.7 crore from Rs 0.8 crore, while finance cost increased to Rs 2.7 crore from Rs 2.4 crore and profit before tax rose 178.7% to Rs 72.3 crore.
Profit after tax increased 179.7% to Rs 53.9 crore from Rs 19.3 crore, raising the profit-after-tax margin by 6.2 percentage points to 25.8%. Tax expense rose to Rs 18.4 crore from Rs 6.7 crore, other income increased to Rs 2.6 crore from Rs 1.8 crore, and earnings per share were Rs 7.14 compared with Rs 2.59.
What does Kanohar's H1FY27 performance show?
Kanohar reported Rs 345.7 crore of consolidated revenue in the first half of fiscal year 2027 (H1FY27), up 108.8% from Rs 165.6 crore in H1FY26, while EBITDA rose 161.7% to Rs 111.8 crore. The H1FY27 EBITDA margin was 32.3%, compared with 25.8% a year earlier, showing margin expansion across the six-month period.
Gross profit rose 114.0% to Rs 152.9 crore from Rs 71.5 crore, and gross margin increased to 44.2% from 43.2%. Profit after tax grew 164.8% to Rs 81.2 crore from Rs 30.7 crore, while the profit-after-tax margin increased by 5.0 percentage points to 23.5% and earnings per share reached Rs 10.83 from Rs 4.12.
Q2FY27 accounted for Rs 208.6 crore of H1FY27 revenue, compared with Rs 137.1 crore implied for the first quarter from the Rs 345.7 crore half-year total. Q2FY27 EBITDA of Rs 73.1 crore similarly exceeded the Rs 38.7 crore implied for the first quarter from H1FY27 EBITDA of Rs 111.8 crore.
Got a follow-up? Ask IRIS
Which products changed Kanohar's revenue mix?
Kanohar's transformer business represented 87.8% of H1FY27 revenue, up from 76.0% in H1FY26, while engineering, procurement and construction (EPC) represented 12.2%, down from 24.0%. Management said power-transformer revenue grew 88% year on year in H1FY27, citing volume growth and a broader product mix.
Shunt reactors represented 21.7% of transformer business mix in H1FY27, compared with 0.1% in H1FY26. Power transformers represented 56.0%, down from 62.2%; Scott transformers accounted for 8.8%, against 9.7%; and distribution transformers contributed 1.2% after recording no share a year earlier.
Products rated 400 kilovolts (kV) represented 55.9% of transformer revenue in H1FY27, while products rated 220 kV and below 400 kV represented 21.8%. Together, those categories made up 77.7% of revenue, compared with 53.3% in H1FY26; products below 132 kV fell to 1.2% from 9.5%, and management said the higher-voltage mix improved the margin profile.
What order book and expansion plans does Kanohar have?
Kanohar's consolidated order book was Rs 2,711.2 crore at 30 September 2026, up 34% from Rs 2,026.0 crore at 30 June 2026. Management said it secured fresh orders worth about Rs 867.3 crore during the quarter and expects the outstanding order book to be executed over the next 24 to 30 months.
Power transformers accounted for 78.5% of the September 2026 order book, shunt reactors for 10.0%, EPC solutions for 7.5%, Scott transformers for 2.6% and distribution transformers for 1.3%. Government clients represented 89.1% of the order book, while private-sector clients represented 10.9%.
Management said the brownfield expansion at Kanohar's Gangol unit was on track for commissioning by FY29. Based on H1FY27 performance, management expects FY27 revenue of about Rs 950 crore with an EBITDA margin profile similar to FY26; the supplied presentation pages do not state a numeric FY26 EBITDA margin.
Conclusion
Kanohar's Q2FY27 results show reported margin expansion alongside revenue growth: revenue rose 112.4% to Rs 208.6 crore, gross margin reached 45.8%, EBITDA margin reached 35.0%, and profit after tax increased 179.7% to Rs 53.9 crore. H1FY27 showed the same direction, with revenue up 108.8% and EBITDA up 161.7%.
The next disclosed markers are execution of the Rs 2,711.2 crore order book over management's expected 24 to 30 months, progress toward its approximately Rs 950 crore FY27 revenue expectation, and commissioning of the Gangol brownfield expansion by FY29. Management's expectation of an FY26-like EBITDA margin profile is also a disclosed benchmark for subsequent results.