










Ola Electric Mobility Q2 FY27 sales may fall 26.5%, says Kotak
Key highlights
- Ola Electric Mobility will consider Q2 FY27 results on November 12, 2026.
- Kotak Institutional Equities estimates Q2 FY27 net sales of ₹507 crore, down 26.5% year on year.
- Kotak forecasts a Q2 FY27 EBITDA loss of ₹140 crore, versus a ₹165 crore loss in Q1 FY27.
- Ola Electric Mobility reported Q1 FY27 revenue from operations of ₹455 crore and a net loss of ₹336 crore.
powered by IRIS
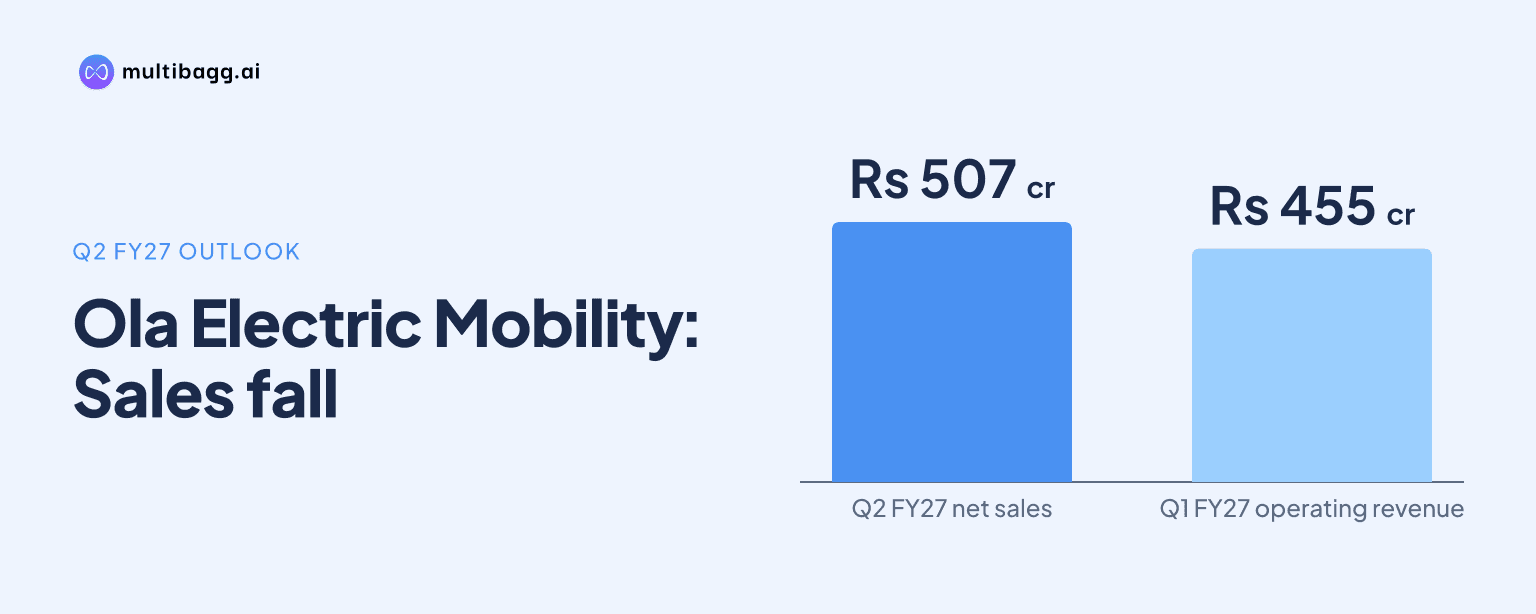
Ola Electric Mobility Limited is scheduled to consider Q2 FY27 results on November 12, with Kotak Institutional Equities estimating net sales of ₹507 crore, a 26.5% year-on-year decline, and a narrower net loss of ₹315.3 crore. The earnings will show whether improving sequential demand and cost control have translated into a reduced operating loss.
Know Ola Electric Mobility inside out
Results, valuation, peers and who's buying, in one view.
When will Ola Electric Mobility report Q2 FY27 results?
Ola Electric Mobility will consider and approve its unaudited standalone and consolidated results for the quarter and half-year ended September 30, 2026, at a board meeting on Thursday, November 12. The company disclosed the meeting date in an NSE filing made on November 7.
The company has also scheduled an earnings conference call at 5:00 PM IST on November 12 for analysts and investors. The call is expected to cover the July-September quarter, which is the second quarter of FY27, and management's discussion of the reported financial performance and outlook.
The timing is relevant because Ola Electric's latest reported quarter showed a sharp sequential recovery in automotive revenue but a steep year-on-year decline. Its Q1 FY27 revenue from operations was ₹455 crore, 71.7% higher than ₹265 crore in Q4 FY26, but 45% below ₹828 crore in Q1 FY26.
The upcoming results will also include the first-half financial statements. The regulatory notice does not disclose Q2 performance figures, so the market will rely on the reported results and management commentary for confirmation of demand, margins and operating costs during the quarter.
What does Kotak Institutional Equities expect from Ola Electric Mobility's Q2 FY27?
Kotak Institutional Equities expects Ola Electric to report Q2 FY27 net sales of ₹507 crore, representing an 11.5% quarter-on-quarter increase but a 26.5% year-on-year decline. The brokerage attributes the annual sales decline to an expected 20% fall in volumes and a 5-6% reduction in average selling prices.
According to Kotak, the lower average selling price is linked to an inferior product mix. At the same time, the brokerage expects the company to narrow its consolidated net loss to ₹315.3 crore, compared with the ₹336 crore net loss reported in Q1 FY27. This would also be lower than the ₹418 crore loss recorded in Q2 FY26.
Kotak forecasts an EBITDA loss of ₹140 crore for Q2 FY27. That compares with an EBITDA loss of ₹170 crore in Q1 FY27 and ₹200 crore in Q2 FY26, indicating an expected improvement both sequentially and from a year earlier.
The brokerage said lower sequential losses could be supported by operating leverage, cost-control measures and a higher mix of the Gen-3 platform. It also noted that commodity headwinds could partly offset these benefits. These are estimates, not financial results disclosed by Ola Electric.
Got a follow-up? Ask IRIS
How did Ola Electric Mobility perform in the previous quarter?
Ola Electric reported a consolidated net loss of ₹336 crore in Q1 FY27, narrowing from a ₹428 crore loss in Q1 FY26 and a ₹500 crore loss in Q4 FY26. Total income for the June 2026 quarter was ₹484 crore, compared with ₹304 crore in the March 2026 quarter and ₹896 crore in the June 2025 quarter.
Revenue from core operations, described by the company as automotive revenue from operations, stood at ₹455 crore in Q1 FY27. Automotive gross profit was ₹139 crore and gross margin was 30.5%, versus a gross margin of 38.3% in Q4 FY26 and 25.6% in Q1 FY26.
The company said Q1 orders rose to about 44,000 units, up 96% quarter on quarter, while deliveries increased 94% quarter on quarter to about 39,200 units. Registrations were reported at about 43,900 units. These operating measures supported the sequential increase in automotive revenue from ₹264 crore in Q4 FY26 to ₹455 crore in Q1 FY27.
However, the business remained loss-making at the operating level. Consolidated operating EBITDA loss improved to ₹165 crore in Q1 FY27 from ₹281 crore in Q4 FY26, while adjusted operating EBITDA loss was ₹195 crore. Cash flow from operations was negative ₹215 crore and free cash flow was negative ₹351 crore in the quarter.
Why do the Q2 FY27 figures matter for investors and the electric two-wheeler market?
The Q2 FY27 release matters because it will test whether Ola Electric can sustain its Q1 sequential recovery while reducing losses further. Kotak's forecast of a sales increase from the preceding quarter, alongside a decline from the prior-year quarter, points to the differing effects of a low Q4 FY26 base and lower annual volume and pricing assumptions.
Margin progression is a central measure for the company. Ola Electric's reported gross margin improved over several quarters before falling to 30.5% in Q1 FY27 from 38.3% in Q4 FY26. Kotak expects operating leverage and cost controls to help reduce EBITDA losses in Q2, although it has flagged commodity costs as a countervailing factor.
For investors, the results will provide updated data on sales, losses, cash generation and the Gen-3 platform mix. The company operates in India's electric two-wheeler market, where unit volumes, pricing, product mix and input costs can materially affect quarterly revenue and profitability.
The Q1 FY27 results were released with a qualified audit opinion related to a provision reversal connected with a government incentive scheme. The Q2 filing and investor call may provide further information on financial reporting matters and operating trends, but no outcome should be assumed before the company releases its statements.
Conclusion
Ola Electric Mobility enters its Q2 FY27 results with expectations of sequentially higher sales and a narrower operating loss, while year-on-year sales are projected to remain lower. Kotak's estimate of ₹507 crore in net sales and a ₹140 crore EBITDA loss highlights the importance of volumes, average selling prices, product mix and cost control to the company's quarterly performance.
Investors will watch the November 12 board-approved results and the 5:00 PM IST earnings call for the actual revenue, EBITDA, net loss, delivery and margin figures. Management commentary on the Gen-3 platform mix, commodity costs and the factors behind any movement in losses will be the next disclosed indicators to assess.