










Poly Medicure lifts FY27 EBITDA margin guidance to 27.5%
Key highlights
- Poly Medicure raised FY27 standalone EBITDA-margin guidance to 26%-27.5% from 25%-27%.
- Standalone H1 FY27 gross margin increased 111 basis points to 70.1%, with gross profit up 17% to Rs 645 crore.
- Standalone H1 FY27 revenue grew 15% to Rs 919 crore, while Q2 revenue rose 17% to Rs 488 crore.
- Poly Medicure retained FY27 standalone revenue guidance of Rs 1,900 crore-Rs 1,950 crore.
powered by IRIS
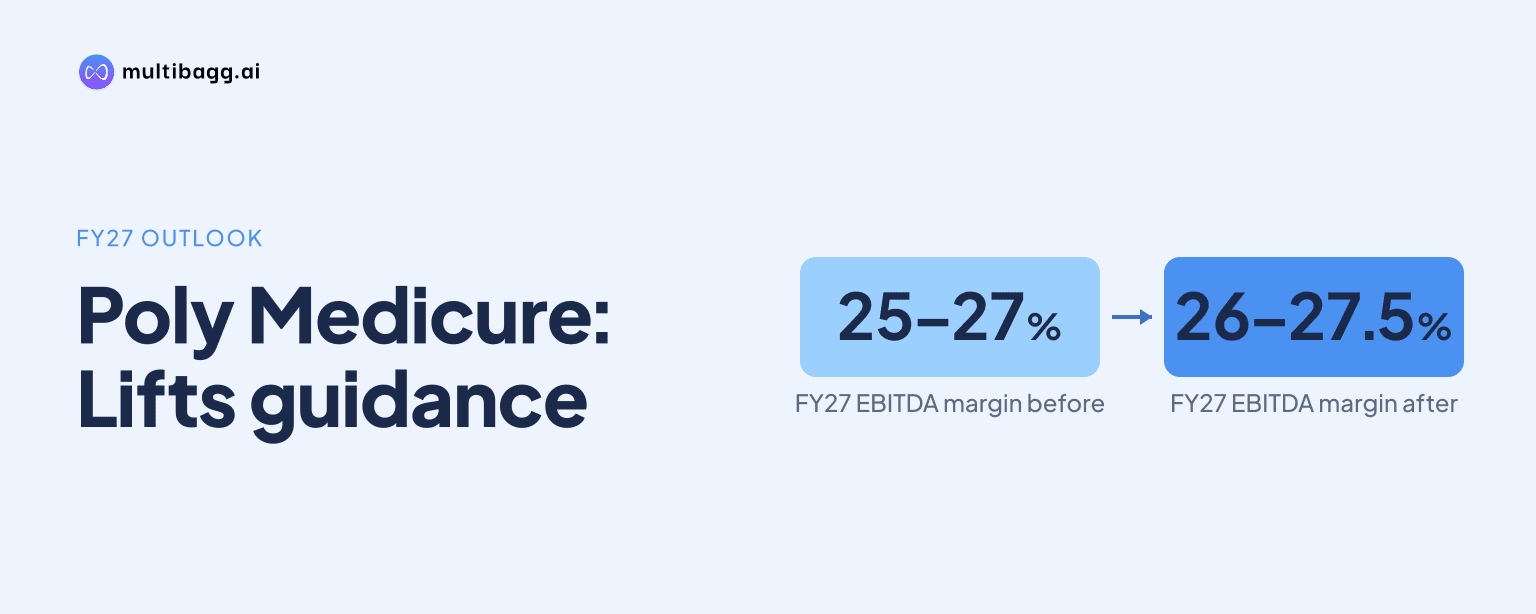
Poly Medicure Limited raised its FY27 standalone earnings before interest, tax, depreciation and amortisation (EBITDA) margin guidance to 26%-27.5% from 25%-27% after H1 FY27 gross margin increased 111 basis points to 70.1%, despite management's earlier expectation of a 200-300-basis-point impact from raw-material inflation.
Know Poly Medicure inside out
Results, valuation, peers and who's buying, in one view.
Why did Poly Medicure raise its FY27 EBITDA-margin guidance?
Poly Medicure raised its standalone FY27 EBITDA-margin outlook because H1 FY27 profitability exceeded its earlier assumptions on raw-material costs. Management increased the range to 26%-27.5% from 25%-27%, citing proactive inventory management, calibrated price increases and a greater focus on higher-value products.
Standalone gross profit rose 17% to Rs 645 crore in H1 FY27, while gross margin expanded by 111 basis points to 70.1%. Operating EBITDA increased 20% to Rs 255 crore, and profit after tax was Rs 180 crore, or a reported 18.6% margin. At the beginning of FY27, management had expected the West Asia crisis to reduce gross margin by 200-300 basis points through higher raw-material prices.
Q2 FY27 supplied further evidence for the revised outlook. Standalone operating EBITDA rose 20% to Rs 134 crore and the EBITDA margin was 27.4%, within the new 26%-27.5% full-year range. Q2 gross profit increased 16% to Rs 336 crore, although the quarterly gross margin of 68.9% was lower than the 70.1% recorded across H1.
What revenue guidance has Poly Medicure retained for FY27?
Poly Medicure retained FY27 standalone revenue guidance of Rs 1,900 crore-Rs 1,950 crore while lifting its margin range. Management also retained its targets for standalone domestic revenue growth of 20% and international revenue growth of 15%, alongside consolidated revenue guidance of Rs 2,300 crore-Rs 2,400 crore.
Standalone H1 revenue grew 15% to Rs 919 crore, comprising domestic revenue of Rs 318 crore, up almost 20%, and international revenue of Rs 595 crore, up about 12.5%. In Q2, revenue increased 17% to Rs 488 crore as domestic revenue rose 22% to Rs 172 crore and international revenue grew 15% to Rs 313 crore.
International growth accelerated from 10% in Q1 to 15% in Q2, according to management, while H1 growth was 12.5%. Management said the annualised revenue run rate after Q2 was close to the level required for its full-year guidance. Domestic revenue remained the faster-growing reported stream in Q2, at 22% growth versus 15% internationally.
How did Poly Medicure mitigate raw-material and freight costs?
Poly Medicure said it mitigated the expected gross-margin effect of raw-material inflation through inventory actions, calibrated price hikes and sales of higher-value products. These measures coincided with a 111-basis-point H1 expansion in standalone gross margin to 70.1%, rather than the decline management had previously anticipated.
Management also referred to higher freight costs, but did not quantify the savings from inventory management, the size of price increases or the product-mix contribution. It said the margin improvement came despite both raw-material and freight headwinds, while the revised 26%-27.5% EBITDA-margin guidance applies only to the standalone business.
Growth was distributed across several businesses in H1 FY27. Infusion therapy, the largest disclosed segment, grew 11% to Rs 542 crore, while renal revenue increased 7.5% to Rs 94 crore. The other segments category, including critical care and transfusion systems, rose 23% to Rs 317 crore, providing a broader sales base for management's higher-value-product strategy.
International commercial activity also expanded during the six months to September 30, 2026. Poly Medicure added 30 customers and said it was raising its share of revenue from existing customers through cross-selling. The call did not disclose the revenue or margin contribution of those new customers, so the direct financial impact cannot be measured from the reported figures.
Got a follow-up? Ask IRIS
How do consolidated results and regional trends compare?
Poly Medicure kept consolidated FY27 EBITDA-margin guidance unchanged at 23%-25%, unlike the higher standalone range. Consolidated H1 operating EBITDA rose 19% to Rs 266 crore, and management said that figure included set-up costs for its new United Kingdom and Brazil subsidiaries.
Consolidated H1 revenue increased 31% to Rs 1,106 crore, while organic consolidated revenue, excluding acquisitions, rose 14%. Gross profit grew 36% to Rs 793 crore and gross margin expanded 270 basis points to 71.7%. Management attributed the consolidated gross-margin change to acquired businesses with better margin profiles and a larger contribution from value-added products.
Regional trends were uneven. Organic Europe revenue grew close to 40% in Q2 and 29% in H1, while rest-of-world revenue declined 7% in Q2 and 1.8% in H1 amid West Asia logistics disruptions. Management said container availability, difficulties reaching ports around Hormuz and higher freight rates were delaying orders even though underlying demand remained intact.
Acquired businesses added to the group revenue base but had different growth conditions. Orthopaedics, reflecting Citieffe's consolidation, contributed Rs 92 crore in H1 and Rs 43 crore in Q2, while cardiology, led by PendraCare, contributed Rs 56 crore and Rs 27 crore respectively. Management said Citieffe faced delayed Italian public tenders, while PendraCare's Middle East exposure affected its growth.
What capital spending and strategic initiatives are under way?
Poly Medicure maintained FY27 capital-expenditure guidance of Rs 200 crore-Rs 225 crore after reporting Rs 124 crore of spending in H1. Management disclosed Rs 124 crore of India-business expenditure and Rs 15 crore of overseas-business expenditure in its call, without providing a reconciliation between those stated amounts and the H1 total.
The group reported liquidity of Rs 839 crore as of September 30, 2026, against consolidated debt of Rs 377 crore and a stated net cash position of Rs 460 crore. These figures accompany investment in new overseas operations, including first shipments to Brazil in October and a direct United Kingdom presence intended to pursue opportunities under the India-UK free-trade agreement.
Management said it was working on three new United Kingdom projects. It expects the first project to go live in Q1, the second in Q4 of the current financial year and the third in Q3 of the following financial year, while also referring to another project anticipated in Q1 of the following year. The call did not provide expected revenue or margin from these projects.
Conclusion
The upgraded standalone margin outlook reflects a reported H1 FY27 combination of 15% revenue growth, a 111-basis-point gross-margin increase to 70.1% and 20% operating EBITDA growth to Rs 255 crore. Poly Medicure retained its revenue targets, indicating that management's revised profitability view is based on cost mitigation and product mix rather than a reduction in planned sales growth.
Next, management's ability to maintain the 26%-27.5% standalone EBITDA-margin target will depend on raw-material and freight conditions as well as delivery of 20% domestic and 15% international growth. Investors will also watch the unresolved anti-dumping case filed at the end of June, the planned United Kingdom project launches and the remaining FY27 capital expenditure within the Rs 200 crore-Rs 225 crore guidance range.