










Polymed uses Plan1Health model for European integration
Key highlights
- Plan1Health revenue rose from €49 lakh in 2022 to €1.05 crore in 2025, while EBITDA margin rose from 4.5% to 13.4%.
- Polymed acquired 90% of PendraCare in 2025 at an enterprise value of €1.88 crore.
- Polymed acquired 100% of Citieffe in 2025 at an enterprise value of about €3.10 crore.
- Polymed held about Rs 839 crore of cash and cash equivalents on September 30, 2026.
powered by IRIS
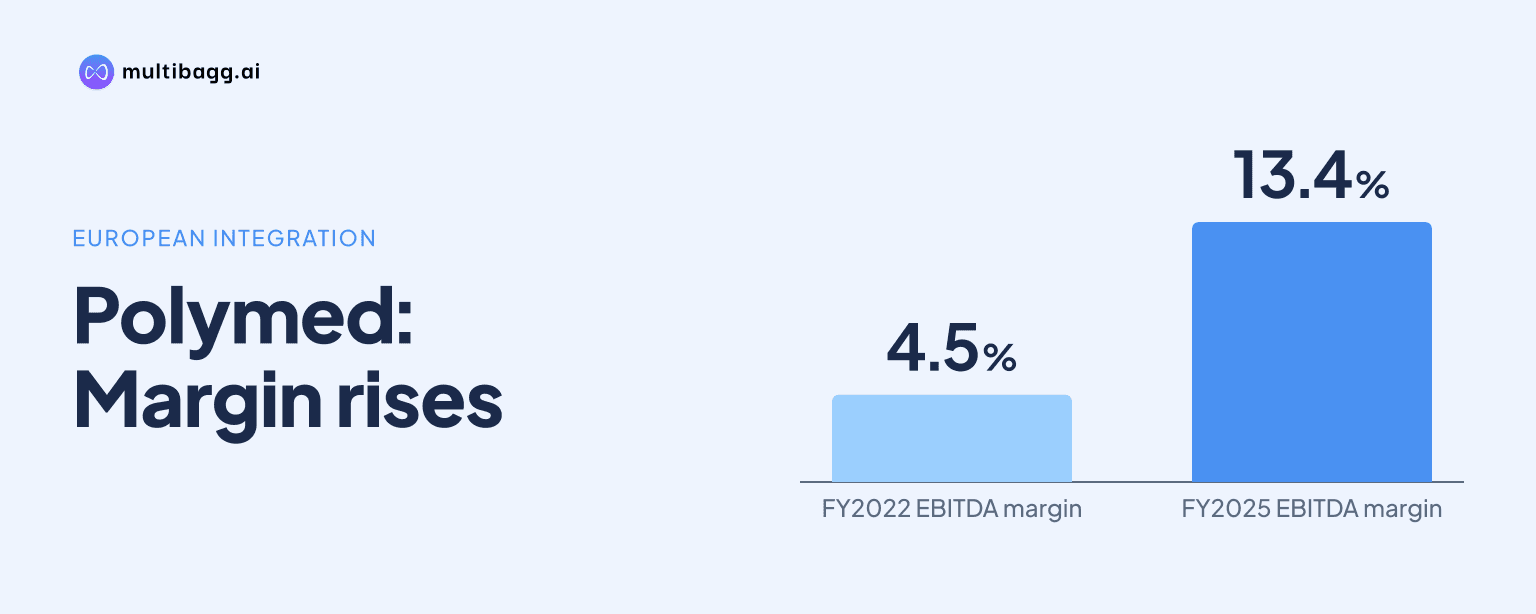
Poly Medicure plans to replicate its Plan1Health integration model for PendraCare and Citieffe, using product launches, Indian manufacturing, direct sales, distribution and research collaboration after Plan1Health revenue reached €1.05 crore and its EBITDA margin reached 13.4% in 2025. The two newer European acquisitions were completed in 2025.
Know Poly Medicure inside out
Results, valuation, peers and who's buying, in one view.
How did Plan1Health perform after Polymed acquired it?
Polymed’s reported Plan1Health performance provides the evidence behind its stated integration approach: revenue rose 2.2 times, EBITDA rose 6.4 times and EBITDA margin increased by 890 basis points. Polymed acquired 100% of the Italy-based oncology-focused business in 2019 at an enterprise value of about €42 lakh. Plan1Health had operated since 1995 and developed and sold long-term infusion devices, oncology products, pain-control devices and implantable products.
Plan1Health’s revenue increased from €49 lakh in 2022 to €81 lakh in 2024 and €1.05 crore in 2025. Its EBITDA margin rose from 4.5% in 2022 to 10.9% in 2024 and 13.4% in 2025. The progression from 2022 to 2025 is the operating record management cites in its plan to replicate the Plan1Health playbook for PendraCare and Citieffe.
Polymed lists five actions used at Plan1Health: accelerated product launches, Indian manufacturing to reduce cost, investment in direct-sales capabilities, wider distribution, and collaboration on research and development, or R&D, and marketing. The original acquisition rationale included entry into critical care, clinical data and technology, and regulatory and technical advantages in developed markets. Plan1Health had European Union Medical Device Regulation and CE-compliant products, an ISO Class 7 clean room, and several Class III medical devices.
How will Polymed integrate PendraCare and Citieffe?
Polymed plans to integrate PendraCare and Citieffe by leveraging product and customer strengths, collaborating on R&D and expanding production capabilities. The programme forms part of its Polymed 3.0 plan from FY2027 onwards, which also includes doubling R&D spending and launching 25 to 30 products annually. These are management’s disclosed plans, rather than reported integration results for the two 2025 acquisitions.
For PendraCare, Polymed identifies supply-chain and procurement integration, R&D collaboration, use of the acquired distribution network and deeper global cardiology penetration as expected synergies. Polymed acquired 90% of the Netherlands-based business in 2025 at an enterprise value of €1.88 crore. PendraCare supplies interventional cardiology catheters across more than 50 countries, works with more than 50 distributors and has annual capacity of more than 15 lakh units.
For Citieffe, Polymed identifies deeper penetration in the United States and Europe, portfolio expansion, R&D collaboration, and manufacturing and procurement cost savings. It acquired 100% of the Italy-based trauma and extremity implant business in 2025 at an enterprise value of about €3.10 crore. Citieffe has two manufacturing facilities covering 2,100 square metres, more than 25 patents and sales across more than 30 countries.
The three transactions add distinct device categories beyond Polymed’s established infusion portfolio. Plan1Health supplies oncology-oriented long-term infusion and critical-care devices, PendraCare adds guiding and diagnostic catheters for cardiology, and Citieffe supplies trauma and extremity products including internal and external fixators, instruments and navigation systems. Infusion therapy represented about 53% of Polymed’s FY2026 revenue, down from about 68% in FY2020 as newer categories expanded.
Got a follow-up? Ask IRIS
What do PendraCare and Citieffe contribute to Polymed?
PendraCare contributed a catheter platform with CY2025 revenue of about €82 lakh and gross profit of about €63 lakh. Guiding catheters made up 70% of its CY2025 product mix, diagnostic catheters represented 23%, and other operating revenue accounted for 7%. Its manufacturing is ISO 13485 and United States Food and Drug Administration, or FDA, approved, while product registrations cover more than 60 countries, including Europe and the US.
PendraCare’s next disclosed operational step is a new lease to consolidate operations into about 2,300 square metres, with transition expected in CY2028. It currently operates from three leased facilities and has 1,150 square metres of cleanroom space. Management identifies expansion of the distribution network and new contract development and manufacturing organisation projects as growth drivers, but provides no revenue target for either initiative.
Citieffe reported CY2025 revenue of about €1.77 crore and gross profit of about €1.66 crore. It reported a number-two position in Italy and Mexico with about 12.0% market share, while more than 85% of sales came from countries where it has a direct presence. Its customer complaint rate was below 0.001%, and it had more than 90 employees, including five in R&D and more than 50 key opinion leaders.
Citieffe’s disclosed commercial plan prioritises the US, where the presentation states orthopaedics prices are four to five times those in Europe. Management plans to add plates to the portfolio, which it says would double the total addressable market. Citieffe has Medical Device Regulation clearance, FDA registrations, registrations in Latin America and more than 25 countries, and a CY2025 sales mix of 45% Europe, 36% US and 19% rest of world.
How is Polymed expanding direct-market access?
Polymed’s direct-market strategy combines organic and inorganic expansion in Brazil, Southeast Asia and Europe, use of existing customer relationships, and new product registrations. The company links this effort to its Polymed 3.0 objective of deepening direct customer access following FY2026 revenue of Rs 1,875 crore. Its plan also includes adding more than 100 sales associates annually and registering more than 30 new products in Europe.
Polymed’s US plan includes 15 approvals obtained, more than 10 approvals in the pipeline, group purchasing organisation contracts across multiple accounts and launches of new high-technology products. The presentation does not disclose US revenue for these activities. Citieffe’s direct presence in countries representing more than 85% of sales and PendraCare’s network of more than 50 distributors are the acquired commercial channels disclosed alongside the strategy.
Polymed has also outlined manufacturing and funding measures. It lists two upcoming plants and infrastructure for the next three to five years of growth, while it initiated construction of three new plants in 2025 and operationalised the Haridwar plant in 2026. Cash and cash equivalents stood at about Rs 839 crore on September 30, 2026, which Polymed says is reserved for strategic initiatives.
Polymed’s financial performance changed between FY2025 and FY2026 as revenue increased from Rs 1,670 crore to Rs 1,875 crore and gross-profit margin rose from 66.7% to 68.2%. Operating EBITDA was Rs 459 crore in FY2025 and Rs 458 crore in FY2026, causing margin to decline from 27.5% to 24.4%. Profit after tax fell from Rs 339 crore to Rs 321 crore over the same period.
Conclusion
Polymed’s disclosed strategy is to apply Plan1Health’s product-launch, manufacturing, direct-sales, distribution and R&D actions to higher-complexity cardiology and orthopaedics businesses in Europe. Plan1Health’s reported move from €49 lakh of revenue and a 4.5% EBITDA margin in 2022 to €1.05 crore and 13.4% in 2025 is the clearest operating evidence presented for that model.
The next disclosed milestones are PendraCare’s planned CY2028 facility consolidation, Citieffe’s proposed addition of plates, and Polymed’s target of 25 to 30 annual product launches. Management also lists more than 10 US approvals in the pipeline, more than 30 European product registrations and two upcoming plants, but it has not disclosed acquisition-specific financial targets for PendraCare or Citieffe.