










Sanghvi Movers Defers Rs 80-90 Crore Saudi Capex to FY28
Key highlights
- Sanghvi Movers moved Rs 80 crore to Rs 90 crore of Saudi Arabia capex to FY28 because logistics disruptions delayed crane deployment.
- Sanghvi Movers' GCC crane-rental business reported 86% H1 FY27 utilisation, a 3.80% yield and a 24% EBITDA margin.
- Sanghvi Movers capitalised Rs 182 crore of its Rs 583 crore FY27 capex ceiling by H1 FY27, leaving Rs 401 crore pending.
- Sanghvi Movers reaffirmed FY27 total-income guidance of Rs 1,400 crore to Rs 1,500 crore and EBITDA guidance of Rs 525 crore to Rs 575 crore.
powered by IRIS
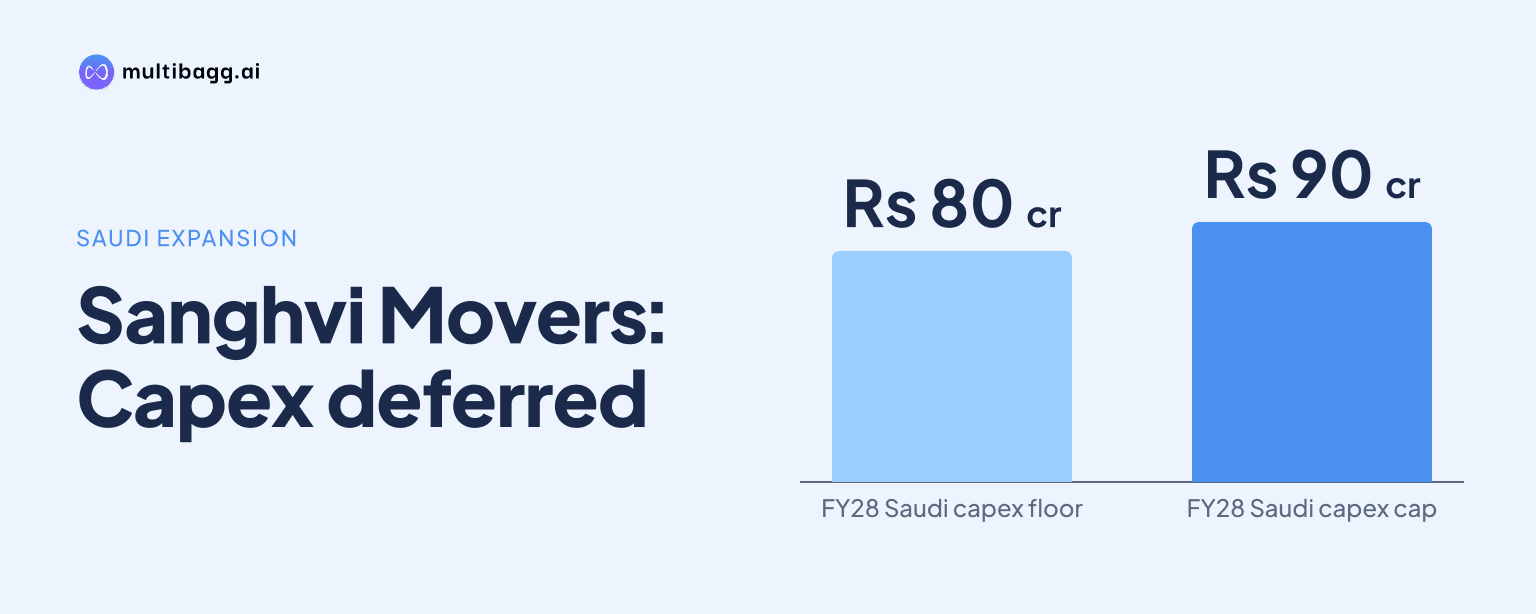
Sanghvi Movers Limited has deferred Rs 80 crore to Rs 90 crore of Saudi Arabia capital expenditure to FY28 after shipping disruption, vessel constraints and port congestion delayed crane deployment, while its Gulf Cooperation Council, or GCC, crane-rental business recorded 86% utilisation in H1 FY27 and a 3.80% rental yield.
Know Sanghvi Movers inside out
Results, valuation, peers and who's buying, in one view.
Why has Sanghvi Movers deferred Saudi Arabia capex?
Sanghvi Movers deferred the Saudi Arabia spending because logistics constraints have delayed the delivery and deployment of new cranes. Management said on November 3, 2026 that West Asia shipping disruption, vessel availability constraints and port congestion had affected deployment timing, requiring part of the Kingdom of Saudi Arabia, or KSA, investment to be re-phased to FY28.
Management described the action as a response to timing conditions rather than a change in its long-term view of the Saudi market. It said procurement is being aligned with contracted demand and prioritised toward higher-return assets, while larger cranes will await more normal shipping costs before mobilisation.
How much Saudi Arabia capex has Sanghvi Movers moved to FY28?
Sanghvi Movers has postponed Rs 80 crore to Rs 90 crore of its designed capital-expenditure plan to FY28. The deferred sum is part of the revised FY27 capital-expenditure ceiling of Rs 583 crore, which includes carry-forward capex from FY26 and the revised FY27 plan.
Sanghvi Movers had capitalised Rs 182 crore by H1 FY27, leaving Rs 401 crore pending for H2 FY27. Management said about 96% of the planned capex pool relates to revenue-generating assets, so the Saudi deferral primarily postpones additional crane capacity rather than cancelling the group’s asset-investment programme.
Management did not commit to bringing the deferred KSA capex back into FY27 if logistics improve. Managing Director Rishi Sanghvi said the disruption was not limited to the West Asia conflict because logistics and shipping-chain disruption could take time to normalise, and the company was waiting for shipping costs to normalise before moving some larger cranes.
Is Saudi demand still supporting Sanghvi Movers' expansion plan?
Sanghvi Movers said Saudi demand and enquiry flow remain sufficient, while cranes already deployed are highly utilised and earning above-target yields. The GCC crane-rental business reported H1 FY27 total income of Rs 39 crore, utilisation of 86%, a yield of 3.80% and a positive EBITDA margin of 24%.
The 3.80% H1 yield was above management’s annual target of 3.5%, and GCC utilisation rose to 87% in Q2 FY27. Management said the Saudi business was EBITDA-positive and generated cash profit during the quarter, although the reported GCC margin included start-up costs incurred before commercial operations commenced.
The immediate effect is slower scale-up in Saudi Arabia because additional cranes cannot yet be deployed. Management expects the EBITDA margin to improve as the business reaches scale, but this is its expectation for next year’s full-year guidance rather than a reported FY27 outcome.
Got a follow-up? Ask IRIS
How does the Saudi delay compare with Sanghvi Movers' Indian operations?
Sanghvi Movers faced a different constraint in India during Q2 FY27, where monsoon conditions reduced crane utilisation to 71% from 86% in Q1 FY27. The 71% level was still above 70% a year earlier, while yield improved to 2.20% from 2.04%, according to management.
For H1 FY27, the India and Botswana crane-rental business generated total income of Rs 406 crore, utilisation of 78%, yield of 2.24% and an EBITDA margin of 46%. Compared with the GCC business’s Rs 39 crore of income and 86% utilisation, India’s near-term issue was seasonal project activity, while Saudi Arabia’s was the delayed physical movement of new cranes.
The group’s revenue mix is also changing. H1 FY27 revenue was approximately 62% crane rental, 36% renewable engineering and construction, or E&C, and 2% project engineering, procurement and construction, or EPC; management now expects a roughly 60:40 crane-rental and renewable E&C mix for the full year, versus its earlier two-thirds and one-third expectation.
What does the deferral mean for Sanghvi Movers' FY27 targets?
Sanghvi Movers reaffirmed FY27 guidance for total income of Rs 1,400 crore to Rs 1,500 crore and EBITDA of Rs 525 crore to Rs 575 crore despite the Saudi capex deferral. In H1 FY27, revenue from operations increased 36% year on year to Rs 657 crore, EBITDA rose 25% to Rs 245 crore and profit after tax increased 22% to Rs 106 crore.
The order book stood at Rs 1,582 crore on October 23, 2026, up 26% from Rs 1,253 crore on July 24, 2026. It comprised Rs 683 crore in India and Botswana crane rental, Rs 45 crore in GCC crane rental and Rs 854 crore in renewable E&C, although management said 8% to 10%, or Rs 140 crore to Rs 160 crore, could spill into the next year because of execution and revenue-recognition delays.
Operating cash flow was about Rs 231 crore in H1 FY27, equal to 82% of full-year FY26 cash flow. Net debt was Rs 391 crore on September 30, 2026 after a Rs 414 crore treasury position, while gross debt stood at Rs 805 crore and the gross debt-to-equity ratio was 0.58 times, below management’s FY27 ceiling of 0.72 times.
Conclusion
The Saudi capex deferral changes the timing of Sanghvi Movers’ expansion rather than its stated demand assessment. The company has shifted Rs 80 crore to Rs 90 crore to FY28 while the GCC business reported 86% H1 FY27 utilisation, a 3.80% yield above its 3.5% target and a 24% EBITDA margin; meanwhile, India and Botswana crane rental delivered Rs 406 crore of H1 income at a 46% margin.
The next disclosed milestones are execution of the Rs 401 crore of FY27 capex still pending and delivery against total-income guidance of Rs 1,400 crore to Rs 1,500 crore. Management’s FY28 deployment decision will depend on vessel availability, port conditions and shipping-cost normalisation, while Rs 140 crore to Rs 160 crore of the current order book may spill into the next year.