










Sanghvi Movers renewable E&C mix set to reach 40% FY27 revenue
Key highlights
- Sanghvi Movers expects renewable E&C to contribute about 40% of FY27 revenue, versus 36% in H1 FY27.
- Renewable E&C generated Rs 365 crore of H1 FY27 total income with an EBITDA margin of about 14%.
- India and Botswana crane rental reported a 46% H1 FY27 EBITDA margin, compared with about 14% for renewable E&C.
- Sanghvi Movers’ renewable E&C order book stood at Rs 854 crore on October 23, 2026.
powered by IRIS
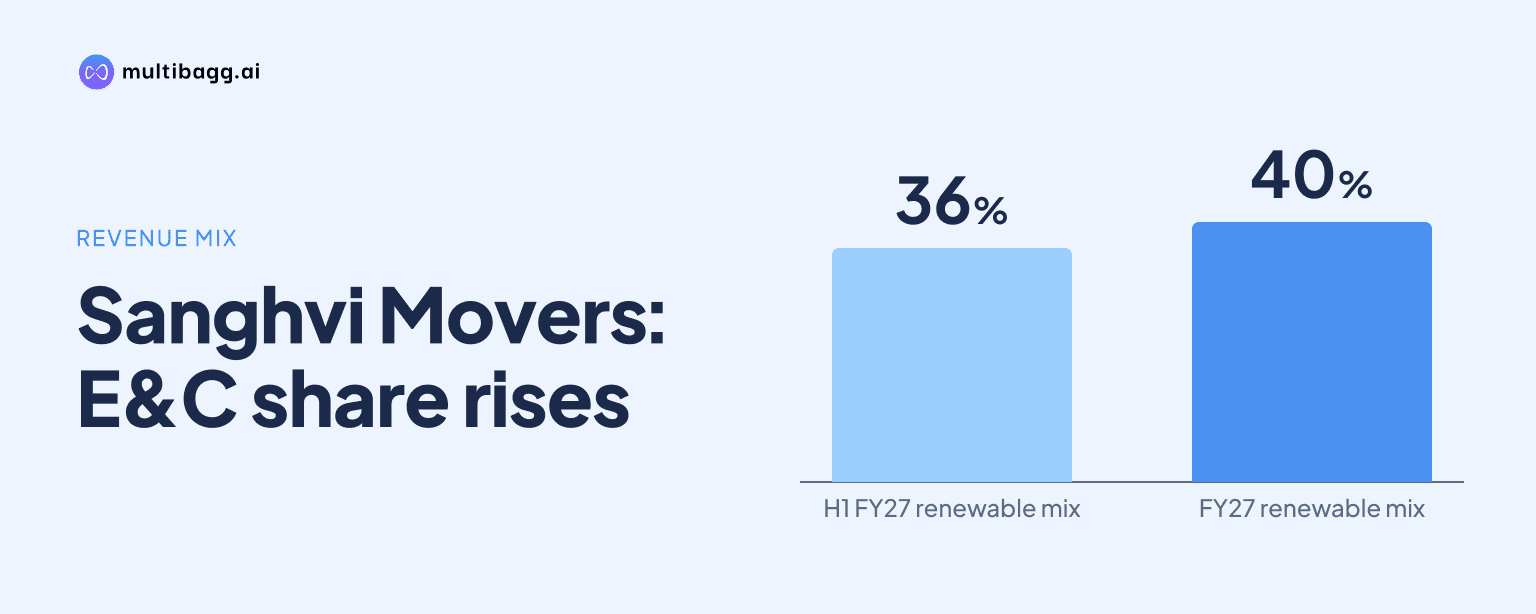
For FY27, Sanghvi Movers Limited expects renewable Engineering and Construction to account for about 40% of revenue, after the asset-light business generated Rs 365 crore of total income in the first half, or H1, ended September 30, 2026. Management said the change lifts absolute earnings before interest, tax, depreciation and amortisation and return on capital employed, while moderating the reported margin percentage.
Know Sanghvi Movers inside out
Results, valuation, peers and who's buying, in one view.
Why is Sanghvi Movers targeting a 40% renewable mix?
Sanghvi Movers is targeting an approximately 60:40 FY27 revenue mix between crane rental and renewable Engineering and Construction, or E&C. This revises management’s earlier expectation of about two-thirds from crane rental and one-third from renewable E&C, reflecting a larger expected contribution from the renewable project-execution business.
In H1 FY27, crane rental represented about 62% of group revenue, renewable E&C represented 36%, and project engineering, procurement and construction, or EPC, represented 2%. The four-percentage-point gap between the H1 renewable share and the full-year expectation indicates that management expects renewable E&C to comprise a greater part of second-half revenue.
Sanghvi Movers reported revenue from operations of Rs 657 crore for H1 FY27, up 36% year on year, while total income increased 38% to Rs 689 crore. In Q2 FY27, revenue from operations was Rs 277 crore, 32% above Rs 210 crore in Q2 FY26, although management said it was lower than Q1 because of renewable project-execution phasing, monsoon conditions in India and the timing of Middle East crane deployments.
How does renewable E&C change Sanghvi Movers’ margins and returns?
Sanghvi Movers said renewable E&C increases absolute earnings before interest, tax, depreciation and amortisation, or EBITDA, and is accretive to return on capital employed, or ROCE, but reduces the blended EBITDA margin percentage because renewable E&C margins are below crane-rental margins. Renewable E&C generated an EBITDA margin of about 14% in H1 FY27, compared with 46% for the India and Botswana crane-rental business.
The difference is visible in the group results as the business mix changes. Sanghvi Movers’ H1 FY27 EBITDA rose 25% year on year to Rs 245 crore, while the blended margin was 36%; Q2 EBITDA increased 20% to Rs 106 crore, also at a 36% margin. Revenue from operations grew 36% in H1, faster than EBITDA, alongside the increased contribution from the lower-margin renewable E&C business.
Renewable E&C’s 63% ROCE on a trailing 12-month basis reflects its asset-light model, according to management. Management also said margins should settle within its indicated range as the business scales, while execution timing and percentage-of-completion accounting may cause quarter-to-quarter variation in reported results.
Got a follow-up? Ask IRIS
What supports Sanghvi Movers’ renewable E&C revenue plan?
Sanghvi Movers had a renewable E&C order book of Rs 854 crore as of October 23, 2026, making it the largest component of the group’s Rs 1,582 crore order book. The group order book had increased 26% from Rs 1,253 crore reported on July 24, 2026, while the enquiry pipeline was about Rs 6,700 crore.
Management said the Rs 1,582 crore order book was executable in FY27, but identified an 8% to 10% possibility that some work could spill into the next financial year. It cited grid connectivity, power-purchase-agreement offtake, site availability, wind-turbine-generator supply from original equipment manufacturers, prolonged monsoon delays and internal project-scheduling challenges as factors that can delay E&C revenue recognition.
Renewable E&C had days sales outstanding, or DSO, below 60 days in H1 FY27, compared with group DSO of 81 days and 89 days for India and Botswana crane rental. Group cash flow from operations was about Rs 231 crore in H1 FY27, equal to 82% of the full FY26 amount, while management described the lower DSO in renewable E&C as part of improved working-capital performance.
What remains important for Sanghvi Movers’ crane-rental business during the mix shift?
Sanghvi Movers’ crane-rental business remains the larger planned FY27 revenue contributor at about 60% of the expected mix, supported by Rs 728 crore of order book across India, Botswana and the Gulf Cooperation Council, or GCC. That amount included Rs 683 crore in India and Botswana crane rental and Rs 45 crore in GCC crane rental as of October 23, 2026.
India and Botswana crane-rental fleet utilisation was 78% in H1 FY27, with yield of 2.24%. In India, Q2 utilisation was 71%, compared with 86% in Q1 and 70% in the corresponding prior-year period, as management attributed the sequential decline to the monsoon; Q2 yield improved to 2.20% from 2.04%.
The GCC crane-rental business reported H1 total income of Rs 39 crore, utilisation of 86%, yield of 3.80% and a positive EBITDA margin of 24%. Management said shipping constraints, port congestion and delayed crane deliveries slowed the near-term Saudi Arabian expansion, leading it to move part of planned capital expenditure to FY28 rather than alter its long-term view of the market.
Sanghvi Movers set an FY27 capital-expenditure ceiling of Rs 583 crore, including FY26 carry-forward expenditure, of which Rs 182 crore was capitalised in H1 and Rs 401 crore remained for the second half. About 96% of the planned pool relates to revenue-generating assets, and management said procurement would be aligned with contracted demand and prioritised towards higher-return assets.
Conclusion
The expected 40% renewable E&C share changes Sanghvi Movers’ FY27 revenue composition from its earlier one-third expectation. Renewable E&C combines an asset-light 63% trailing-12-month ROCE with a 14% H1 EBITDA margin, below the 46% margin reported in India and Botswana crane rental, explaining management’s view that the mix supports absolute EBITDA and returns while reducing the group’s blended margin percentage.
The next measures to watch are whether renewable E&C converts its Rs 854 crore order book within FY27 and whether the disclosed 8% to 10% potential spillover materialises. Management reaffirmed FY27 total-income guidance of Rs 1,400 crore to Rs 1,500 crore and EBITDA guidance of Rs 525 crore to Rs 575 crore, while Middle East crane deliveries and the remaining Rs 401 crore FY27 capital-expenditure plan remain timing factors.